

|
시장보고서
상품코드
2125723
농업 CRO 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Agriculture CRO Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
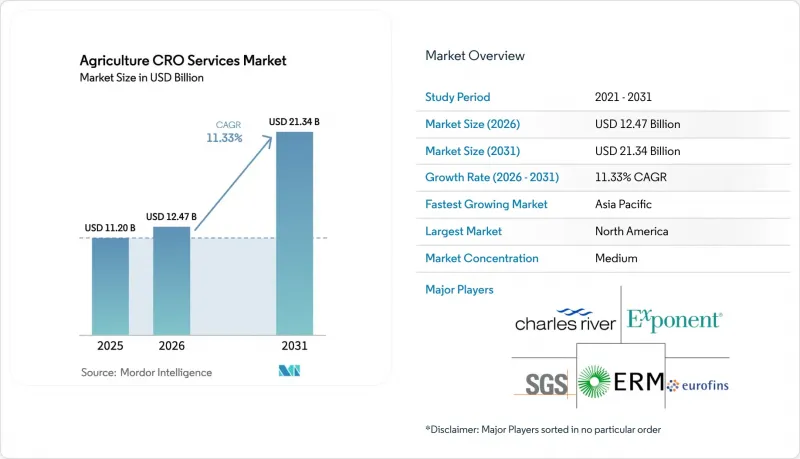
에 의하면, 농업 CRO 서비스 시장 규모는 2025년에 112억 달러로 평가되었고, 2026년 124억 7,000만 달러에서 2031년까지 213억 4,000만 달러에 이를 것으로 추정되며, 예측 기간(2026-2031년) CAGR은 11.33%를 나타낼 전망입니다.
본 보고서는 서비스 유형별(현장 서비스, 실험실 서비스, 규제 관련 서비스, 기타 서비스), 부문별(작물 보호용 화학물질, 비료, 종자), 지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 농업 CRO 서비스 시장 동향 및 인사이트
급증하는 신약 개발 비용을 억제하기 위한 연구개발 아웃소싱 증가
신약 개발 비용의 급등으로 인해 농약 제조업체들은 핵심 업무 이외의 과학 활동을 외부에 위탁하고 있습니다. 바이엘의 2024년 제출 서류는 이러한 동향을 보여주고 있으며, 그룹 전체의 연구비가 58억 6,000만 유로(64억 4,600만 달러)에 달함에도 불구하고, 크롭 사이언스 부문은 어려움에 직면해 있습니다. CRO(위탁 연구 기관)와의 제휴를 통해 시장 출시까지의 기간을 최대 2년 단축할 수 있으며, 연구 투자의 수익성을 높일 수 있습니다. 각 기업은 고도의 독성학, 여러 거점에서의 현장 시험, 예측 모델링과 같은 전문적인 서비스에 대해 외부 파트너에 의존함으로써 막대한 사내 인프라 비용을 피하고 있습니다. 세계 경쟁 환경은 효율적인 자본 배분의 중요성을 부각시키고 있으며, 아웃소싱의 지속적인 확장을 촉진하고 있습니다. 이러한 추세에 따라 초기 신약 스크리닝부터 규제 당국에 대한 신청에 이르기까지 농업 부문에서 CRO 서비스에 대한 수요가 증가하고 있습니다.
규제 강화에 따른 제3자 규정 준수 전문 지식에 대한 수요 증가
미국 환경보호청(EPA)의 2024년 프레임워크에서는 신청자가 EPA, 식품의약국(FDA), 미국 농무부(USDA)의 각 데이터 요건을 반영해야 하므로, 이에 따라 신청 서류의 복잡성과 규정 준수 비용이 증가하고 있습니다. 국제적인 규제 변경 사항으로는 아르헨티나 농업식품위생품질청(SENASA)의 결의안 제1081/2024호가 있으며, 엄격한 기술 요건을 유지하면서 시험 프로토콜이 갱신되었습니다. 각 기업은 제제, 미생물, 유전자 편집 종자에 관한 규정을 준수하기 위해 전문 CRO 규제 대응 팀과 협력하고 있습니다. 현재 CRO 파트너 선정은 GLP(우수 실험실 관리 기준), 신청 서류의 조화, 여러 관할 구역에 대한 신청과 관련된 전문 지식에 크게 의존하고 있습니다. 그 결과, 규제 컨설팅은 농업 부문의 CRO 서비스 시장에서 가장 빠르게 성장하는 서비스 부문이 되었습니다.
주요 지역의 GLP 인증 현장 부지 부족
규정을 준수하는 시험 포장에 대한 수요가 공급을 초과하고 있어, 제한된 시험 용량을 이용하고자 하는 의뢰사에게는 대기 기간이 발생하고 있습니다. 뉴질랜드 국제인증기관(IANZ)이나 호주의 국립시험기관협회(NATA)와 같은 기관으로부터 인증을 획득하려면 3년에 걸친 절차 외에도 데이터 시스템, 분석 장비, 인재 양성에 대한 막대한 투자가 필요합니다. 인증 시설의 이용이 제한되어 있어 프로젝트 기간이 장기화되고, 여러 거점에서 시험을 진행하는 데 드는 비용이 증가하고 있으며, 이것이 농업 CRO 서비스 시장의 성장 저해 요인이 되고 있습니다. 생물학적 연구의 경우, 격리 시설이나 미생물 모니터링 능력이 요구되기 때문에 추가적인 과제에 직면하고 있지만, 이러한 설비는 대부분의 야외 시험장에 갖추어져 있지 않습니다.
부문 분석
2025년, 농업 CRO 서비스 시장에서 잔류물 분석, 환경 동태 모델링, 유효성 확인에 있어 필수적인 기능을 바탕으로 실험실 서비스가 46.55%의 시장 점유율을 차지했습니다. 각 후원사는 등록 요건을 충족하기 위해 크로마토그래피, 질량 분석, 분자진단을 활용하고 있습니다. 유로핀 사이언티픽(Eurofins Scientific)은 일시적인 고객의 예산 제약으로 인해 아그로사이언스 부문의 매출이 10% 감소했음에도 불구하고, 처리 능력 향상 수요에 대응하기 위해 2024년에 실험실 용량을 9만 8,000제곱미터 확대했습니다. 디지털 정보 기술과 자동화된 시료 처리의 통합은 표준 관행이 되어 데이터 처리 시간을 단축하고 세계 공급업체의 업무 효율을 높이고 있습니다. 분석 인프라의 중앙 집중화로 인해 농업 CRO 서비스 시장에서 이 부문의 지배적 지위가 더욱 공고해지고 있습니다.
규제 컨설팅 서비스는 신청 서류의 복잡화를 배경으로 2031년까지 연평균 성장률(CAGR) 12.64%를 나타낼 것으로 예측됩니다. 생물학적 제제나 유전자 편집 작물의 개발에는 작용기전, 미생물군집에 미치는 영향, 사회경제적 위험을 다룬 종합적인 신청 서류의 제출이 요구됩니다. 독성학, 환경 과학, 법 정책에 대한 전문 지식을 아우르는 다양한 팀을 보유한 CRO가 더 많은 계약을 수주하고 있습니다. SGS의 ‘농장 지속가능성 평가(Farm Sustainability Assessment)’ 프로그램은 실험실 분석과 규정 준수 검증, 인증 감사를 결합함으로써 이러한 서비스의 통합을 입증하고 있습니다. 지역 전문가들은 현지 규제 당국과 견고한 관계를 유지하고 있으며, 이는 지속적으로 확대되고 있는 농업 CRO 서비스 시장 부문에서 전문 지식이 규모의 경제와 더불어 여전히 경쟁력을 갖추고 있음을 보여줍니다.
지역별 분석
2025년 기준, 북미는 농업 CRO 서비스 시장의 54.10% 점유율을 차지했습니다. 이 지역의 강점은 환경보호청(EPA)의 다기관에 걸친 생명공학 프레임워크, 미국 농무부(USDA)의 혁신 보조금, 수백만 헥타르에 달하는 정밀 농업 도입에서 비롯됩니다. 캐나다의 규제 조화와 멕시코에서 계획 중인 글리포세이트 전환으로 인해 조사 프로젝트의 다양성이 확대되고 있습니다. 디지털 농업 검증을 위한 코르테바(Corteva)와 존 디어(John Deere)의 제휴는 CRO 수주를 뒷받침하는 한편, 농업 법안의 인센티브에 따른 탄소 고정량 측정은 지속가능성 검증 분야에서 추가적인 수익 기회를 창출하고 있습니다.
아시아태평양은 연평균 성장률(CAGR) 12.11%로 가장 높은 성장률을 보이고 있습니다. 이 지역의 성장은 중국의 생명공학 규제 개정과 인도의 수출 규정 준수 요건에 힘입고 있습니다. 정부의 현대화 노력과 벤처 자금 증가가 초기 단계의 생물학적 시험을 촉진하고 있습니다. 인증과 관련된 과제는 여전히 남아 있지만, 지역별 ‘우수 실험실 관리 기준(GLP)’ 체계의 도입과 호주의 4,030만 달러 규모 프로그램을 포함한 가뭄 내성 향상 노력으로 인해 역량 측면의 제약은 점차 완화되고 있습니다. 동남아시아에서 센서를 활용한 농업 솔루션이 보급됨에 따라 제3자 검증 서비스에 대한 수요가 증가하고 있습니다.
유럽과 남미는 서로 다르지만 상호 보완적인 성장 궤도를 보이고 있습니다. 유럽의 성장은 ‘그린 딜’과 ‘팜 투 포크’ 이니셔티브에 의해 주도되고 있으며, 생물학적 유효성 시험, 탄소 발자국 검증, 순환형 영양소 조사에 대한 수요를 창출하고 있습니다. 남미는 생물학적 작물 보호 부문에서 두각을 나타내고 있으며, 브라질의 생물제제 시장에서는 미생물 제품과 화학 대체품을 비교하는 전문적인 시험이 요구되고 있습니다. 아르헨티나의 완화된 시험지 선정 정책은 엄격한 데이터 요건을 유지하면서도 국제적인 CRO를 유치하고 있으며, 시장의 규제적 진화를 보여주고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.15According to Mordor Intelligence, the agriculture CRO services market size was valued at USD 11.20 billion in 2025 and estimated to grow from USD 12.47 billion in 2026 to reach USD 21.34 billion by 2031, at a CAGR of 11.33% during the forecast period (2026-2031).
This report is Segmented by Service Type (Field Services, Laboratory Services, Regulatory Services, and Other Services), by Sector (Crop Protection Chemicals, Fertilizers, and Seeds), and by Geography (North America, Europe, Asia-Pacific, South America, Middle East, and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Agriculture CRO Services Market Trends and Insights
Rising Research and Development Outsourcing to Contain Soaring Discovery Costs
Rising discovery costs are driving agrochemical companies to outsource non-core scientific activities. Bayer's 2024 filings demonstrate this trend, as the Crop Science division faces challenges despite the group's total research expenditure of EUR 5,860 million (USD 6,446 million). Contract Research Organization (CRO) partnerships reduce time-to-market by up to two years, enhancing returns on research investment. Companies depend on external partners for specialized services such as advanced toxicology, multi-site field trials, and predictive modeling, avoiding substantial internal infrastructure costs. Global competition emphasizes the importance of efficient capital allocation, supporting continued outsourcing growth. These dynamics increase the demand for agricultural CRO services, ranging from initial discovery screening to regulatory submission.
Regulatory Tightening Drives Demand for Third-Party Compliance Expertise
The Environmental Protection Agency's 2024 framework requires applicants to incorporate data requirements from the Environmental Protection Agency, the Food and Drug Administration, and the United States Department of Agriculture, thereby increasing dossier complexity and compliance costs. International regulatory changes include Argentina's National Service of Agri-Food Health and Quality (SENASA) Resolution 1081/2024, which updated testing protocols while maintaining strict technical requirements. Companies work with specialized CRO regulatory teams to comply with regulations on formulations, microbials, and gene-edited seeds. The selection of CRO partners now depends heavily on their expertise in Good Laboratory Practice, dossier harmonization, and multi-jurisdiction submissions. As a result, regulatory consulting has become the fastest-growing service segment in the agriculture CRO services market.
Shortage of Good Laboratory Practice Qualified Field Sites in Key Geographies
The demand for compliant test plots exceeds supply, creating waiting periods for sponsors seeking access to limited testing capacity. Obtaining certifications from organizations such as International Accreditation New Zealand (IANZ) or Australia's National Association of Testing Authorities (NATA) requires a three-year process and substantial investments in data systems, analytical equipment, and personnel training. The restricted availability of certified facilities extends project timelines and increases costs for multi-location trials, constraining the agriculture CRO services market. Biological research faces additional challenges due to requirements for containment facilities and microbial monitoring capabilities, which are absent in most field stations.
Other drivers and restraints analyzed in the detailed report include:
- Growth in Biologicals and Biosolutions Requiring New Efficacy Trials
- Shift to Data-Driven Portfolio Optimization by Agrochemical Majors
- Privacy and Cyber-Security Breaches Undermining Sponsor Confidence
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Laboratory testing held 46.55% of the agriculture CRO services market share in 2025, driven by its essential functions in residue analytics, environmental fate modeling, and efficacy confirmation. Sponsors utilize chromatography, mass spectrometry, and molecular diagnostics to meet registration requirements. Eurofins Scientific increased its laboratory capacity by 98,000 square meters in 2024 to address higher throughput demands, despite experiencing a 10% decline in agrosciences revenue due to temporary client budget constraints. The integration of digital informatics and automated sample processing has become standard practice, reducing data processing time and enhancing the operational efficiency of global providers. The concentration of analytical infrastructure reinforces this segment's dominant position in the agriculture CRO services market.
Regulatory consulting services are projected to grow at a 12.64% CAGR through 2031, driven by increasing dossier complexity. The development of biologicals and gene-edited crops requires comprehensive submissions addressing mode of action, microbiome effects, and socio-economic risks. CROs with diverse teams encompassing toxicology, environmental sciences, and legal policy expertise are securing more contracts. SGS's Farm Sustainability Assessment program demonstrates this service integration by combining laboratory analysis with compliance verification and certification audits. Regional specialists maintain strong relationships with local regulators, indicating that expertise remains competitive with scale advantages in this expanding segment of the agriculture CRO services market.
Complete Report Scope:
- By Service Type
- Field Services
- Laboratory Services
- Regulatory Services
- Other Services (Product Development Services, Precision Agriculture Services, Seed Services, etc.)
- By Sector
- Crop Protection Chemicals
- Fertilizers
- Seeds
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- North America
Geography Analysis
North America holds 54.10% of the agriculture CRO services market share in 2025. The region's strength stems from the Environmental Protection Agency's multi-agency biotech framework, United States Department of Agriculture innovation grants, and precision farming implementation across millions of hectares. Canada's regulatory alignment and Mexico's planned glyphosate transition expand the diversity of research projects. The collaboration between Corteva and John Deere for digital agriculture validation strengthens CRO bookings, while carbon sequestration measurement under farm bill incentives creates additional revenue opportunities in sustainability verification.
Asia-Pacific demonstrates the highest growth rate at 12.11% CAGR. The region's expansion is supported by China's biotechnology regulation updates and India's export compliance requirements. Government modernization initiatives and increased venture funding facilitate early-stage biological testing. While accreditation challenges remain, the implementation of regional Good Laboratory Practices frameworks and drought resilience initiatives, including Australia's USD 40.3 million program, is reducing capacity limitations. The widespread adoption of sensor-based agronomy solutions in Southeast Asia increases the demand for third-party validation services.
Europe and South America exhibit different but complementary growth trajectories. European growth is driven by the Green Deal and Farm to Fork initiatives, generating demand for biological efficacy testing, carbon footprint verification, and circular nutrient research. South America excels in biological crop protection, with Brazil's biologicals market requiring specialized trials comparing microbial products to chemical alternatives. Argentina's relaxed laboratory selection policies attract international CROs while maintaining rigorous data requirements, demonstrating the market's regulatory evolution.
- Eurofins Scientific SE
- SGS SA
- Charles River Laboratories International, Inc.
- Syntech Research Group, Inc.
- Knoell Germany GmbH
- ERM International Group Limited
- Exponent, Inc.
- Staphyt Group
- Anadiag Group SAS
- RIFCON GmbH
- Ibacon GmbH (Labanalysis Srl)
- Jai Research Foundation
- Smithers Group Inc.
- Laus GmbH
- Ag Metrics Group LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Research and Development Outsourcing to Contain Soaring Discovery Costs
- 4.2.2 Regulatory Tightening Drives Demand for Third-party Compliance Expertise
- 4.2.3 Growth in Biologicals and Biosolutions Requiring New Efficacy Trials
- 4.2.4 Precision Agriculture and Digital Farming Tools Need Validation Studies
- 4.2.5 Shift to Data-Driven Portfolio Optimization by Agrochemical Majors
- 4.2.6 Venture Funding Surge for Ag-Tech Start-Ups Lacking In-house Trial Capacity
- 4.3 Market Restraints
- 4.3.1 Shortage of Good Laboratory Practice Qualified Field Sites in Key Geographies
- 4.3.2 Privacy and Cyber-Security Breaches Undermining Sponsor Confidence
- 4.3.3 Rising Cost of Liability Insurance for Field-testing Live Plots
- 4.3.4 Weather-Related Trial Failures Increasing Project Risk and Cost
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Service Type
- 5.1.1 Field Services
- 5.1.2 Laboratory Services
- 5.1.3 Regulatory Services
- 5.1.4 Other Services (Product Development Services, Precision Agriculture Services, Seed Services, etc.)
- 5.2 By Sector
- 5.2.1 Crop Protection Chemicals
- 5.2.2 Fertilizers
- 5.2.3 Seeds
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.1.4 Rest of North America
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Spain
- 5.3.2.5 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 India
- 5.3.3.3 Japan
- 5.3.3.4 Australia
- 5.3.3.5 Rest of Asia-Pacific
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Chile
- 5.3.4.4 Rest of South America
- 5.3.5 Middle East
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Kenya
- 5.3.6.3 Rest of Africa
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Eurofins Scientific SE
- 6.4.2 SGS SA
- 6.4.3 Charles River Laboratories International, Inc.
- 6.4.4 Syntech Research Group, Inc.
- 6.4.5 Knoell Germany GmbH
- 6.4.6 ERM International Group Limited
- 6.4.7 Exponent, Inc.
- 6.4.8 Staphyt Group
- 6.4.9 Anadiag Group SAS
- 6.4.10 RIFCON GmbH
- 6.4.11 Ibacon GmbH (Labanalysis Srl)
- 6.4.12 Jai Research Foundation
- 6.4.13 Smithers Group Inc.
- 6.4.14 Laus GmbH
- 6.4.15 Ag Metrics Group LLC


