

|
시장보고서
상품코드
2154232
유럽의 플랜팅 기계 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Planting Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
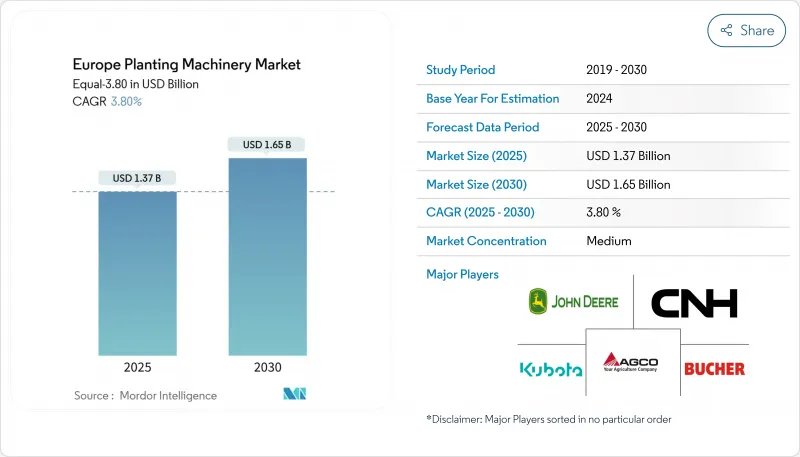
에 따르면 유럽의 플랜팅 기계 시장은 2025년에 13억 7,000만 달러 규모에 달하며, 2026년 14억 2,000만 달러에서 2031년까지 17억 1,000만 달러로 성장하며, 2026-2031년 예측 기간의 CAGR 3.79%로 추이할 것으로 예측됩니다.
유럽 플랜팅 기계 시장의 동향 및 인사이트
유럽연합(EU)의 공동농업정책(CAP) 전략 계획 및 각국의 농업기계 보조금
2023-2027년까지의 공동농업정책(CAP) 전략 계획은 정밀농업 장비 및 디지털 기술을 포함한 투자 조치를 통해 농장의 현대화를 지원하고 있습니다. 2023년 유럽연합 집행위원회의 데이터에 따르면 승인된 CAP 전략 계획에 기반한 투자 지원은 인프라 및 농업 방식의 현대화를 위해 약 40만 개의 농장에 혜택을 제공하는 것을 목표로 했습니다. 이러한 조치는 정밀 제어, 데이터 수집, 투입 자재 관리 기능을 갖춘 파종 기계에 대한 투자를 촉진하는 것입니다. 유럽연합(EU)의 각 회원국은 국가 및 지역의 우선순위에 따라 독자적인 CAP 전략 계획을 시행하고 있으므로, 농업기계 지원 프로그램의 이용 가능 여부와 내용은 유럽 각지에서 다릅니다. 이로 인해 파종기 제조업체와 판매 대리점에게는 해당 지역에서 지원되는 투자 프로그램에 맞춰 장비 사양, 자금 조달 옵션, 기술 지원을 조정할 기회가 생겨, 현대적인 파종기에 대한 수요를 지원하는 결과로 이어집니다.
유럽의 농업 인력 부족과 농업 임금 상승
농업 종사자의 감소에 따라 유럽 전역의 농장에서 기계화 및 노동력 절감 기술의 중요성이 높아지고 있습니다. 2026년에 발표된 유로스타트(Eurostat)의 데이터에 따르면 유럽연합(EU)의 농업 고용은 2013년 전체 고용의 5.2%를 차지했으나, 2023년에는 3.9%로 감소했으며, 농업 종사자 수는 840만 명입니다. 이처럼 농업 종사자 수가 감소함에 따라 생산자들은 더 적은 인력으로 광범위한 면적을 커버하고, 반복적인 수작업 조정을 줄일 수 있는 파종기 도입을 촉진하고 있습니다. 그 결과, 수요는 자동 종자 계량, 카터 압력 조절, 안내 기능, 그리고 운전 효율을 향상시키는 캐빈내 조작 기능을 갖춘 장비로 이동하고 있습니다. 인력 확보가 점점 더 어려워지는 가운데, 신뢰성이 높고 조작하기 쉬운 파종기는 농장이 파종 능력을 유지하면서 수작업에 대한 의존도를 낮추는 데 도움이 되며, 유럽 전역에서 첨단 파종기에 대한 수요를 지원하고 있습니다.
높은 기계 가격과 유럽내 농업 금융 비용의 상승
장비 가격의 급등과 자금 조달 비용의 상승은 특히 현금 흐름이 제한적이거나 수익성이 불확실한 농장에서 첨단 파종 기계에 대한 투자를 제약하는 요인이 될 수 있습니다. 정밀 파종이 가능한 시스템은 일반적으로 기존 장비보다 많은 초기 투자가 필요하지만, 차입 비용의 상승은 장비의 총 소유 비용을 더욱 높일 가능성이 있습니다. 이러한 상황으로 인해 농가는 기계 교체를 미루거나, 사양이 낮은 기종을 선택하거나, 기존 기계를 더 오랫동안 계속 사용하는 경향이 강해질 수 있습니다. 따라서 장비 비용이나 자금 조달의 제약이 농업의 수익성 저하와 겹치게 되면, 유럽의 파종기 시장은 더 큰 압박에 직면하게 될 것입니다. 리스나 계절에 따른 지불 체계, 유연한 장비 금융은 초기 자금 부담을 줄이는 데 도움이 됩니다. 또한 제조사나 판매점이 자금 조달 지원을 제공함으로써 첨단 파종 기술에 대한 접근성을 개선할 수 있습니다.
부문 분석
2025년 기준, 유럽 파종기 시장에서 자동 시스템은 설계 유형별 점유율 58.0%를 차지하며 최대 설계 부문로 자리매김하고 있으며, 2026-2031년까지 연평균 성장률(CAGR) 7.0%로 확대될 것으로 예측됩니다. 이러한 선도적인 위상은 특히 파종 정밀도 향상과 수동 조정 감소를 추구하는 대규모 경작 농장에서 전자식 종자 계량, 섹션 제어 및 커넥티드 조작에 대한 수요가 증가하고 있음을 반영합니다. 자동 시스템은 유럽 전역에서 정밀농업 기술이 널리 보급되고 있는 추세와도 부합합니다. 2025년 11월, LEMKEN GmbH &Co. KG는 ISOBUS iQblue 조작, 개별 열 호퍼, 자동 섹션 제어를 특징으로 하는 정밀 파종기 ‘Faya MF’를 발표하며, 파종 장비에 대한 자동화 기능의 지속적인 통합을 입증했습니다. 유럽 농장에서 정밀 중심의 파종 방식이 점점 더 많이 채택됨에 따라 자동 시스템에 대한 수요가 해당 부문의 성장을 지원할 것으로 예상됩니다.
반자동 시스템은 고사양 장비와 같은 완전한 자동화가 아닌, 특정 전자 기능만을 필요로 하는 농장에 있으며, 중간적인 선택지가 됩니다. 이러한 시스템은 전자적 모니터링 및 제어 등의 기능을 지원하면서도 여전히 작업자의 개입에 크게 의존하고 있습니다. 기계식 시스템은 장비의 합리적인 가격, 조작의 간편함, 확립된 정비 체계가 구매시 중요한 고려 사항이 되는 상황에서 여전히 중요한 선택지로 남아 있습니다. 자동식, 반자동식, 기계식 등 다양한 구성이 마련되어 있으며, 제조사는 유럽 시장 전반에 걸쳐 농장의 규모, 투자 능력, 기술적 요구 사항 및 지역별 서비스 이용 가능성의 차이에 대응할 수 있습니다. 이러한 폭넓은 장비 구성 덕분에 자동 파종 기술의 도입이 확대되는 상황에서도 이 설계 부문 전체의 수요는 유지될 것으로 예상됩니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 디자인별
- 조작별
- 작물 유형별
- 지역별
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 네덜란드
- 폴란드
- 러시아
- 기타 유럽 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Deere & Company
- AGCO Corporation
- KUHN S.A.(Bucher Industries AG)
- Kverneland AS(Kubota Corporation)
- YANMAR HOLDINGS CO., LTD.
- Kubota Corporation
- Mahindra & Mahindra Limited
- CNH Industrial N.V.
- ISEKI & CO., LTD.
- DAEDONG CORPORATION
- YTO Group Corporation(China National Machinery Industry Corporation)
- Zoomlion Heavy Industry Science & Technology Co., Ltd.
- MASCHIO GASPARDO S.p.A.
- AMAZONEN-WERKE H. DREYER SE & Co. KG
- HORSCH Maschinen GmbH
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the Europe planting machinery market was valued at USD 1.37 billion in 2025 and is forecasted to grow from USD 1.42 billion in 2026 to USD 1.71 billion by 2031, at a CAGR of 3.79% during the forecast period 2026-2031.
Europe Planting Machinery Market Trends and Insights
European Union CAP Strategic Plans and national machinery grants
The Common Agricultural Policy (CAP) Strategic Plans for 2023-2027 support farm modernization through investment measures covering precision farming equipment and digital technologies. According to European Commission data in 2023, investment support under the approved CAP Strategic Plans was targeted to benefit close to 400,000 farms for modernization of infrastructure and practices. These measures strengthen the investment case for planting machinery with precision-control, data-capture, and input-management capabilities. As each European Union Member State implements its own CAP Strategic Plan according to national and regional priorities, the availability and design of machinery-support programs vary across Europe. This creates opportunities for planting-machinery manufacturers and dealers to align equipment specifications, financing options, and technical support with locally funded investment programs, supporting demand for modern planting machinery.
European Farm-Labor Shortages and Rising Agricultural Wages
A declining agricultural workforce is increasing the importance of mechanization and labor-saving technologies across European farms. According to Eurostat data published in 2026, agricultural employment in the European Union fell from 5.2% of total employment in 2013 to 3.9% in 2023, with 8.4 million people employed in agriculture. This reduction in available farm labor encourages growers to use planting machinery that can cover larger areas with fewer operators and reduce repetitive manual adjustments. Demand is therefore shifting toward equipment with automated seed metering, coulter-pressure adjustment, guidance, and in-cab controls that improve operating efficiency. As labor availability becomes more constrained, reliable and easy-to-operate planting equipment can help farms maintain planting capacity while reducing dependence on manual intervention, supporting demand for advanced planting machinery across Europe.
High Equipment Prices and Elevated European Farm Financing Costs
High equipment prices and financing costs can constrain investment in advanced planting machinery, particularly for farms operating with limited cash flow or uncertain profitability. Precision-capable planting systems typically require greater upfront investment than conventional equipment, while higher borrowing costs can further increase the total cost of equipment ownership. These conditions can encourage farmers to postpone machinery replacement, choose lower-specification configurations, or continue using existing equipment for longer. The Europe planting machinery market therefore faces greater pressure when equipment costs and financing constraints coincide with weaker farm profitability. Leasing, seasonal payment structures, and flexible equipment financing can help reduce the initial capital burden, while manufacturers and dealers offering financing support can improve access to advanced planting technologies.
Other drivers and restraints analyzed in the detailed report include:
- Climate Volatility and Compressed European Planting Windows
- Replacement Demand from Aging European Machinery Fleets
- Limited Technical Service Capacity for Connected Planting Equipment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automatic systems held 58.0% of the Europe planting machinery market by design in 2025, making them the largest design segment, and are forecast to expand at a 7.0% CAGR between 2026 and 2031. Their leading position reflects increasing demand for electronic seed metering, section control, and connected operation, particularly on larger arable farms seeking greater planting accuracy and reduced manual adjustments. Automatic configurations also align with the broader adoption of precision-farming technologies across Europe. In November 2025, LEMKEN GmbH & Co. KG introduced the Faya MF precision seed drill, featuring ISOBUS iQblue operation, individual row hoppers, and automatic section control, demonstrating the continued integration of automated functions into planting equipment. As European farms increasingly adopt precision-oriented planting practices, demand for automated systems is anticipated to support growth in the segment.
Semi-Automatic systems provide an intermediate option for farms seeking selected electronic functions without the full automation of higher-specification equipment. These systems can support features such as electronic monitoring and control while retaining greater reliance on operator intervention. Mechanical Systems remain relevant where equipment affordability, operational simplicity, and established servicing capabilities are important purchasing considerations. The availability of automatic, semi-automatic, and mechanical configurations allows manufacturers to address differences in farm size, investment capacity, technical requirements, and local service availability across European markets. This broad range of equipment configurations is anticipated to maintain demand across the design segment, even as adoption of automated planting technologies increases.
Complete Report Scope:
- By Design
- Mechanical
- Automatic
- Semi-Automatic
- By Operation
- Mounted equipment
- Trailed equipment
- Self-Propelled equipment
- Walk-Behind equipment
- Ride-On equipment
- By Crop Type
- Cereals and Grains
- Rice
- Wheat
- Maize
- Other Cereals and Grains
- Oilseeds and Pulses
- Soybean
- Groundnut
- Pulses
- Fruits and Vegetables
- Vegetables
- Fruit Crops
- Cotton
- Sugarcane
- Other Crop Types
- Cereals and Grains
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Netherlands
- Poland
- Russia
- Rest of Europe
List of Companies Covered in this Report:
- Deere & Company
- AGCO Corporation
- KUHN S.A. (Bucher Industries AG)
- Kverneland AS (Kubota Corporation)
- YANMAR HOLDINGS CO., LTD.
- Kubota Corporation
- Mahindra & Mahindra Limited
- CNH Industrial N.V.
- ISEKI & CO., LTD.
- DAEDONG CORPORATION
- YTO Group Corporation (China National Machinery Industry Corporation)
- Zoomlion Heavy Industry Science & Technology Co., Ltd.
- MASCHIO GASPARDO S.p.A.
- AMAZONEN-WERKE H. DREYER SE & Co. KG
- HORSCH Maschinen GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 European Union CAP strategic plans and national machinery grants
- 4.2.2 European farm-labor shortages and rising agricultural wages
- 4.2.3 Climate volatility and compressed European planting windows
- 4.2.4 Precision seeding for EU input-reduction and sustainability targets
- 4.2.5 Replacement demand from aging European machinery fleets
- 4.2.6 Interoperable planting systems for fragmented European farms
- 4.3 Market Restraints
- 4.3.1 High equipment prices and elevated European farm financing costs
- 4.3.2 Small and fragmented holdings limiting annual machine utilization
- 4.3.3 Limited technical service capacity for connected planting equipment
- 4.3.4 Cross-brand data and implement compatibility gaps across European fleets
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Supplier Bargaining Power
- 4.6.2 Buyer Bargaining Power
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Design
- 5.1.1 Mechanical
- 5.1.2 Automatic
- 5.1.3 Semi-Automatic
- 5.2 By Operation
- 5.2.1 Mounted equipment
- 5.2.2 Trailed equipment
- 5.2.3 Self-Propelled equipment
- 5.2.4 Walk-Behind equipment
- 5.2.5 Ride-On equipment
- 5.3 By Crop Type
- 5.3.1 Cereals and Grains
- 5.3.1.1 Rice
- 5.3.1.2 Wheat
- 5.3.1.3 Maize
- 5.3.1.4 Other Cereals and Grains
- 5.3.2 Oilseeds and Pulses
- 5.3.2.1 Soybean
- 5.3.2.2 Groundnut
- 5.3.2.3 Pulses
- 5.3.3 Fruits and Vegetables
- 5.3.3.1 Vegetables
- 5.3.3.2 Fruit Crops
- 5.3.4 Cotton
- 5.3.5 Sugarcane
- 5.3.6 Other Crop Types
- 5.3.1 Cereals and Grains
- 5.4 By Geography
- 5.4.1 Germany
- 5.4.2 United Kingdom
- 5.4.3 France
- 5.4.4 Italy
- 5.4.5 Spain
- 5.4.6 Netherlands
- 5.4.7 Poland
- 5.4.8 Russia
- 5.4.9 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Deere & Company
- 6.4.2 AGCO Corporation
- 6.4.3 KUHN S.A. (Bucher Industries AG)
- 6.4.4 Kverneland AS (Kubota Corporation)
- 6.4.5 YANMAR HOLDINGS CO., LTD.
- 6.4.6 Kubota Corporation
- 6.4.7 Mahindra & Mahindra Limited
- 6.4.8 CNH Industrial N.V.
- 6.4.9 ISEKI & CO., LTD.
- 6.4.10 DAEDONG CORPORATION
- 6.4.11 YTO Group Corporation (China National Machinery Industry Corporation)
- 6.4.12 Zoomlion Heavy Industry Science & Technology Co., Ltd.
- 6.4.13 MASCHIO GASPARDO S.p.A.
- 6.4.14 AMAZONEN-WERKE H. DREYER SE & Co. KG
- 6.4.15 HORSCH Maschinen GmbH


