

|
시장보고서
상품코드
2154244
유럽의 중고 건설기계 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Used Construction Machinery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
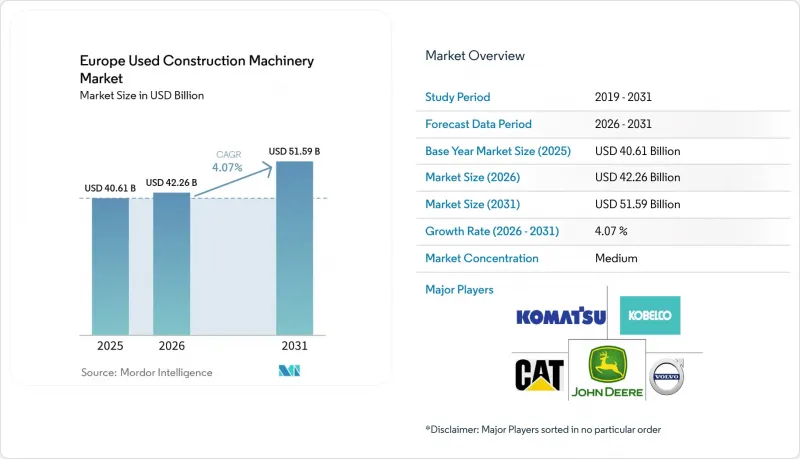
에 따르면 유럽의 중고 건설기계 시장 규모는 2025년에 406억 1,000만 달러로 평가되며, 2026년에는 422억 6,000만 달러로 추정되고 있으며, 2031년까지 515억 9,000만 달러에 달할 것으로 예측됩니다.
2026-2031년에 연평균 성장률(CAGR) 4.07%로 성장할 것으로 전망됩니다.
유럽 중고 건설기계 시장의 동향 및 인사이트
가속화되는 EU의 인프라 부양책
EU의 ‘NextGenerationEU’ 및 개정된 TEN-T 지침에 따라 철도 터널, 항만, 고속도로에 막대한 자금이 배정되면서, 중고 시장에서 조달되는 가동 시간이 긴 굴착기 및 아티큘레이트 하러에 대한 수요가 증가하고 있습니다. 폴란드의 ‘회복·탄력성 기금(RRF)’ 예산에 힘입어 비아 카르파티아 고속도로 계약이 신속하게 진행되면서 중고 불도저 수요가 급증하고 있습니다. 스페인에서는 철도 현대화 패키지에 따라 도시 지역 역 개보수를 위한 소형 굴착기 도입이 확대되고 있습니다. 공공사업 도급업체들은 조달 제한에 대응하기 위해 스테이지 IV 규정을 준수하는 기계를 선호하고 있습니다. 이러한 선택은 기계의 잔존 가치를 보호할 뿐만 아니라, 플릿의 갱신 주기를 단축하는 결과로 이어집니다. 안정적인 프로젝트 파이프라인이 예상되는 가운데, 재판매 가격은 안정세를 유지하고 있으며, 소유주들이 자산을 조기에 매각할 동기를 부여하고 있습니다.
스테이지 V 준수 차량으로의 전환
스테이지 V 오프로드 규제의 시행으로 인해 렌탈 업체와 대형 건설업체들은 벌칙을 피하기 위해 Tier 3 및 티어 4 잠정 규격 장비를 단계적으로 폐기할 수밖에 없게 되었습니다. 이러한 규제는 미세먼지 배출량을 특정 기준치 이하로 제한하고, 일정 출력을 초과하는 엔진의 NOx 배출량을 감축할 것을 요구하고 있습니다. 볼보 CE는 납품 대수의 대부분이 스테이지 V 대응 기종이었다고 밝혔습니다. 그러나 스테이지 V 이전 모델의 상당수는 여전히 가동 중이며, 향후 몇 년 내에 재판매될 전망입니다. 경매에서는 스테이지 V 대응 기종이 상당한 프리미엄 가격에 거래되는 반면, 규제를 준수하지 않는 디젤 기종은 규제가 완화된 수출 시장으로 유입되고 있으며, 시장이 명확하게 양극화되고 있음이 드러나고 있습니다. 또한 엔진 가동 시간이나 배기가스 시스템의 이력 기록을 요구하는 구매자들의 수요에 힘입어 텔레매틱스 도입이 가속화되고 있습니다.
고금리 환경 하에서의 건설 및 설비 투자 변동
유럽중앙은행(ECB)이 대폭적인 통화 긴축을 단행한 후 예금 금리를 동결함에 따라 주요 시장에서 주택담보대출 금리가 사상 최고 수준을 넘어섰습니다. 유로스타트는 주로 주택 부문의 침체를 원인으로 지목하며, 유로존의 건설 생산액이 감소했다고 지적했습니다. 재고 증가에 직면한 딜러들은 중가대 차량의 잔존 가치에 하락 압력을 가하고 있습니다. 이탈리아와 그리스 등 일부 국가들은 국채 스프레드 확대, 인프라 입찰 연기, 그리고 갱신 주기의 장기화로 어려움을 겪고 있습니다. 렌탈 업체들은 보유 차량을 물류 및 창고 프로젝트용으로 전환했으나, 장비 구성의 변화는 토목 공사의 침체를 부분적으로만 완화할 수 있었습니다. 전기자동차(EV) 시장에서는 렌탈 업체들이 지속가능성 목표와 변화하는 소비자 선호도에 맞춰 보유 차량에 전기자동차를 포함시키는 데 점점 더 주력하고 있습니다.
부문별 분석
2025년, 유럽 중고 건설기계 시장에서 굴착기 부문은 35.92%의 점유율을 차지했습니다. 이는 토목 공사, 철거 공사, 공공 사업 등 폭넓은 분야에서 쌓아온 도입 실적과 다용도성을 반영한 결과입니다. 차량 소유주들은 굴착기를 활용하여 가장 높은 재판매 유동성을 실현했습니다. 이를 통해 견실한 가격으로 정기적으로 장비를 교체할 수 있게 되었습니다. 굴착기에 이어 로더 부문이 큰 점유율을 차지했으며, 주로 채석장 및 자재 취급 업무에 활용되었습니다. 한편, 크레인과 그레이더는 시장 점유율이 한 자릿수 중반에 그쳤습니다.
덤프트럭은 가장 빠르게 성장하는 부문으로, 2031년까지의 연평균 성장률(CAGR)은 4.59%에 달합니다. 이는 건설업체들이 스칸디나비아의 피오르드 지형이나 알프스의 가파른 경사면을 주행할 수 있는 아티큘레이트 덤프트럭을 선호하기 때문입니다. 6륜 구동을 자랑하는 볼보의 A45G는 몇 차례의 임대 주기를 거친 후 중고 시장에 처음 등장했습니다. 대폭적인 할인이 적용되었음에도 불구하고 여전히 뛰어난 적재량 생산성을 발휘하고 있습니다. 아티큘레이트 부문의 성장에 따라 잔존 가치 곡선도 변화하고 있습니다. 이러한 변화에 발맞춰 독일과 벨기에 대한 경매 주최사들은 분기별 행사에서 운반차 전용 경매 코너를 마련하기 시작했습니다.
2025년에도 내연기관 파워트레인은 89.16%의 시장 점유율을 유지하고 있으며, 다교대제 채석장 작업에 투입되는 중장비에서 디젤이 뛰어난 에너지 밀도를 지닌다는 사실이 입증되고 있습니다. 그러나 하이브리드 및 배터리 구동 기종군은 연간 6.78%의 속도로 확대되고 있으며, 그 선두를 달리는 것은 하룻밤 충전으로 하루의 가동 주기를 충당할 수 있는 소형 굴착기입니다. 유럽에서 실시된 실증 시험에서 캐터필러사의 디젤-전기 하이브리드식 불도저 ‘D6 XE’는 연료비를 대폭 절감하는 효과를 입증했습니다. 그러나 초기 비용이 고가인 탓에, 그 도입은 주로 지속가능성을 중시하는 대규모 건설업체로 한정되어 있습니다.
전기식 기계의 도입은 특히 미니 굴착기와 스키드 스티어 로더 분야에서 급증하고 있습니다. 볼보의 ‘ECR25 Electric’은 경매에서 고가에 거래되고 있습니다. 그 주요 이유는 가동 시간이 짧은 기종의 경우, 도심 지역 건설업체가 배기가스 관련 과금을 피할 수 있기 때문입니다. 구매자는 일반적으로 배터리 팩 교체 가능성을 감안하여 충전 사이클 수가 많은 전기식 기계의 가격을 할인하지만, 가격 책정 과정은 점점 더 정교해지고 있습니다. 이는 주로 텔레매틱스 데이터 공개가 표준화되고 있는 데 기인하며, 현재는 경매에서 충전 상태나 사이클 이력이 일반적으로 공개되고 있습니다.
11톤을 초과하는 대형 기계는 독일과 덴마크를 연결하는 페마룬베르트 터널 등의 대규모 인프라 프로젝트 덕분에 2025년 거래의 46.23%를 차지했습니다. 한편, 6톤 미만의 소형 장비는 도시 재개발 및 개보수 수요를 배경으로 연평균 성장률(CAGR) 4.69%라는 가장 높은 성장률을 기록할 전망입니다.
렌탈 회사는 일반적으로 소형 장비군을 정기적인 주기로 갱신하고 있습니다. 이러한 관행으로 인해 가동 시간이 적은 타케우치 TB216이나 밥캣 E10e가 경매 시장에 대량으로 유입되고 있습니다. 한편, 중장비 부문에서는 리프헬(Leuphel)사의 광산용 굴착기 ‘R 980 SME’가 채석장에서 장기간 사용된 후 중고 시장에 등장하고 있습니다. 신품 정가보다 저렴한 가격에 거래되고 있음에도 불구하고 이 굴착기에 대한 수요는 계속해서 견고하며, 특히 버킷 용량이 6m³를 초과하는 기종을 찾는 폴란드와 포르투갈의 운영자들로부터의 수요가 두드러집니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 기기 유형별
- 추진 유형별
- 기기 사이즈별
- 출력별
- 용도별
- 기기 내용연수별
- 판매 채널별
- 국가별
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 스웨덴
- 기타 유럽 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Caterpillar Inc.
- Volvo Construction Equipment
- Liebherr-International Deutschland GmbH
- Komatsu Ltd.
- JCB Ltd.
- Hitachi Construction Machinery
- Deere & Company
- Kobelco Construction Machinery
- CNH Industrial(CASE)
- Wacker Neuson SE
- Kubota Corp.
- Doosan Infracore
- Hyundai Construction Equipment
- SANY Group
- Manitou Group
- Terex Corporation
- Yanmar CE
- Atlas GmbH
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the European used construction machinery market size was valued at USD 40.61 billion in 2025, is estimated at USD 42.26 billion in 2026, and is projected to reach USD 51.59 billion by 2031, growing at a CAGR of 4.07% from 2026 to 2031.
Europe Used Construction Machinery Market Trends and Insights
Accelerated EU Infrastructure Stimulus
The EU's NextGenerationEU and updated TEN-T guidelines allocate substantial funding to rail tunnels, ports, and highways, favoring high-hour excavators and articulated haulers sourced from the secondary market . Poland's Recovery & Resilience Facility budget has fast-tracked contracts for the Via Carpatia highway, leading to a surge in demand for pre-owned dozers. In Spain, a railway modernization package is driving the acquisition of compact excavators for upgrades at urban stations. Public contractors, navigating procurement limits, are gravitating towards Stage IV machines. This choice not only safeguards the machines' residual value but also encourages more frequent fleet turnover. With a steady project pipeline in sight, resale prices have stabilized, motivating owners to auction off their assets sooner.
Shift to Stage V-Compliant Fleets
The enforcement of Stage V off-road regulations compelled rental firms and major contractors to phase out Tier 3 and Tier 4 interim equipment to sidestep penalties. These regulations limit particulate emissions to below a specific threshold and reduce NOx emissions for engines exceeding a certain power output. Volvo CE revealed that the majority of its deliveries were Stage V machines . However, many pre-Stage V units still operate and are set for resale in the coming years. Stage V units command a significant premium at auctions, while non-compliant diesel units find their way to export markets with more lenient regulations, highlighting a distinct two-tier market. Furthermore, the push for telematics is on the rise, driven by buyers' demands for documented histories of engine hours and emission systems.
Construction-Capex Volatility Amid High Rates
The European Central Bank held its deposit rate steady after significant tightening, leading mortgage rates to surpass levels seen in major markets. Eurostat highlighted a decline in eurozone construction output, driven primarily by falls in the residential sector . Dealers, facing higher inventories, exert downward pressure on mid-tier residual values. Countries like Italy and Greece grapple with widening sovereign-debt spreads, postponed infrastructure tenders, and extended replacement cycles. While rental firms shifted their fleets toward logistics and warehouse projects, the change in equipment mix only partially mitigated the downturn in civil works. In the electric vehicle market, rental firms are increasingly focusing on integrating EVs into their fleets to align with sustainability goals and evolving consumer preferences.
Other drivers and restraints analyzed in the detailed report include:
- Digital Auction Platforms Deepen Liquidity
- Energy-Efficient Renovation Boom
- Ultra-Low-Emission Zones Depress Older-Diesel Values
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The excavator category captured 35.92% of the European used construction equipment market in 2025, reflecting a broad installed base and versatility across civil works, demolition, and utilities. Fleet owners capitalized on excavators, achieving the highest resale liquidity. This allowed them to rotate units periodically at robust prices. Following excavators and loaders, the category of loaders captured a significant share, primarily serving quarries and material-handling tasks. Meanwhile, cranes and graders occupied mid-single-digit market positions.
Dump trucks are the fastest-growing segment, with a 4.59% CAGR to 2031, as contractors favor articulated haulers that navigate Scandinavian fjord terrain and Alpine gradients. Volvo's A45G, boasting a six-wheel drive, makes its debut on the secondary market after several rental cycles. Even with a significant discount, it still delivers notable payload productivity. As the articulated segment grows, it's reshaping residual-value curves. This change has prompted auctioneers in Germany and Belgium to launch dedicated hauler rings in their quarterly events.
Internal-combustion powertrains retained 89.16% market share in 2025, underscoring diesel's superior energy density for heavy machines deployed on multi-shift quarry operations. However, the hybrid-and-battery cohort is expanding at 6.78% per year, led by compact excavators where overnight charging suffices for daily duty cycles. In European trials, Caterpillar's diesel-electric D6 XE dozer showcased significant fuel savings. However, its steeper upfront price tag has confined its adoption primarily to larger contractors with a sustainability focus.
Electric adoption is surging, particularly in mini-excavators and skid-steers. Volvo's ECR25 Electric is fetching premium prices at auctions, largely because its low-hour units allow urban contractors to sidestep emissions-related fees. While buyers typically discount electrics with higher charge cycles to account for potential battery-pack replacements, the pricing process is becoming more refined. This is largely due to the increasing standardization of telematics data disclosures, which now commonly include state-of-charge and cycle history at auctions.
Heavy units above 11 tonnes accounted for 46.23% of 2025 transactions, owing to large-scale infrastructure projects such as the Fehmarnbelt Tunnel between Germany and Denmark, while sub-6-tonne compacts will post the fastest 4.69% CAGR on urban-infill and renovation demand.
Rental companies typically refresh their compact fleets on regular cycles. This routine results in a significant influx of low-hour Takeuchi TB216 and Bobcat E10e units entering auction channels. Meanwhile, in the heavy machinery segment, Liebherr's R 980 SME mining excavator, after extended use at quarry sites, makes its debut in the secondary market. Despite trading at a discount to its new list price, the excavator continues to see robust demand, particularly from Polish and Portuguese operators seeking bucket capacities exceeding 6 m3.
Complete Report Scope:
- By Equipment Type
- Excavator
- Loader
- Mobile Cranes
- Motor Graders
- Bulldozers
- Road Rollers
- Dump Trucks
- Others
- By Propulsion Type
- Internal Combustion
- Hybrid / Battery-Electric
- Hydrogen Fuel-Cell
- By Equipment Size
- Heavy (Above 11 t)
- Medium (6-11 t)
- Compact / Mini (Below 6 t)
- By Power Output
- Up to 250 HP
- 250 - 500 HP
- Above 500 HP
- By Application
- Infrastructure
- Residential and Commercial Construction
- Mining and Quarrying
- Oil and Gas / Pipelines
- Industrial and Manufacturing
- Others
- By Equipment Age
- Below 5 Years
- 5 - 10 Years
- 10 - 15 Years
- Above 15 Years
- By Sales Channel
- Dealer / Broker
- Auction
- Online Platforms
- By Country
- Germany
- United Kingdom
- France
- Italy
- Spain
- Sweden
- Rest of Europe
List of Companies Covered in this Report:
- Caterpillar Inc.
- Volvo Construction Equipment
- Liebherr-International Deutschland GmbH
- Komatsu Ltd.
- JCB Ltd.
- Hitachi Construction Machinery
- Deere & Company
- Kobelco Construction Machinery
- CNH Industrial (CASE)
- Wacker Neuson SE
- Kubota Corp.
- Doosan Infracore
- Hyundai Construction Equipment
- SANY Group
- Manitou Group
- Terex Corporation
- Yanmar CE
- Atlas GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated EU Infrastructure Stimulus (NextGen, TEN-T)
- 4.2.2 Shift To Stage V-Compliant Fleets Drives Renewal
- 4.2.3 Digital Auction Platforms Deepen Liquidity
- 4.2.4 Energy-Efficient Renovation Boom (EU Green Deal)
- 4.2.5 MEA Buyers Exploiting Weak Euro Via Online Bids
- 4.2.6 OEM Refurbishment + Telematics Subscriptions
- 4.3 Market Restraints
- 4.3.1 Construction-Capex Volatility Amid High Rates
- 4.3.2 Ultra-Low-Emission Zones Hurt Older Diesel Values
- 4.3.3 Export Freight-Rate Spikes Squeeze Margins
- 4.3.4 Influx of Low-Cost Rebuilt Chinese Equipment
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value (USD), Volume (Units))
- 5.1 By Equipment Type
- 5.1.1 Excavator
- 5.1.2 Loader
- 5.1.3 Mobile Cranes
- 5.1.4 Motor Graders
- 5.1.5 Bulldozers
- 5.1.6 Road Rollers
- 5.1.7 Dump Trucks
- 5.1.8 Others
- 5.2 By Propulsion Type
- 5.2.1 Internal Combustion
- 5.2.2 Hybrid / Battery-Electric
- 5.2.3 Hydrogen Fuel-Cell
- 5.3 By Equipment Size
- 5.3.1 Heavy (Above 11 t)
- 5.3.2 Medium (6-11 t)
- 5.3.3 Compact / Mini (Below 6 t)
- 5.4 By Power Output
- 5.4.1 Up to 250 HP
- 5.4.2 250 - 500 HP
- 5.4.3 Above 500 HP
- 5.5 By Application
- 5.5.1 Infrastructure
- 5.5.2 Residential and Commercial Construction
- 5.5.3 Mining and Quarrying
- 5.5.4 Oil and Gas / Pipelines
- 5.5.5 Industrial and Manufacturing
- 5.5.6 Others
- 5.6 By Equipment Age
- 5.6.1 Below 5 Years
- 5.6.2 5 - 10 Years
- 5.6.3 10 - 15 Years
- 5.6.4 Above 15 Years
- 5.7 By Sales Channel
- 5.7.1 Dealer / Broker
- 5.7.2 Auction
- 5.7.3 Online Platforms
- 5.8 By Country
- 5.8.1 Germany
- 5.8.2 United Kingdom
- 5.8.3 France
- 5.8.4 Italy
- 5.8.5 Spain
- 5.8.6 Sweden
- 5.8.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)}
- 6.4.1 Caterpillar Inc.
- 6.4.2 Volvo Construction Equipment
- 6.4.3 Liebherr-International Deutschland GmbH
- 6.4.4 Komatsu Ltd.
- 6.4.5 JCB Ltd.
- 6.4.6 Hitachi Construction Machinery
- 6.4.7 Deere & Company
- 6.4.8 Kobelco Construction Machinery
- 6.4.9 CNH Industrial (CASE)
- 6.4.10 Wacker Neuson SE
- 6.4.11 Kubota Corp.
- 6.4.12 Doosan Infracore
- 6.4.13 Hyundai Construction Equipment
- 6.4.14 SANY Group
- 6.4.15 Manitou Group
- 6.4.16 Terex Corporation
- 6.4.17 Yanmar CE
- 6.4.18 Atlas GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


