

|
시장보고서
상품코드
2154285
유럽의 타이어 제조 장비 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Tire Manufacturing Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
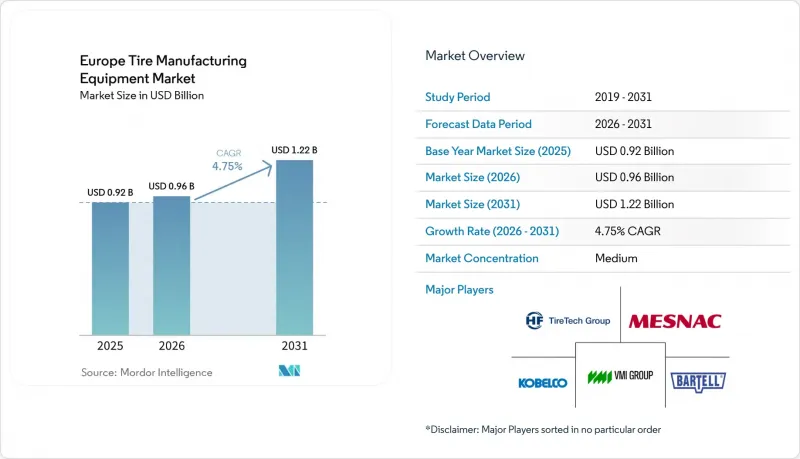
에 따르면 유럽의 타이어 제조 설비 시장 규모는 2025년 9억 2,000만 달러에서 2026년에는 9억 6,000만 달러로 확대하며, 2031년까지 12억 2,000만 달러에 달할 것으로 예상되고 있으며, 2026-2031년에 CAGR 4.75%로 성장할 것으로 전망되고 있습니다.
유럽 타이어 제조 설비 시장의 동향 및 인사이트
전기자동차(EV)를 주동력으로 하는 고실리카 레이디얼 컴파운드의 수요 급증으로 인해 첨단 혼련 및 압출 라인이 필요해지고 있습니다.
전기자동차용 타이어는 차축당 무게가 무겁고 실리카가 배합되어 있으며, 스코칭을 방지하기 위해 믹서에는 더 높은 전단력이 요구됩니다. 코벨코의 ‘5THR’ 로터는 생산성을 43% 향상시켜, 각 OEM 업체가 추가 믹서를 도입하지 않고도 전기자동차 납기 일정을 준수할 수 있도록 합니다. 미쉐린의 매그놀리아 공장에서는 AI 제어를 통한 스크류 속도 조절로 실리카의 응집을 관리하여 효율적인 압출 속도를 실현하고 있습니다. 브리지스톤의 부르고스 공장에서는 림 직경이 큰 EV용 타이어의 생산 능력을 확대함에 따라 더 넓은 압출 헤드의 사용이 필요하게 되었습니다. 에보닉(Evonik)의 새로운 침전 실리카 등급은 분산 허용 오차가 더욱 엄격해졌으며, 이에 따라 로터의 내마모성 코팅이 표준적인 방식으로 자리 잡았습니다. 각 제조사가 결함률 개선을 목표로 하는 가운데, 디지털 트윈 및 예측 유지보수 알고리즘의 도입으로 가동률이 대폭 향상되었습니다.
유럽 전역의 타이어 제조사들의 생산 능력 확대가 성형기에 대한 새로운 설비 투자를 견인
스페인에 막대한 투자를 진행 중인 브리지스톤은 생산 능력 증강을 계획하고 있습니다. 이 확장을 위해서는 모듈식 드럼과 서보식 플라이 피더의 도입이 필요하며, 이를 통해 SKU 전환이 신속해질 것입니다. 한편, 아폴로와 노키안은 헝가리와 루마니아에서 생산을 확대하고 있으며, 2028년까지 새로운 빌딩 머신에 대한 수요가 급증할 것으로 예상됩니다. HF TireTech사의 ‘HF ONE’ 기술은 전환 효율을 향상시키고 폭넓은 SKU에 대응합니다. MESNAC사의 NPS 원스테이지 빌더는 사이클 타임이 짧아 소량 생산 요구에 최적입니다. 'The European Rubber Journal'에 따르면 2025년에는 막대한 설비 투자가 발표되었으며, 그 예산의 대부분이 빌딩 분야 설비에 배정되었습니다.
천연고무 및 석유화학제품의 가격 변동이 설비 구매를 지연시키고 있습니다.
2024년, 고무 가격은 10년 만에 최고치를 기록했으며, 현물 시장에서는 큰 폭의 변동이 나타났습니다. 이러한 가격 변동으로 인해 타이어 제조사의 이익률이 압박을 받고 있으며, 고가형 믹서의 수주가 정체되고 있습니다. 한편, 원유 가격 동향과 밀접하게 연동되는 합성 원료는 투입 비용에 추가적인 불확실성을 초래했습니다. 그 결과, 센추리사는 스페인에서의 그린필드 프로젝트를 보류하고 전제 조건을 재평가하고 있습니다. 또한 많은 중견 기업은 현재 새로운 생산 라인에 대한 투자를 결정하기 전에 가격이 일정 기간 중정되기를 요구하고 있습니다. 원자재비가 타이어 원가의 대부분을 차지한다는 점을 감안할 때, 원자재 리스크의 증가는 자본 예산에 직접적인 영향을 미칩니다.
부문별 분석
가황·검사 라인은 공장의 프레스 기계 전동화 및 미세먼지 배출 규제 강화에 따라 연평균 성장률(CAGR) 9.33%를 기록하며, 다른 모든 카테고리를 상회하는 성장이 예상됩니다. 유럽 타이어 제조 설비 시장에서 건설용 기계 시장 규모는 여전히 크며, 2025년에는 42.35%의 점유율을 차지할 것으로 예상되지만, 각 OEM 업체들이 에너지 절약형 가황기에 예산을 전환함에 따라 그 점유율은 하락하고 있습니다. 기존 프레임에 장착하는 형태의 전기 가열식 개조 키트는 토목 공사가 필요 없이 신속한 교체가 가능합니다. AI 이미지 분석을 활용한 검사 시스템은 새로운 프레스 기계에 번들로 제공되며, HF나 VMI와 같은 공급업체에게는 교차 판매의 기회가 되고 있습니다.
상류 공정의 믹서와 캘린더는 특히 실리카 함량이 높은 EV용 배합에서 여전히 중요합니다. 코벨코의 ‘5THR’과 코메리오의 ‘ZEUS’ 캘린더는 눈에 띄는 성장세가 둔화되고 있는 상황에서도 생산성의 점진적인 향상과 설치 면적의 축소가 수주로 이어지고 있음을 보여주고 있습니다. 스트립 와인더와 비드 와인더는 브리지스톤과 노키안의 생산 확대에 힘입어 수요가 증가하고 있지만, 전반적인 성장률은 가황 라인의 성장률보다 낮습니다. 이는 가황 라인이 ‘유로 7’ 규제와 탄소 중립 목표 모두에 대응하고 있기 때문입니다.
레이디얼용 기계는 2025년에 매출의 89.04%를 차지할 것으로 예상되며, 2031년까지 연평균 성장률(CAGR) 5.45%의 성장 궤도를 유지할 전망입니다. 유럽 타이어 제조 설비 시장에서 바이애스용 공구의 점유율은 여전히 극히 미미하며, 이륜차 및 틈새 오프로드 부문에 공급되고 있지만, 이러한 부문에서는 현재 많은 타이어를 아시아에서 조달하고 있습니다. 레이디얼 타이어 제조업체는 18-24인치 승용 전기자동차용 타이어 크기를 지원하기 위해 더 넓은 벨트를 처리해야 하며, 이로 인해 서보식 장력 제어 및 실시간 벨트 추적 기능으로의 업그레이드가 촉진되고 있습니다.
바이애스 프레스는 저렴하고 단순하지만, 수요가 너무 낮아 유럽의 많은 OEM(Original Equipment Manufacturer)를 유치하기에는 미치지 못하고 있습니다. 여전히 바이애스 생산 능력이 필요한 공장에서는 독립된 생산 라인을 구매하는 대신, 레이디얼용 드럼으로 개조하고 있습니다. 그 결과, 공급업체들은 스크랩을 두 자릿수 비율로 줄일 수 있는 AI 기반 이물질 감지 등, 레이디얼 타이어를 위한 기술 혁신에 연구개발을 집중하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류·공급망 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 기기 유형별
- 타이어 설계별
- 차종별
- 림 사이즈별
- 최종사용자별
- 국가별
- 독일
- 영국
- 스페인
- 이탈리아
- 프랑스
- 네덜란드
- 기타 유럽 국가
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- HF TireTech Group
- VMI Group
- Kobelco Stewart Bolling
- MESNAC Co., Ltd.
- Bartell Machinery Systems
- Comerio Ercole S.p.A.
- KONSTRUKTA-TireTech
- Colmec S.p.A.
- Herbert Maschinenbau
- Pelmar Engineering
- Marangoni Meccanica
- Mitsubishi Heavy Industries Machinery Systems
- Siempelkamp Maschinenbau
- Uzer Makina
- Hebert Maschinen
- Yiyang Rubber and Plastics Machinery
- Tianjin Saixiang Technology
- Larsen and Toubro Rubber Machinery
제7장 시장 기회와 향후 전망
KSAAccording to Mordor Intelligence, the European tire manufacturing equipment market size is expected to increase from USD 0.92 billion in 2025 to USD 0.96 billion in 2026 and reach USD 1.22 billion by 2031, growing at a 4.75% CAGR over 2026-2031.
Europe Tire Manufacturing Equipment Market Trends and Insights
EV-Led Surge in High-Silica Radial Compounds Needs Advanced Mixing and Extrusion Lines
Mixers now demand higher shear to prevent scorching, as electric-vehicle tires are heavier per axle and incorporate silica. Kobelco's 5THR rotor raises productivity by 43%, enabling OEMs to meet EV delivery windows without extra mixers . At Michelin's Magnolia plant, an AI-controlled screw speed manages silica agglomeration, achieving an efficient extrusion rate. Bridgestone's Burgos facility increased its capacity for high-rim EV sizes, necessitating the use of wider extrusion heads. Evonik's new precipitated-silica grades, which have tighter dispersion tolerances, have made rotor hardfacing a standard practice. As manufacturers aim for improved defect rates, the implementation of digital twins and predictive-maintenance algorithms has significantly enhanced uptime.
Tire-Maker Capacity Expansions Across Europe Drive Fresh Capex for Building Area Machines
Bridgestone, with a significant investment in Spain, is set to enhance its production capacity. This expansion necessitates the use of modular drums and servo ply feeders, enabling swift SKU transitions. Meanwhile, Apollo and Nokian are ramping up production in Hungary and Romania, leading to a surge in demand for new building machines by 2028. HF TireTech's HF ONE technology improves changeover efficiency and accommodates a wide range of SKUs. MESNAC's NPS one-stage builder offers a rapid cycle, perfectly suited for small-batch needs. According to The European Rubber Journal, substantial capital expenditures have been announced for 2025, with a significant portion of the budget allocated to building-area equipment.
Volatile Natural-Rubber and Petrochemical Prices Delay Equipment Purchases
In 2024, rubber prices reached their highest levels in over a decade, with significant spot-market fluctuations. This volatility has tightened margins for tire manufacturers and halted orders for high-value mixers. Meanwhile, synthetic feedstocks, closely tracking crude oil movements, introduced additional uncertainty in input costs. As a result, Sentury has put its Spanish greenfield project on hold, re-evaluating its assumptions. Furthermore, many mid-tier companies are now insisting on a period of stable pricing before they commit to new production lines. Given that raw materials account for a substantial portion of tire costs, any rise in feedstock risk directly impacts capital budgets.
Other drivers and restraints analyzed in the detailed report include:
- Smart-Factory and Industry 4.0 Retrofits for Productivity and Traceability
- Euro 7 Tire-Particle Limits Accelerate Uptake of Precision Curing and Inspection Machines
- High Capex and Long Payback Horizons Deter Smaller Manufacturers
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Curing and Inspection lines are projected to outpace all other categories at a 9.33% CAGR as plants electrify presses and tighten particle-emission control. The European tire manufacturing equipment market size for Building-area machines remains large, with 42.35% share in 2025, yet its share declines as OEMs divert budgets to energy-saving vulcanizers. Electric-heating retrofits that slot into existing frames allow fast swaps without civil works. Inspection systems using AI image analytics are bundled with new presses, giving suppliers like HF and VMI a cross-selling opportunity.
Upstream mixers and calenders still matter, especially with high-silica EV recipes. Kobelco's 5THR and Comerio's ZEUS calendars demonstrate that incremental productivity and footprint savings win orders even when headline growth lags. Strip winders and bead winders get uplift from Bridgestone and Nokian expansions, but overall growth trails that of curing lines because the latter tackle both Euro 7 compliance and carbon-neutral targets.
Radial machinery captured 89.04% revenue in 2025 and will maintain a 5.45% CAGR growth trajectory through 2031. The European tire manufacturing equipment market share for bias tooling remains marginal, serving two-wheeler and niche off-road segments that now source many tires from Asia. Radial builders must handle wider belts for 18-to-24-inch passenger EV sizes, driving upgrades to servo tensioning and real-time belt tracking.
Bias presses are inexpensive and simple, yet demand is too low to entice most European OEMs. Plants that still need bias capability retrofit radial drums rather than buy standalone lines. Consequently, suppliers concentrate R&D on radial innovations such as AI-assisted foreign-object detection that can cut scrap by double digits.
Complete Report Scope:
- By Equipment Type
- Upstream (Mixer and Component Preparation)
- Mixing Machines / Rubber Mixers
- Calendaring Machines
- Extrusion Machines
- Cutting Machines
- Others (Cooling Units, etc.)
- Building Area
- Bead Winding Machines
- Tire Building Machines
- Others (Strip Winding Machines, etc.)
- Curing and Inspection (Testing Area)
- Curing Press Machines
- Tire Painting Machines
- Others (Inspection Machines, etc.)
- Upstream (Mixer and Component Preparation)
- By Tire Design
- Bias
- Radial
- By Vehicle Type
- Two-Wheelers
- Three-Wheelers
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Off-Road Vehicles
- By Rim Size
- Up to 12 inches
- 12 to 18 inches
- Above 18 inches
- By End-User
- Original Equipment Manufacturers (OEMs)
- Replacement / Aftermarket
- By Country
- Germany
- United Kingdom
- Spain
- Italy
- France
- Netherlands
- Rest of Europe
List of Companies Covered in this Report:
- HF TireTech Group
- VMI Group
- Kobelco Stewart Bolling
- MESNAC Co., Ltd.
- Bartell Machinery Systems
- Comerio Ercole S.p.A.
- KONSTRUKTA-TireTech
- Colmec S.p.A.
- Herbert Maschinenbau
- Pelmar Engineering
- Marangoni Meccanica
- Mitsubishi Heavy Industries Machinery Systems
- Siempelkamp Maschinenbau
- Uzer Makina
- Hebert Maschinen
- Yiyang Rubber and Plastics Machinery
- Tianjin Saixiang Technology
- Larsen and Toubro Rubber Machinery
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV-Led Surge in High-Silica Radial Compounds Needs Advanced Mixing and Extrusion Lines
- 4.2.2 Tire-Maker Capacity Expansions Across Europe Drive Fresh Capex for Building Area Machines
- 4.2.3 Smart-Factory and Industry 4.0 Retrofits for Productivity and Traceability
- 4.2.4 Euro 7 Tire-Particle Limits Accelerate Uptake of Precision Curing and Inspection Machines
- 4.2.5 Energy-Cost Spikes Push Migration to Energy-Efficient All-Electric Presses
- 4.2.6 EU Circular-Economy Rules Spur Investment in Mixing Lines That Handle Recycled/Bio Fillers
- 4.3 Market Restraints
- 4.3.1 Volatile Natural-Rubber and Petrochemical Prices Delay Equipment Purchases
- 4.3.2 High Capex and Long Payback Horizons Deter Smaller Manufacturers
- 4.3.3 Skilled-Maintenance Shortage Limits Adoption of Integrated, Complex Machinery
- 4.3.4 Proposed PFAS Ban Clouds Equipment-Seal Specifications and Upgrade Timing
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitution
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Equipment Type
- 5.1.1 Upstream (Mixer and Component Preparation)
- 5.1.1.1 Mixing Machines / Rubber Mixers
- 5.1.1.2 Calendaring Machines
- 5.1.1.3 Extrusion Machines
- 5.1.1.4 Cutting Machines
- 5.1.1.5 Others (Cooling Units, etc.)
- 5.1.2 Building Area
- 5.1.2.1 Bead Winding Machines
- 5.1.2.2 Tire Building Machines
- 5.1.2.3 Others (Strip Winding Machines, etc.)
- 5.1.3 Curing and Inspection (Testing Area)
- 5.1.3.1 Curing Press Machines
- 5.1.3.2 Tire Painting Machines
- 5.1.3.3 Others (Inspection Machines, etc.)
- 5.1.1 Upstream (Mixer and Component Preparation)
- 5.2 By Tire Design
- 5.2.1 Bias
- 5.2.2 Radial
- 5.3 By Vehicle Type
- 5.3.1 Two-Wheelers
- 5.3.2 Three-Wheelers
- 5.3.3 Passenger Cars
- 5.3.4 Light Commercial Vehicles
- 5.3.5 Medium and Heavy Commercial Vehicles
- 5.3.6 Off-Road Vehicles
- 5.4 By Rim Size
- 5.4.1 Up to 12 inches
- 5.4.2 12 to 18 inches
- 5.4.3 Above 18 inches
- 5.5 By End-User
- 5.5.1 Original Equipment Manufacturers (OEMs)
- 5.5.2 Replacement / Aftermarket
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 Spain
- 5.6.4 Italy
- 5.6.5 France
- 5.6.6 Netherlands
- 5.6.7 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 HF TireTech Group
- 6.4.2 VMI Group
- 6.4.3 Kobelco Stewart Bolling
- 6.4.4 MESNAC Co., Ltd.
- 6.4.5 Bartell Machinery Systems
- 6.4.6 Comerio Ercole S.p.A.
- 6.4.7 KONSTRUKTA-TireTech
- 6.4.8 Colmec S.p.A.
- 6.4.9 Herbert Maschinenbau
- 6.4.10 Pelmar Engineering
- 6.4.11 Marangoni Meccanica
- 6.4.12 Mitsubishi Heavy Industries Machinery Systems
- 6.4.13 Siempelkamp Maschinenbau
- 6.4.14 Uzer Makina
- 6.4.15 Hebert Maschinen
- 6.4.16 Yiyang Rubber and Plastics Machinery
- 6.4.17 Tianjin Saixiang Technology
- 6.4.18 Larsen and Toubro Rubber Machinery
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment


