

|
시장보고서
상품코드
2154375
공간 오디오 소프트웨어 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Spatial Audio Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
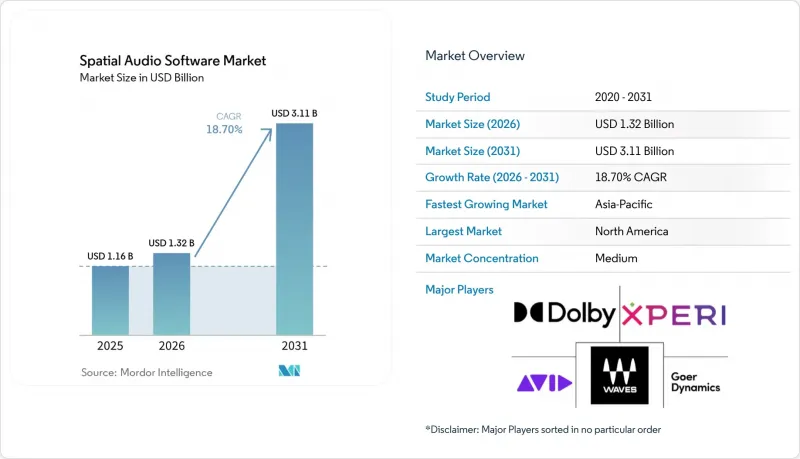
에 따르면 공간 오디오 소프트웨어 시장 규모는 2025년에 11억 6,000만 달러로 평가되며, 2026년 13억 2,000만 달러에서 2031년까지 31억 1,000만 달러로 확대하며, 2026-2031년 예측 기간의 CAGR 18.70%로 성장할 것으로 전망되고 있습니다.
전 세계 공간 오디오 소프트웨어 시장의 동향 및 인사이트
몰입형 게임 및 XR 컨텐츠의 확대
공간 오디오는 단순한 옵션 기능이 아니라, 많은 AAA급 게임 개발 워크플로우에서 표준 기술 기능으로 자리 잡았습니다. 언리얼 엔진 5(Unreal Engine 5)와 유니티(Unity)에는 공간 오디오 기능이 내장되어 있으며, 미들웨어 제공업체들은 음향 모델링 및 고급 저작 기능에 집중하고 있습니다. 이러한 변화로 인해 엔진 수준의 기능만으로는 세부적인 음향 요구 사항을 충족할 수 없는 경우, 전문 툴에 대한 수요가 증가하고 있습니다. 가상 환경에서 공간적 일관성을 유지하기 위해서는 헤드 트래킹을 지원하는 바이노럴 렌더링이 여전히 필수적입니다. 그래프 뉴럴 필드(GNF) 접근법에 대한 연구에서는 이러한 환경에서 HRTF의 개인화를 위한 노력이 계속되고 있습니다. 미들웨어 제공업체들은 자사 제품을 게임 엔진의 출시 주기에 맞추는 경향을 보이고 있으며, 이로 인해 공간 저작 툴은 개발 워크플로우와 밀접하게 연계된 상태를 유지하고 있습니다.
공간 오디오 제공을 의무화하는 스트리밍 플랫폼
플랫폼의 요구 사항에 따라 레이블, 스튜디오 및 독립 크리에이터에게 공간 오디오 배포는 제작상의 필수 요건이 되었습니다. Apple Music은 Dolby Atmos 제출 파일이 스테레오에서 업믹스된 것이 아니라, 본래의 멀티채널 세션에서 생성된 것이어야 한다고 요구합니다. Apple은 WWDC 2025에서 Apple Spatial Audio Format을 도입하고, Apple Immersive Video를 위해 APAC을 의무화했습니다. 이러한 요구 사항으로 인해 Apple 네이티브 출력을 위해서는 Dolby Atmos 워크플로우만으로는 불충분할 가능성이 있습니다. 그 결과, 스튜디오는 여러 툴체인을 유지해야만 하며, 반복적인 업그레이드 비용이 발생할 가능성이 있습니다. 2026년 6월, Peacock은 2026년 FIFA 월드컵 중계에 Dolby AC-4를 채택하여 몰입형 스트리밍을 스포츠 생중계로 확대했습니다.
분산된 오브젝트 기반 및 씬 기반 오디오 표준
돌비 애트모스, MPEG-H 3D 오디오, 애플 스페이셜 오디오 포맷, AURO-3D 및 DTS:X의 경우, 컨텐츠 제작 팀이 여러 배포 경로를 지원해야 합니다. 이로 인해 단일 공통 제작 포맷에 비해 인코딩 및 검증에 드는 비용이 증가합니다. SMPTE 2110-41은 방송 파이프라인에서 돌비 AC-4 및 MPEG-H 메타데이터를 지원하지만, 포맷별 기기 지원 현황은 일관되지 않습니다. 삼성과 LG가 최근 DTS:X에서 전환하기로 결정한 것은 기기 지원 현황이 급격히 변화할 수 있음을 보여줍니다. 스튜디오는 고객의 요구를 충족하기 위해 여러 디지털 오디오 워크스테이션, 플러그인 및 변환 시스템을 병행하여 유지해야 할 수도 있습니다. 그 결과, 수요가 확대되고 있음에도 불구하고 공간 오디오 소프트웨어 시장에는 추가적인 라이선스 비용과 엔지니어링 비용이 수반됩니다.
부문 분석
2025년 기준, 소프트웨어는 구성 요소 부문의 75.80%를 차지했습니다. 이러한 상황은 공간 오디오 제작에서 플러그인, 미들웨어, 렌더링 엔진이 중심적인 역할을 하고 있음을 반영합니다. 모든 워크플로는 관련 하드웨어나 전문적인 지원이 필요해지기 전에 먼저 소프트웨어 라이선스에서 시작됩니다. 따라서 소프트웨어 구성 요소 부문의 공간 오디오 소프트웨어 시장 규모는 제작 체인 내의 견고한 진입점에 의해 지원되고 있습니다. 서비스 분야는 2031년까지 연평균 성장률(CAGR) 19.14%로 확대될 것으로 예측됩니다. 소프트웨어 구매 외에도 통합, 보정, 워크플로우 설계의 중요성이 점점 더 커지고 있습니다.
서비스에 대한 수요는 멀티 포맷 배포 및 디지털 오디오 워크스테이션(DAW)과의 통합에서 비롯됩니다. 경험이 풍부한 제작 팀이라 하더라도 포맷 변환이나 시스템 구성에 있으며, 지원이 필요한 경우가 있습니다. 또한 스튜디오가 온프레미스 제작 환경과 클라우드 액세스를 연계할 경우, 서비스 업무의 가치는 더욱 높아집니다. 소니 AI와 Audiokinetic은 Wwise에 AI를 활용한 ‘Similar Sound Search’ 기능을 도입하여, 전문적인 오서링 환경에 워크플로우 기능을 제공했습니다. 이러한 방향성은 정기적인 서비스 수익이 라이선스 수익과 병행하여 창출될 수 있음을 보여줍니다. 따라서 공간 오디오 소프트웨어 업계는 지속적인 소프트웨어 판매에만 의존하는 것이 아니라, 소프트웨어와 전문 지식을 하나로 묶어 제공할 수 있게 됩니다.
2025년, 공간 오디오 렌더링 소프트웨어는 제품 유형별 매출의 35.40%를 차지했습니다. 이는 게임, 방송 및 기타 몰입형 워크플로우에서 제작 파이프라인의 핵심 처리 역할을 수행합니다. 바이노럴 및 HRTF 플러그인은 2031년까지 연평균 성장률(CAGR) 19.42%로 확대될 것으로 예측됩니다. 헤드폰을 통한 전송은 전용 스피커 시스템 없이도 소비자에게 컨텐츠를 전달할 수 있습니다. 이로 인해 일반적인 재생 기기에서 공간 오디오 출력을 구현하고자 하는 크리에이터들의 실질적인 진입 장벽이 낮아집니다. 제작자가 전용 하드웨어를 설치하지 않고도 몰입감 있는 사운드를 제공할 수 있다면, 공간 오디오 소프트웨어 시장은 그 혜택을 누리게 될 것입니다.
뉴럴 필드 HRTF에 대한 연구는 개인 맞춤형 재생을 지원함으로써 이러한 플러그인의 역할을 더욱 확대할 가능성이 있습니다. 바이노럴 툴은 원격 청취, 가상현실 및 소비자용 스트리밍 분야에서 특히 중요합니다. 앰비소닉스 제작용 플러그인은 계속해서 가상현실 컨텐츠 및 라이브 이벤트의 워크플로우에 활용되고 있습니다. 돌비 애트모스, MPEG-H, 그리고 Apple Spatial Audio Format의 배포에는 오브젝트 기반 믹싱 및 오서링 툴이 여전히 필수적입니다. 그 밖의 제품으로는 기존 범주에 속하지 않는 AI 지원 툴 및 변환 기능 등이 포함됩니다. 공급업체는 다양한 포맷을 지원하면서도 제작 팀이 사용하기 편리한 툴을 동시에 제공해야 합니다.
지역별 분석
2025년, 북미는 매출의 38.42%를 차지했습니다. 이 지역에는 주요 플랫폼 사업자, 게임 스튜디오, 공간 오디오 벤더들이 모여 있습니다. 북미 기술 기업이 제시하는 요구 사항은 전 세계 컨텐츠 제작자들에게 영향을 미칠 가능성이 있습니다. 애플이 APAC 지역을 대상으로 제시한 몰입형 비디오 요구 사항은 현재 주기에서 중요한 플랫폼 관련 결정이었습니다. ATSC 3.0에는 Dolby AC-4 및 MPEG-H와 같은 차세대 오디오 프레임워크가 포함되어 있습니다. 이로 인해 미국의 방송 시설에서 공간 오디오 소프트웨어 시장에 대한 규정 준수 관련 수요가 발생하고 있습니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 19.64%로 성장할 것으로 예측됩니다. 중국, 한국, 일본은 각각 서로 다른 수요 패턴을 통해 시장에 기여하고 있습니다. 2026년 3월, QQ Music은 주요 음악 플랫폼 중 최초로 최신 Dolby AC-4 기능 강화를 도입했습니다. 한국의 TTA 표준에서는 차세대 TV를 위해 MPEG-H Audio를 의무화하고 있습니다. 일본에서는 게임 하드웨어, 자동차 업계와의 제휴, 그리고 소비자 가전 제품을 통해 수요가 지원되고 있습니다. 플라운호퍼 IDMT의 ‘Audiofields’는 2026년 2월 메르세데스-벤츠 차량에서 양산이 시작되었습니다.
유럽은 프라운호퍼 협회가 MPEG-H 표준 개발에 기여하고 있으므로 공간 오디오 소프트웨어 시장에서 중요한 위치를 차지하고 있습니다. 독일과 폴란드의 전문 공급업체들도 이 지역의 생산 기반을 지원하고 있습니다. 유럽방송연합(EBU)의 ‘오디오 정의 모델(Audio Definition Model)’은 채널 기반, 오브젝트 기반, 씬 기반 오디오 워크플로우를 지원합니다. 돌비와 아우디는 2025년 7월, 일부 아우디 모델에 돌비 애트모스 통합을 완료했습니다. 남미, 중동 및 아프리카는 여전히 규모는 작지만 신흥 시장으로서 성장하고 있습니다. 브라질의 SBTVD TV 3.0 표준에는 MPEG-H 오디오가 포함되어 있으며, OTT에 대한 투자와 모바일 우선 컨텐츠가 향후 수요를 끌어올릴 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 거시경제 요인이 시장에 미치는 영향
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 컴포넌트별
- 제품 유형별
- 배포 모드별
- 용도별
- 최종사용자별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 유럽
- 독일
- 영국
- 프랑스
- 러시아
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 한국
- 인도
- 동남아시아
- 오세아니아
- 기타 아시아태평양 국가
- 중동
- 아랍에미리트
- 사우디아라비아
- 튀르키예
- 기타 중동 국가
- 아프리카
- 남아프리카공화국
- 나이지리아
- 기타 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Dolby Laboratories, Inc.
- Xperi Holding Corporation
- Goerdyna Group
- Waves Audio Ltd.
- Dear Reality GmbH
- Avid Technology, Inc.
- Fraunhofer-Gesellschaft zur Forderung der angewandten Forschung e. V.
- Blue Ripple Sound Limited
- Sound Particles, Lda.
- Audiokinetic Inc.
- Firelight Technologies Pty Ltd
- VisiSonics Corporation
- Spatial Inc.
- G'Audio Lab, Inc.
- Mach1, Inc.
- Envelop VR, Inc.
- APL-HUD GmbH
- atmoky GmbH
- Ceva, Inc.
- Brandenburg Labs GmbH
- New Audio Technology GmbH
- Wave Arts, Inc.
- SoundField Limited
- Zylia Sp. z o.o.
제7장 시장 기회와 향후 전망
KSA 26.10.23According to Mordor Intelligence, the spatial audio software market size was valued at USD 1.16 billion in 2025 and is estimated to expand from USD 1.32 billion in 2026 to USD 3.11 billion by 2031, at a CAGR of 18.70% during the forecast period 2026-2031.
Global Spatial Audio Software Market Trends and Insights
Immersive Gaming and XR Content Expansion
Spatial sound has become a standard technical capability in many AAA game development workflows, rather than an optional feature. Unreal Engine 5 and Unity include spatial audio capabilities, which shifts middleware providers toward acoustic modeling and advanced authoring functions. This change increases demand for specialized tools when engine-level functions cannot resolve detailed acoustic requirements. Head-tracked binaural rendering remains necessary to maintain spatial coherence in virtual environments. Research on graph neural field approaches shows continued work on HRTF personalization for these settings. Middleware providers continue to align their products with game-engine release cycles, which keeps spatial authoring tools closely tied to development workflows.
Streaming Platforms Mandating Spatial-Audio Deliverables
Platform requirements are making spatial delivery a production requirement for labels, studios, and independent creators. Apple Music requires Dolby Atmos submissions to come from genuine multichannel sessions rather than stereo upmixes. Apple introduced the Apple Spatial Audio Format and mandated APAC for Apple Immersive Video at WWDC 2025. These requirements can make a Dolby Atmos workflow insufficient for Apple-native output. Studios may therefore maintain more than 1 toolchain and incur repeated upgrade costs. In June 2026, Peacock used Dolby AC-4 for its FIFA World Cup 2026 coverage, extending immersive delivery into live sports.
Fragmented Object-Based and Scene-Based Audio Standards
Dolby Atmos, MPEG-H 3D Audio, Apple Spatial Audio Format, AURO-3D, and DTS:X require content teams to address multiple delivery paths. This raises the cost of encoding and validation compared with a single common production format. SMPTE 2110-41 supports Dolby AC-4 and MPEG-H metadata in broadcast pipelines, but device support is not consistent across formats. Recent television decisions by Samsung and LG to move away from DTS:X show that device support can change quickly. Studios may retain parallel digital audio workstations, plugins, and conversion systems to meet customer needs. The Spatial audio software market consequently carries extra licensing and engineering costs even as demand expands.
Other drivers and restraints analyzed in the detailed report include:
- AI-Assisted Real-Time Rendering and HRTF Personalization
- Cloud-Based Production and Remote Collaboration
- High Cost of Certified Immersive-Audio Rooms
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software held 75.80% of the component segment in 2025. This position reflects the central role of plugins, middleware, and rendering engines in spatial production. Every workflow begins with a software license before it requires associated hardware or professional support. The Spatial audio software market size for the software component therefore rests on a durable entry point in the production chain. Services are projected to expand at a 19.14% CAGR through 2031. Integration, calibration, and workflow design are becoming more important alongside software purchases.
The need for services comes from multiformat delivery and digital audio workstation integration. Even experienced production teams may need help with format conversion and system configuration. Service work also becomes more valuable when a studio connects on-premises production with cloud access. Sony AI and Audiokinetic introduced an AI-powered Similar Sound Search capability in Wwise, bringing a workflow function into a professional authoring environment. This direction shows how recurring services can sit beside license revenue. The spatial audio software industry can therefore support software and expertise together rather than relying solely on perpetual software sales.
Spatial audio rendering software held 35.40% of product-type revenue in 2025. It serves as the processing core for production pipelines in gaming, broadcast, and other immersive workflows. Binaural and HRTF plugins are projected to expand at a 19.42% CAGR through 2031. Headphone delivery can reach consumers without requiring dedicated speaker systems. This lowers the practical barrier for creators that want spatial output on common listening devices. The Spatial audio software market benefits when producers can deliver immersive sound without a specialized hardware installation.
Neural-field HRTF research may widen the role of these plugins by supporting individualized playback. Binaural tools are particularly relevant for remote listening, virtual reality, and consumer streaming. Ambisonics production plugins continue to serve virtual reality content and live-event workflows. Object-based mixing and authoring tools remain necessary for Dolby Atmos, MPEG-H, and Apple Spatial Audio Format delivery. Other products include AI-assisted tools and conversion functions that do not fit established categories. Product vendors must balance broad format coverage with tools that remain straightforward for production teams.
Complete Report Scope:
- By Component
- Software
- Services
- By Product Type
- Spatial Audio Rendering Software
- Binaural and HRTF Plugins
- Ambisonics Production Plugins
- Object-Based Mixing and Authoring Tools
- Other Product Types
- By Deployment Mode
- On-Premises
- Cloud-Based
- By Application
- Gaming
- Music Production and Streaming
- Film, Television, and Postproduction
- Virtual Reality and Augmented Reality
- Live Events and Broadcast
- Automotive
- Enterprise Collaboration and Training
- By End User
- Studios and Postproduction Houses
- Game Developers and Publishers
- Streaming and Media Platforms
- Enterprises and Educational Institutions
- Individual Professionals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Southeast Asia
- Oceania
- Rest of Asia-Pacific
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 38.42% of revenue in 2025. The region brings together major platform operators, game studios, and spatial-audio vendors. Requirements issued by North American technology companies can affect content producers worldwide. Apple's APAC requirement for Immersive Video was a significant platform decision in the current cycle. ATSC 3.0 includes next-generation audio frameworks such as Dolby AC-4 and MPEG-H. This creates a compliance-related need for the Spatial audio software market in U.S. broadcast facilities.
Asia-Pacific is projected to expand at a 19.64% CAGR through 2031. China, South Korea, and Japan each contribute through different demand patterns. In March 2026, QQ Music became the first major music platform to deploy the latest Dolby AC-4 enhancements. South Korea's TTA standard requires MPEG-H Audio for next-generation television. Japan supports demand through gaming hardware, automotive relationships, and consumer electronics. Fraunhofer IDMT's Audiofields entered series production in Mercedes-Benz vehicles in February 2026.
Europe has a significant position in the Spatial audio software market because Fraunhofer-Gesellschaft contributes to MPEG-H standards development. Specialist suppliers in Germany and Poland also support the regional production base. The European Broadcasting Union's Audio Definition Model supports channel-based, object-based, and scene-based audio workflows. Dolby and Audi completed Dolby Atmos integration for selected Audi models in July 2025. South America, the Middle East, and Africa remain smaller but emerging markets. Brazil's SBTVD TV 3.0 standard includes MPEG-H Audio, while OTT investment and mobile-first content may add demand over time.
- Dolby Laboratories, Inc.
- Xperi Holding Corporation
- Goerdyna Group
- Waves Audio Ltd.
- Dear Reality GmbH
- Avid Technology, Inc.
- Fraunhofer-Gesellschaft zur Forderung der angewandten Forschung e. V.
- Blue Ripple Sound Limited
- Sound Particles, Lda.
- Audiokinetic Inc.
- Firelight Technologies Pty Ltd
- VisiSonics Corporation
- Spatial Inc.
- G'Audio Lab, Inc.
- Mach1, Inc.
- Envelop VR, Inc.
- APL-HUD GmbH
- atmoky GmbH
- Ceva, Inc.
- Brandenburg Labs GmbH
- New Audio Technology GmbH
- Wave Arts, Inc.
- SoundField Limited
- Zylia Sp. z o.o.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Immersive Gaming and XR Content Expansion
- 4.2.2 Streaming Platforms Mandating Spatial-Audio Deliverables
- 4.2.3 AI-Assisted Real-Time Rendering and HRTF Personalization
- 4.2.4 Cloud-Based Production and Remote Collaboration
- 4.2.5 Premium Device Standardization of Spatial Audio
- 4.2.6 Automotive and Enterprise Immersive-Audio Integration
- 4.3 Market Restraints
- 4.3.1 Fragmented Object-Based and Scene-Based Audio Standards
- 4.3.2 High Cost of Certified Immersive-Audio Rooms
- 4.3.3 Shortage of Spatial-Audio Engineering Talent
- 4.3.4 Platform Gatekeeping and Format-Conversion Dependency
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Software
- 5.1.2 Services
- 5.2 By Product Type
- 5.2.1 Spatial Audio Rendering Software
- 5.2.2 Binaural and HRTF Plugins
- 5.2.3 Ambisonics Production Plugins
- 5.2.4 Object-Based Mixing and Authoring Tools
- 5.2.5 Other Product Types
- 5.3 By Deployment Mode
- 5.3.1 On-Premises
- 5.3.2 Cloud-Based
- 5.4 By Application
- 5.4.1 Gaming
- 5.4.2 Music Production and Streaming
- 5.4.3 Film, Television, and Postproduction
- 5.4.4 Virtual Reality and Augmented Reality
- 5.4.5 Live Events and Broadcast
- 5.4.6 Automotive
- 5.4.7 Enterprise Collaboration and Training
- 5.5 By End User
- 5.5.1 Studios and Postproduction Houses
- 5.5.2 Game Developers and Publishers
- 5.5.3 Streaming and Media Platforms
- 5.5.4 Enterprises and Educational Institutions
- 5.5.5 Individual Professionals
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Russia
- 5.6.3.5 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Southeast Asia
- 5.6.4.6 Oceania
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 United Arab Emirates
- 5.6.5.2 Saudi Arabia
- 5.6.5.3 Turkey
- 5.6.5.4 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Dolby Laboratories, Inc.
- 6.4.2 Xperi Holding Corporation
- 6.4.3 Goerdyna Group
- 6.4.4 Waves Audio Ltd.
- 6.4.5 Dear Reality GmbH
- 6.4.6 Avid Technology, Inc.
- 6.4.7 Fraunhofer-Gesellschaft zur Forderung der angewandten Forschung e. V.
- 6.4.8 Blue Ripple Sound Limited
- 6.4.9 Sound Particles, Lda.
- 6.4.10 Audiokinetic Inc.
- 6.4.11 Firelight Technologies Pty Ltd
- 6.4.12 VisiSonics Corporation
- 6.4.13 Spatial Inc.
- 6.4.14 G'Audio Lab, Inc.
- 6.4.15 Mach1, Inc.
- 6.4.16 Envelop VR, Inc.
- 6.4.17 APL-HUD GmbH
- 6.4.18 atmoky GmbH
- 6.4.19 Ceva, Inc.
- 6.4.20 Brandenburg Labs GmbH
- 6.4.21 New Audio Technology GmbH
- 6.4.22 Wave Arts, Inc.
- 6.4.23 SoundField Limited
- 6.4.24 Zylia Sp. z o.o.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


