

|
시장보고서
상품코드
2154955
바이오에탄올 효모 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Bioethanol Yeast - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
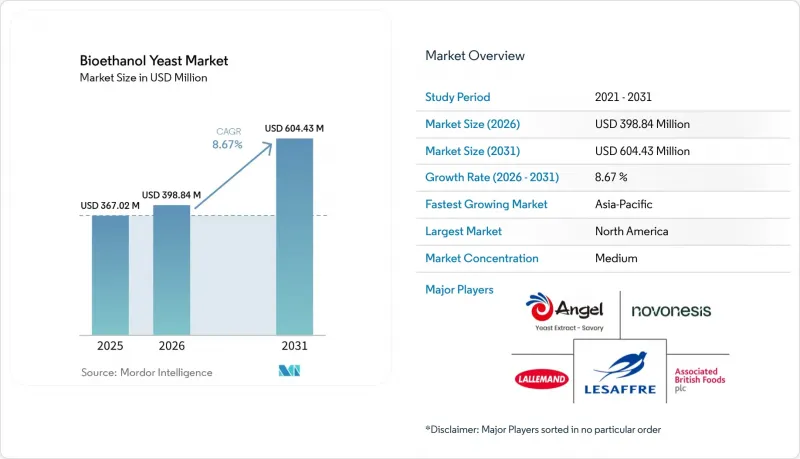
에 따르면 바이오에탄올 용효모 시장은 2025년 3억 6,702만 달러에서 2026년에는 3억 9,884만 달러로 확대하며, 2031년까지 6억 443만 달러에 달할 것으로 예측되고 있으며, 2026-2031년에 CAGR 8.67%를 기록할 전망입니다.
전 세계 바이오에탄올용 효모 시장의 동향 및 인사이트
전 세계 바이오에탄올 생산량 증가
각국에서 바이오에탄올 생산 및 무역이 확대됨에 따라 특수 발효용 효모에 대한 수요가 증가하고 있습니다. 에탄올 플랜트의 생산량이 증가하고 가동률이 향상됨에 따라 발효 속도 향상, 에탄올 수율 향상, 그리고 안정적인 생산 품질 유지를 가능하게 하는 신뢰성 높은 효모가 요구되고 있습니다. 경제협력개발기구(OECD)에 따르면 전 세계 에탄올 무역량은 2024년 110억 리터에서 2034년에는 119억 리터로 증가할 것으로 예측됩니다. 그러나 같은 기간 중 에탄올 총생산량에서 무역이 차지하는 비중은 8.8%에서 8.2%로 감소할 것으로 예상되며, 주요 시장에서는 국내 소비 및 생산이 계속해서 확대될 것으로 보입니다. 이러한 에탄올 생산 및 국경을 넘는 무역의 확대로 인해 바이오에탄올용 효모, 특히 생산자가 생산 시간을 단축하고, 플랜트 가동을 최적화하며, 공정 전반의 경제성을 향상시키는 데 도움이 되는 고수율·고효율 균주에 대한 안정적인 수요가 발생할 것으로 예상됩니다.
에탄올 혼합 의무 확대
연료 공급업체에 대해 휘발유에 대한 에탄올 혼합 비율을 높일 것을 의무화하는 정부 규제로 인해 바이오에탄올 및 그 생산에 사용되는 특수 효모에 대한 꾸준하고 장기적인 수요가 발생하고 있습니다. 미국에서는 환경보호청(EPA)이 2026년분 재생 가능 식별 번호(RIN)를 258억 2,000만 단위로 확정하고, 2026년과 2027년 양해에 걸쳐 기존의 바이오연료 목표인 150억 갤런을 유지했습니다. 또한 인도에서는 2026년에 에탄올 20%를 함유한 ‘E20 가솔린’의 도입이 예정되어 있으며, 이에 따라 인도의 에탄올 생산 수요도 증가하고 있습니다. 마찬가지로 유럽연합(EU)의 ‘재생에너지 지침 III(RED III)’에서는 2030년까지 운송 부문 에너지 소비량의 29%를 재생에너지로 충당하는 것을 목표로 하고 있습니다. 이러한 정책으로 인해 에탄올 생산자들에게는 수요 전망이 더욱 명확해졌으며, 옥수수나 사탕수수 등의 기존 원료뿐만 아니라 농업 잔여물을 포함한 첨단 원료 모두에 대해 효율적이고 고성능인 효모 균주에 대한 투자가 촉진되고 있습니다.
발효 조건에 대한 높은 민감도
효모는 발효 조건에 매우 민감하며, 이는 발효의 안정성, 에탄올 수율 및 플랜트의 생산성에 영향을 미쳐 전 세계 바이오에탄올용 효모 시장의 성장을 저해할 가능성이 있습니다. 산업용 효모는 에탄올의 독성, 삼투압, 온도 변동, pH 변화, 영양분 제한 및 오염 물질에 노출되어 있으며, 이 모든 요인은 효모의 생존율과 발효 효율을 저하시키는 요인이 됩니다. 'Fungal Biology'지에 게재된 연구에서는 이러한 스트레스가 에탄올 수율 및 전반적인 생산 효율에 부정적인 영향을 미칠 수 있다고 지적하고 있습니다. 한편, 'FEMS Yeast Research'지에서는 고비중 발효 및 리그노셀룰로오스 유래 억제 물질로 인해 발생하는 추가적인 과제가 강조되고 있습니다. 그 결과, 에탄올 생산자는 균주별 최적화, 공정 제어, 기술 지원이 필요할 수 있으며, 이로 인해 운영의 복잡성이 증가하고 발효 조건 관리가 어려운 지역에서는 도입이 제한될 우려가 있습니다.
부문 분석
2025년, 바이오에탄올용 효모 시장에서 건조 효모는 67.73%를 차지하며 형태 부문에서 주도적인 위치를 유지했습니다. 장기 보존성 덕분에 생산자는 운영의 연속성을 해치지 않고 효모를 장기간 보관할 수 있습니다. 보관, 운송, 취급의 용이성까지 더해져 에탄올 생산 시설 전반에 걸쳐 광범위하게 활용되고 있습니다. 이 형태는 안정적이고 즉각적인 효모 공급이 필요한 대규모 운영에 특히 적합합니다. 상업적 발효 공정에서의 확고한 용도가 바이오에탄올 산업 전반의 수요를 지속적으로 지원하고 있습니다.
액상 효모는 2031년까지 연평균 성장률(CAGR) 9.21%로 성장할 것으로 예측되며, 가장 빠르게 성장하는 형태 부문이 될 전망입니다. 즉시 사용 가능한 특성 덕분에 준비 과정이 간소화되어 발효를 더 빨리 시작할 수 있습니다. 생산자들은 발효 효율 향상, 효모 성능의 안정적 유지, 그리고 에탄올 수율 최적화를 위해 액상 효모의 도입을 점점 더 확대하고 있습니다. 또한 이 형태는 특히 운영 효율을 중시하는 시설에서 보다 정밀하게 제어된 발효 공정을 가능하게 합니다. 첨단 발효 기술에 대한 투자 확대는 액상 효모 부문의 추가적인 성장을 지원할 것으로 예상됩니다.
지역별 분석
2026년, 북미는 바이오에탄올용 효모 시장의 38.67%를 차지했습니다. 이는 특히 미국내 옥수수를 원료로 하는 에탄올 생산을 지원하는 광범위한 인프라 덕분입니다. 확립된 발효 시설, 통합된 공급망, 그리고 재생 가능 연료 기준(RFS)에 기반한 지원 정책이 에탄올 생산의 안정적인 기반을 지속적으로 제공하고 있습니다. 미국의 생산자들은 에탄올 수율 향상, 발효 주기 단축, 그리고 원치 않는 부산물 감축으로 이어지는 능력을 바탕으로 효모 기술 선정에 점점 더 중점을 두고 있습니다. 생산 효율과 운영 비용 최적화에 대한 관심이 높아짐에 따라 첨단 효모 균주의 도입이 더욱 가속화되고 있습니다. 캐나다와 멕시코 역시 에탄올 생산 확대 및 혼합 정책을 통해 해당 지역의 수요 증대에 기여하고 있습니다.
아시아태평양은 에탄올 혼합 의무 확대와 국내 생산 능력에 대한 투자에 힘입어 2031년까지 연평균 성장률(CAGR) 9.75%로 성장하며, 가장 빠르게 성장하는 지역 시장이 될 것으로 예측됩니다. 2026년 인도 전역에서 시행될 E20은 에탄올 수요를 대폭 강화하고, 고성능 발효 솔루션에 대한 수요를 높일 것으로 예상됩니다. 2025년 11월, 노보네시스(Novonesis)는 현지 열 및 삼투압 조건에서 발효를 지원하기 위해 인도에서 ‘Innova Delta’를 출시했습니다. 중국은 에탄올 혼합 비율이 상대적으로 낮아 성장 기회는 비교적 완만하지만, 정책 발전에 따라 장기적인 수요가 개선될 가능성이 있습니다. 일본, 호주 및 동남아시아 국가들은 재생 가능 연료 프로그램을 추진하고 에너지 원천의 다각화를 진행함에 따라 추가적인 성장의 길을 열어주고 있습니다.
유럽, 남미, 중동 및 아프리카에서는 원료 확보 가능성, 탈탄소화 정책, 그리고 에탄올 생산 인프라의 성숙도에 따라 형성되는 바이오에탄올용 효모 도입을 위한 다양한 기회가 제공되고 있습니다. 유럽의 ‘재생에너지 지침 III(RED III)’는 온실가스 배출 성능과 첨단 원료에 대한 관심을 높이고 있으며, 저탄소 에탄올 제조 공정의 효율을 향상시키는 효모 솔루션에 대한 수요를 지원하고 있습니다. 남미는 브라질의 확고한 사탕수수 에탄올 산업과 대규모 발효 능력을 견인력으로 삼아 계속해서 중요한 지역 시장으로 자리 잡고 있습니다. 중동 및 아프리카는 비교적 신흥 시장이며, 향후 수요는 인프라 구축, 원료 확보 가능성, 그리고 지원적인 규제 체계에 좌우될 것입니다. 재생 가능 연료와 에너지 안보에 대한 관심이 높아짐에 따라 이 지역 전반에 걸친 에탄올 생산 노력이 더욱 가속화될 가능성이 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 공급망 분석
- 기술 전망
- 규제 전망
- Porter's Five Forces
제5장 시장 규모와 성장 예측
- 포맷별
- 원료 유형별
- 용도별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 기타 북미 국가
- 유럽
- 독일
- 영국
- 이탈리아
- 프랑스
- 스페인
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 호주
- 기타 아시아태평양 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 남아프리카공화국
- 사우디아라비아
- 아랍에미리트
- 기타 중동 및 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 순위 분석
- 기업 개요
- Novonesis A/S
- LALLEMAND Inc.
- Lesaffre
- AngelYeast Co., Ltd.
- Associated British Foods plc
- AB Mauri
- International Flavors and Fragrances Inc.
- DSM-Firmenich AG
- Leiber GmbH
- Alltech, Inc.
- Oriental Yeast Co., Ltd.
- Biorigin
- Cargill, Incorporated
- Archer Daniels Midland Company
- POET, LLC
- Green Plains Inc.
- Alto Ingredients, Inc.
- MicroBioGen Pty Ltd
- Xylogenics, Inc.
- Ferm Solutions, Inc.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the bioethanol yeast market is projected to increase from USD 367.02 million in 2025 to USD 398.84 million in 2026 and reach USD 604.43 million by 2031, registering a CAGR of 8.67% during 2026-2031.
Global Bioethanol Yeast Market Trends and Insights
Rising Global Bioethanol Production
Growing bioethanol production and trade across countries are increasing the need for specialized fermentation yeast. As ethanol plants produce larger volumes and operate at higher capacity, they require reliable yeast that can improve fermentation speed, increase ethanol yield, and support consistent production quality. According to the Organization for Economic Co-operation and Development (OECD), global ethanol trade is projected to rise from 11.0 billion liters in 2024 into 11.9 billion liters by 2034. However, trade's share of total ethanol production is expected to decline from 8.8% to 8.2% over the same period, indicating that domestic consumption and production will continue to grow in major markets. This expansion in ethanol production and cross-border trade is expected to create steady demand for bioethanol yeast, particularly high-yield and high-efficiency strains that help producers reduce production time, optimize plant operations, and improve overall process economics.
Expansion of Ethanol-Blending Mandates
Government mandates requiring fuel suppliers to blend more ethanol into gasoline are creating steady, long-term demand for bioethanol and the specialized yeast used to produce it. In the United States, the Environmental Protection Agency (EPA) finalized a requirement of 25.82 billion Renewable Identification Numbers (RINs) for 2026 and retained a conventional biofuel target of 15 billion gallons for both 2026 and 2027. India's rollout of E20 petrol, which contains 20% ethanol, in 2026 is also increasing the country's ethanol production needs. Similarly, the European Union's Renewable Energy Directive III (RED III) aims for renewable energy to account for 29% of transport energy use by 2030. These policies provide ethanol producers with clearer demand expectations and encourage them to invest in efficient, high-performance yeast strains for both conventional feedstocks, such as corn and sugarcane, and advanced feedstocks, including agricultural residues.
High Sensitivity to Fermentation Conditions
The high sensitivity of yeast to fermentation conditions can restrain the global bioethanol yeast market by affecting fermentation consistency, ethanol yield, and plant productivity. Industrial yeast is exposed to ethanol toxicity, osmotic pressure, temperature fluctuations, pH changes, nutrient limitations, and contaminants, all of which can reduce yeast viability and fermentation efficiency. Research published in Fungal Biology notes that these stresses can negatively affect ethanol yields and overall production efficiency, while FEMS Yeast Research highlights the additional challenges created by high-gravity fermentation and lignocellulosic inhibitors. Consequently, ethanol producers may require strain-specific optimization, process control, and technical support, increasing operational complexity and potentially limiting adoption where fermentation conditions are difficult to manage.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Second-Generation Bioethanol
- Growing Adoption of High-Performance Yeast Strains
- High Cost of Specialized Yeast Strains
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dry Yeast accounted for 67.73% of the bioethanol yeast market in 2025, maintaining its leading position in the format segment. Its extended shelf life enables producers to store yeast for longer periods without compromising operational continuity. Ease of storage, transportation, and handling further supports its widespread use across ethanol production facilities. The format is particularly well-suited to large-scale operations that require a stable and readily available yeast supply. Its established application in commercial fermentation processes continues to support demand across the bioethanol industry.
Liquid Yeast is projected to grow at a 9.21% CAGR through 2031, making it the fastest-growing format segment. Its ready-to-use characteristics reduce preparation requirements and enable faster initiation of fermentation. Producers are increasingly adopting liquid yeast to improve fermentation efficiency, maintain consistent yeast performance, and optimize ethanol yields. The format can also support more controlled fermentation processes, particularly in facilities focused on operational efficiency. Growing investment in advanced fermentation technologies is expected to further support the expansion of the Liquid Yeast segment.
Complete Report Scope:
- By Format
- Dry Yeast
- Liquid Yeast
- By Feedstock Type
- Sugarcane
- Wheat
- Corn
- Others
- By Application
- Industrial Ethanol
- Fuel Ethanol
- By Geography
- North America
- United States
- Canada
- Mexico
- Rest of North America
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- South Africa
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for 38.67% of the bioethanol yeast market in 2026, supported by the region's extensive corn-based ethanol production infrastructure, particularly in the United States. Established fermentation facilities, integrated supply chains, and supportive policies under the Renewable Fuel Standard continue to provide a stable foundation for ethanol production. U.S. producers are increasingly selecting yeast technologies based on their ability to improve ethanol yield, shorten fermentation cycles, and reduce unwanted by-products. The growing focus on production efficiency and operating cost optimization is further supporting the adoption of advanced yeast strains. Canada and Mexico also contribute to regional demand through expanding ethanol production and blending initiatives.
Asia Pacific is projected to be the fastest-growing regional market, expanding at a 9.75% CAGR through 2031, driven by increasing ethanol blending mandates and investments in domestic production capacity. India's nationwide E20 implementation in 2026 is expected to significantly strengthen ethanol demand and increase the need for high-performing fermentation solutions. In November 2025, Novonesis launched Innova Delta in India to support fermentation under local thermal and osmotic conditions. China offers a more moderate growth opportunity because of its relatively low ethanol blending rate, although policy developments could improve long-term demand. Japan, Australia, and Southeast Asian countries provide additional growth avenues as they advance renewable fuel programs and diversify energy sources.
Europe, South America, and the Middle East & Africa offer diverse opportunities for bioethanol yeast adoption, shaped by feedstock availability, decarbonization policies, and the maturity of ethanol production infrastructure. Europe's Renewable Energy Directive III (RED III) is increasing the focus on greenhouse gas performance and advanced feedstocks, supporting demand for yeast solutions that improve the efficiency of lower-carbon ethanol pathways. South America remains a key regional market, led by Brazil's well-established sugarcane ethanol industry and its large-scale fermentation capacity. The Middle East and Africa represent comparatively emerging markets, where future demand will depend on infrastructure development, feedstock availability, and supportive regulatory frameworks. Growing interest in renewable fuels and energy security could further support ethanol production initiatives across these regions.
- Novonesis A/S
- LALLEMAND Inc.
- Lesaffre
- AngelYeast Co., Ltd.
- Associated British Foods plc
- AB Mauri
- International Flavors and Fragrances Inc.
- DSM-Firmenich AG
- Leiber GmbH
- Alltech, Inc.
- Oriental Yeast Co., Ltd.
- Biorigin
- Cargill, Incorporated
- Archer Daniels Midland Company
- POET, LLC
- Green Plains Inc.
- Alto Ingredients, Inc.
- MicroBioGen Pty Ltd
- Xylogenics, Inc.
- Ferm Solutions, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising global bioethanol production
- 4.2.2 Expansion of ethanol-blending mandates
- 4.2.3 Growing adoption of high-performance yeast strains
- 4.2.4 Shift toward high-efficiency fermentation processes
- 4.2.5 Expansion of second-generation bioethanol
- 4.2.6 Advancements in yeast strain engineering
- 4.3 Market Restraints
- 4.3.1 High sensitivity to fermentation conditions
- 4.3.2 High cost of specialized yeast strains
- 4.3.3 Competition from alternative fermentation technologies
- 4.3.4 Dependence on bioethanol industry economics
- 4.4 Supply Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Format
- 5.1.1 Dry Yeast
- 5.1.2 Liquid Yeast
- 5.2 By Feedstock Type
- 5.2.1 Sugarcane
- 5.2.2 Wheat
- 5.2.3 Corn
- 5.2.4 Others
- 5.3 By Application
- 5.3.1 Industrial Ethanol
- 5.3.2 Fuel Ethanol
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.1.4 Rest of North America
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 Italy
- 5.4.2.4 France
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 South Africa
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 United Arab Emirates
- 5.4.5.4 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Ranking Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials (if available), Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Novonesis A/S
- 6.4.2 LALLEMAND Inc.
- 6.4.3 Lesaffre
- 6.4.4 AngelYeast Co., Ltd.
- 6.4.5 Associated British Foods plc
- 6.4.6 AB Mauri
- 6.4.7 International Flavors and Fragrances Inc.
- 6.4.8 DSM-Firmenich AG
- 6.4.9 Leiber GmbH
- 6.4.10 Alltech, Inc.
- 6.4.11 Oriental Yeast Co., Ltd.
- 6.4.12 Biorigin
- 6.4.13 Cargill, Incorporated
- 6.4.14 Archer Daniels Midland Company
- 6.4.15 POET, LLC
- 6.4.16 Green Plains Inc.
- 6.4.17 Alto Ingredients, Inc.
- 6.4.18 MicroBioGen Pty Ltd
- 6.4.19 Xylogenics, Inc.
- 6.4.20 Ferm Solutions, Inc.


