

|
시장보고서
상품코드
2155237
나프탈렌 술폰산염 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Naphthalene Sulfonate - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
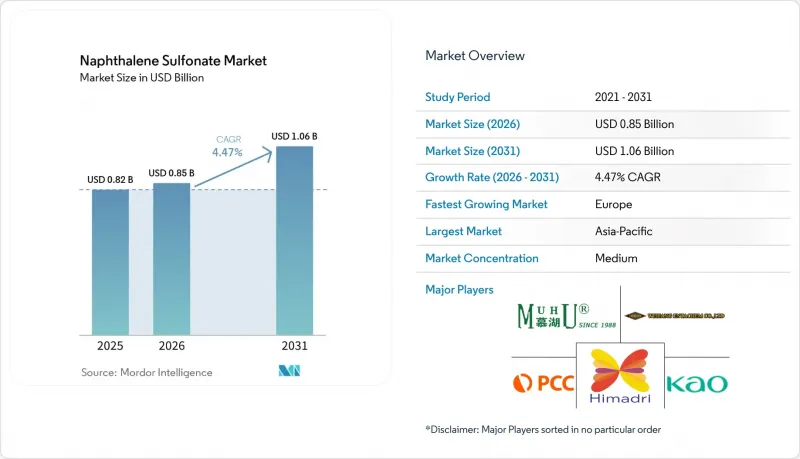
에 따르면 나프탈렌 술폰산염 시장 규모는 2025년에 8억 2,000만 달러로 추계되고 있으며, 2026년 8억 5,000만 달러에서 2031년까지 10억 6,000만 달러로 확대하며, 예측 기간(2026-2031년)에 CAGR은 4.47%에 달할 것으로 전망되고 있습니다.
전 세계 나프탈렌술폰산염 시장의 동향 및 인사이트
인프라 개발 및 고성능 콘크리트 수요
아시아태평양의 공공 인프라 사업은 수축 억제제에 대한 수년에 걸친 수요를 지원하고 있습니다. 이는 철도 회랑, 교량, 지하철, 고속도로 프로젝트에서 장기간에 걸친 건설 기간 중 지속적인 콘크리트 공급이 필요하기 때문입니다. 베트남은 하노이와 호치민시를 연결하는 670억 달러 규모의 고속철도 회랑 계획을 승인했습니다. 필리핀에서는 39억 1,000만 달러 규모의 바탄-카비테 인터링크 교량 건설이 진행 중이며, 한편 인도에서는 레디믹스 콘크리트 및 프리캐스트 콘크리트의 생산 능력을 활용하는 지하철 확장 및 고속도로 회랑을 포함한 ‘국가 인프라 파이프라인’에 기반한 공사가 계속되고 있습니다. 이러한 사업에서는 대량 타설, 프리캐스트 부재, 토목 공사에 걸쳐 막대한 양의 콘크리트가 필요합니다. 나프탈렌술폰산 포름알데히드(NSF)계 감수제를 사용함으로써 물-시멘트 비율을 15-25% 낮출 수 있습니다. 도로 및 교량 건설은 주택용 콘크리트 수요보다 빠르게 확대되고 있으며, 토목 프로젝트를 위한 레디믹스 및 프리캐스트 플랜트에 대한 구매가 촉진되고 있습니다. 이러한 구매자들은 보관 및 이동식 플랜트 네트워크를 통한 유통이 용이하므로 중급 등급의 설폰화 나프탈렌-포름알데히드(SNF) 분말을 점점 더 선호하고 있으며, 이로 인해 나프탈렌술폰산 시장에는 장기적인 건설 일정을 통해 지속적인 수요 채널이 형성되고 있습니다.
농약 및 섬유용 분산제 용도의 확대
나프탈렌술폰산에 대한 수요는 콘크리트 분야에 그치지 않고, NSF는 농약 및 섬유 제조 공정에서 분산제 및 습윤제로 기능하고 있습니다. 농약 제품에서 분산제 NNO는 습윤성 분말, 수분산성 과립 및 현탁 농축액 내에서 고체 입자를 현탁된 상태로 유지하여, 제제 제조업체가 수질이나 보관 조건의 변동에도 불구하고 안정적인 제품을 유지할 수 있도록 합니다. 이를 통해 균일한 살포 피복과 유효 성분의 안정적인 공급이 실현됩니다. 섬유 염색욕에서는 NSF가 특히 폴리아미드 섬유 및 단백질 섬유용 배트 염료, 반응성 염료, 분산 염료의 균염제로 기능합니다. 남아시아 및 동남아시아의 폴리에스테르 의류 생산 거점이 이러한 수요 기반을 지원하고 있습니다. REACH 규정 및 관련 프레임워크의 요건에 따라 일부 섬유 제제 제조업체는 성능과 비용의 균형이 여전히 양호한 분야에서 NSF 등급의 사용을 지속하고 있으며, 이로 인해 기존의 콘크리트 수요를 뛰어넘는 나프탈렌설포네이트 시장이 지탱되고 있습니다.
폴리카복실산 에테르계 고성능 감수제와의 경쟁
폴리카복실산 에테르(PCE)계 고성능 감수제는 첨단 콘크리트 용도에서 나프탈렌술폰산 포름알데히드(NSF)의 잠재 시장을 제한하고 있습니다. PCE계 고성능 감수제는 NSF의 1-2시간에 비해 4-6시간의 슬럼프 유지 시간을 제공하므로 자가 충진 콘크리트나 타설 전에 더 긴 작업성이 필요한 용도에 적합합니다. 이로 인해 고밀도 철근 구조물에서 자가 충진 콘크리트의 사용이 촉진되고 있지만, 동일한 첨가량으로는 NSF로는 일관되게 동등한 결과를 얻을 수 없습니다. 중국 양쯔강 삼각주 지역과 인도 서부 산업 회랑에 대한 자동 첨가 시스템에 대한 투자로 인해 보다 복잡한 PCE 배합의 사용 정확도와 실용성이 향상되어 NSF의 운영상 우위가 약화되고 있습니다. MUHU(중국) 건자재 및 유사한 공급업체들은 NSF와 PCE 요소를 결합한 하이브리드 제품을 개발하고 있습니다. 고객들이 더 고성능의 대체품으로 전환함에 따라 특히 첨단 콘크리트 사양이 표준화되고 있는 나프탈렌술폰산염 시장 부문에서 순수 NSF 공급업체들은 표준 등급의 이익률 압박에 직면하고 있습니다.
부문 분석
2025년 현재, 분말은 나프탈렌술폰산염 시장 점유율의 55.12%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 4.89%로 성장할 것으로 예측됩니다. 이러한 선도적인 지위는 보관 조건이 제각각이고 배송 경로가 긴 지방 건설 지역에 서비스를 제공하는 판매 대리점을 포함한 분산된 고객 네트워크 전반에 걸친 보관, 운송 및 취급상 이점을 반영합니다. 분말 등급의 유통 기한은 18-24개월인 반면, 액체 등급은 6-12개월이므로, 외딴 지역의 건설 현장이나 농업용 배합 업체에 서비스를 제공하는 판매 대리점의 경우 재고 손실 위험을 줄일 수 있습니다. 또한 대량의 물을 운송할 필요가 없어지므로, 드라이믹스 공급업체는 현장에 액체 처리 시스템이 없더라도 콘크리트 혼합물을 제조할 수 있게 됩니다. 이러한 특징은 남아시아, 아프리카, 라틴아메리카 전역의 지방 건설 현장에서 중요합니다. 고순도·저황산염 등급에 대한 수요 또한 나프탈렌술폰산 분말 시장의 성장을 지원하고 있습니다. 프리미엄 분말 등급은 유럽의 입찰에서 저포름알데히드 함유 제품과 관련된 15-30%의 가격 프리미엄을 감당할 수 있습니다.
액상 NSF는 자동 투여 작업을 수행하는 대규모 레디믹스트 플랜트에서 여전히 중요하지만, 레디믹스 콘크리트에서 액상 PCE 시스템의 채택이 확대됨에 따라 그 상대적 성장률은 둔화되고 있습니다. 분말은 기존 용도를 넘어선 기술적 개선도 지원하고 있습니다. 미국 특허 제12,698,235호는 모래를 많이 포함하는 건설용 혼합물에서 점토의 영향을 덜 받는 성능을 실현하도록 설계된 나프탈렌술폰산 중축합체를 대상으로 합니다. ASTM C494 유형 F 요건을 포함한 ISO 및 ASTM 표준 준수는 북미 인프라 공급에서 인증상의 고려 사항이 됩니다. 중국의 조달 기준 GB 8076도 유사한 품질 기준을 마련하고 있습니다. 규격 적합 등급과 범용 등급 분말의 차이는 보고된 시장 점유율 수치를 넘어 공급업체의 시장내 입지에 영향을 미칩니다. 이러한 구분은 제품 선정, 문서화 및 일관된 로트 품질을 통해 고객을 지원하는 공급업체에 유리하게 작용합니다. 또한 인프라 구매자가 신뢰할 수 있는 승인 기록을 요구함에 따라 경쟁은 단순히 납품 가격에만 국한되지 않게 됩니다. 확립된 시험 절차를 갖춘 제조업체는 이러한 요구에 신속하게 대응할 수 있으며, 판매 파트너는 보다 명확한 기술적 포지셔닝을 가진 분말 등급을 취급할 수 있습니다. 이러한 요인들이 나프탈렌설포네이트 시장 전체에서 분말의 역할을 강화하고 있습니다.
지역별 분석
유럽은 2031년까지 연평균 성장률(CAGR) 5.07%로 성장할 것으로 예측되며, 나프탈렌설포네이트 시장에서 가장 두드러진 성장을 보일 것으로 전망됩니다. 이 지역의 수요는 개보수 공사, 더욱 엄격해진 제품 요건, 그리고 콘크리트 보수 용도에 의해 지원되고 있습니다. 저포름알데히드 등급 및 인증 등급 제품은 가격 이외의 요소에서 경쟁력을 발휘하고 있습니다. 2025년 12월부터 2026년 5월에 걸쳐 개정된 ‘건축물 에너지 성능에 관한 지침’에 따라 16건의 ‘국가 건축물 개보수 계획’안이 제출되었습니다. NSF를 기반으로 한 보수용 모르타르 및 그라우트는 소량 생산이나 슬럼프 유지 시간 연장이 반드시 필요하지 않은 다양한 보수용 배합에 적합합니다. 이탈리아의 ‘국가 회복 및 회복탄력성 계획’은 인프라, 디지털화, 녹색 전환을 우선 과제로 삼고 있으며, 이에 따라 콘크리트 자재에 대한 수요가 증가하고 있습니다.
2025년, 아시아태평양은 나프탈렌설포네이트 시장 점유율의 43.57%를 차지했으며, 중국의 SNF 생산 규모와 인도의 인프라 계획이 이를 지원했습니다. 이러한 프로젝트들은 콘크리트 수요를 지원하며, 레디믹스트 플랜트, 프리캐스트 시설, 토목 공사 도급업체에 안정적으로 공급할 수 있는 제조사를 포함하여 광범위한 유통 네트워크를 갖춘 공급업체를 우대하고 있습니다. 북미에서는 인프라 보수 및 유정 시멘트 충진 분야의 수요가 안정적이지만, 국내 생산자는 ‘유해물질 규제법(TSCA)’에 따른 화학물질 보고 및 기록 보관 요건을 충족해야 합니다. 이 체계로 인해 규정 준수 비용이 발생하지만, 소규모 제조업체의 경우 그 부담을 감당하기가 더욱 어렵습니다. 대규모 생산자는 높은 생산량을 통해 규정 준수 업무의 부담을 분산시킬 수 있지만, 소규모 공급업체는 동일한 의무를 이동하기 위한 자원이 제한적일 수 있습니다.
브라질과 아르헨티나를 필두로 한 남미에서는 공공 인프라 주기와 연동된 건설 수요와 농약 수요가 결합되어 있습니다. 브라질의 인프라 컨세션 프로젝트와 작물 보호 활동은 NSF의 판매에 두 가지 서로 다른 판로를 제공하며, 국내 건설 고객 이외의 수요를 모색하는 아시아 생산자들의 관심을 끌고 있습니다. 사우디아라비아와 남아프리카공화국은 중동 및 아프리카 전역의 건설 수요를 주도하고 있는 반면, 사하라 이남 아프리카의 농업 개발 프로그램은 농약 등급 원료의 조기 구매를 지원하고 있습니다. 나프탈렌설포네이트 시장은 인프라 투자, 제형 요건 및 현지 규정 준수 능력에 따라 지역별로 뚜렷한 수요 패턴을 보이고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 폼별
- 용도별
- 최종사용자 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Bailin Group Co., Ltd
- Enaspol a.s.
- Giovanni Bozzetto S.p.A.
- Himadri Speciality Chemical Ltd
- Hubei Aging Chemical Co., Ltd.
- Kao Corporation
- MUHU(China) Construction Materials Co., Ltd.
- Nease Performance Chemicals
- PCC Group
- Shandong Jufu Chemical Technology Co., Ltd.
- Shandong Laiwu Wenhe Chemicals Co., Ltd.
- Shandong Wanshan Chemical Co., Ltd.
- Shanxi Jiankai Fine Chemicals Co., Ltd.
- WEIFANG ENTACHEM CO.,LTD
- Wuhan Xinyingda Chemicals Co., Ltd.
제7장 시장 기회와 향후 전망
KSA 26.10.28According to Mordor Intelligence, the naphthalene sulfonate market size was estimated at USD 0.82 billion in 2025 and is estimated to grow from USD 0.85 billion in 2026 to USD 1.06 billion by 2031, at a CAGR of 4.47% during the forecast period (2026-2031).
Global Naphthalene Sulfonate Market Trends and Insights
Infrastructure Development and High-Performance Concrete Demand
Public infrastructure programs in the Asia-Pacific region support multi-year demand for water-reducing admixtures, as rail corridors, bridges, metros, and highway projects require recurring concrete deliveries over extended construction periods. Vietnam approved a USD 67 billion high-speed rail corridor between Hanoi and Ho Chi Minh City. The Philippines advanced the USD 3.91 billion Bataan-Cavite Interlink Bridge, while India continued work under its National Infrastructure Pipeline, which includes metro expansions and highway corridors that draw on ready-mix and precast capacity. These programs require substantial concrete quantities across mass pours, precast elements, and civil works. Naphthalene Sulfonate Formaldehyde (NSF)-based water reducers can lower the water-to-cement ratio by 15-25%. Road and bridge construction has been expanding faster than residential concrete use, directing purchases toward ready-mix and precast plants serving civil projects. These buyers increasingly prefer mid-grade Sulfonated Naphthalene Formaldehyde (SNF) powder due to its ease of storage and distribution across mobile plant networks, providing the naphthalene sulfonate market with a recurring demand channel throughout long construction schedules.
Expansion of Agrochemical and Textile Dispersant Applications
Demand for naphthalene sulfonate extends beyond concrete, as NSF serves as a dispersant and wetting agent in agrochemical and textile processes. In agrochemical products, Dispersant NNO keeps solid particles suspended in wettable powders, water-dispersible granules, and suspension concentrates, enabling formulators to maintain stable products across variations in water quality and storage conditions. This supports even spray coverage and consistent availability of active ingredients. In textile dye baths, NSF functions as a leveling agent for vat, reactive, and disperse dyes, particularly for polyamide and protein fibers. South and Southeast Asian production centers for polyester-based garments support this demand base. Requirements under REACH and related frameworks have led some textile formulators to continue using NSF grades where the performance-cost balance remains favorable, supporting the naphthalene sulfonate market beyond conventional concrete demand.
Competition from Polycarboxylate Ether Superplasticizers
Polycarboxylate ether (PCE) superplasticizers limit the addressable market for Naphthalene Sulfonate Formaldehyde (NSF) in advanced concrete applications. PCE superplasticizers offer slump retention of 4-6 hours, compared with 1-2 hours for NSF, making them suited for self-consolidating concrete and applications requiring longer workability before placement. This supports the use of self-consolidating concrete in densely reinforced structures, where NSF cannot consistently deliver equivalent results at similar dosages. Automated dosing investments in China's Yangtze River Delta and India's western industrial corridor reduce NSF's operational advantage by improving the accuracy and practicality of using more complex PCE formulations. MUHU (China) Building Materials Co., Ltd. and similar suppliers have developed hybrid products combining NSF and PCE elements. Pure NSF suppliers face margin pressure on standard grades as customers shift toward higher-performance alternatives, particularly in segments of the naphthalene sulfonate market where advanced concrete specifications are becoming standard.
Other drivers and restraints analyzed in the detailed report include:
- Cost-Efficient Water Reduction in Concrete Formulations
- Formaldehyde-Free and Lower-Emission Product Innovation
- Formaldehyde Exposure and Emission Compliance Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Powder held 55.12% of the naphthalene sulfonate market share in 2025 and is forecast to grow at a 4.89% CAGR through 2031. Its leading position reflects advantages in storage, transport, and handling across distributed customer networks, including distributors serving rural construction areas with uneven storage conditions and long delivery routes. Powder grades provide an 18-24-month shelf life, compared with 6-12 months for liquid grades, reducing the risk of inventory loss for distributors serving distant construction clusters and agricultural formulators. They also eliminate the need to transport bulk water and allow dry-mix suppliers to prepare concrete blends without on-site liquid-handling systems. These features are relevant in rural construction areas across South Asia, Africa, and Latin America. Demand for high-purity, low-sulfate grades also supports the naphthalene sulfonate powder market. Premium powder grades can support the 15-30% price premium associated with lower-formaldehyde variants in European tenders.
Liquid NSF remains relevant for large ready-mix plants with automated dosing operations, though its relative growth is slower as liquid PCE systems gain acceptance in ready-mix concrete. Powder also supports technical improvements beyond established uses. U.S. Patent 12,698,235 covers naphthalenesulfonic acid polycondensates designed for modified clay-insensitive performance in sand-rich construction mixes. ISO and ASTM alignment, including ASTM C494 Type F requirements, adds a certification consideration for North American infrastructure supply. China's GB 8076 procurement standard creates a similar quality threshold. The difference between compliant-grade and commodity-grade powder affects supplier positioning beyond reported share figures. This distinction favors suppliers that support customers through product selection, documentation, and consistent batch quality. It also shifts competition beyond delivered price, as infrastructure buyers require reliable approval records. Producers with established testing procedures can respond more readily to these requests, and distribution partners can carry powder grades with clearer technical positioning. These factors reinforce powder's role across the naphthalene sulfonate market.
Complete Report Scope:
- By Form
- Liquid
- Powder
- By Application
- Dispersant and Wetting Agent
- Plasticizer
- Surfactants
- Other Applications
- By End-User Industry
- Building and Construction
- Agriculture
- Textile and Leather
- Household Cleaning
- Other End-Use Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Europe is forecast to grow at a 5.07% CAGR through 2031, making it the fastest-growing geography in the naphthalene sulfonate market. Regional demand is supported by renovation activity, stricter product requirements, and concrete repair applications. Lower-formaldehyde and documented grades compete on factors beyond price. Sixteen draft National Building Renovation Plans were submitted between December 2025 and May 2026 under the revised Energy Performance of Buildings Directive. NSF-based repair mortars and grouts are suited to smaller batches and varied renovation formulations that do not always require extended slump retention. Italy's National Recovery and Resilience Plan supports infrastructure, digitalization, and green transition priorities, thereby increasing demand for concrete materials.
Asia-Pacific held 43.57% of the naphthalene sulfonate market share in 2025, supported by China's SNF production scale and India's infrastructure pipeline. These projects support concrete demand and favor suppliers that can serve wide distribution networks, including producers capable of consistently supplying ready-mix plants, precast facilities, and civil-work contractors. North America has a stable demand in infrastructure repair and oil well cementing, while domestic producers must meet chemical reporting and recordkeeping requirements under the Toxic Substances Control Act. This framework adds compliance costs that smaller manufacturers find harder to absorb. Larger producers can distribute compliance work across higher output, while smaller suppliers may have fewer resources to meet the same obligations.
South America, led by Brazil and Argentina, combines construction demand linked to public infrastructure cycles with agrochemical demand. Brazil's infrastructure concession pipeline and crop-protection activity offer two separate channels for NSF sales and have attracted interest from Asian producers seeking demand beyond their domestic construction customers. Saudi Arabia and South Africa drive construction demand across the Middle East and Africa, while agricultural development programs in sub-Saharan Africa support early purchases of agrochemical-grade materials. The naphthalene sulfonate market exhibits distinct regional demand patterns driven by infrastructure investment, formulation requirements, and local compliance capacity.
- Bailin Group Co., Ltd
- Enaspol a.s.
- Giovanni Bozzetto S.p.A.
- Himadri Speciality Chemical Ltd
- Hubei Aging Chemical Co., Ltd.
- Kao Corporation
- MUHU (China) Construction Materials Co., Ltd.
- Nease Performance Chemicals
- PCC Group
- Shandong Jufu Chemical Technology Co., Ltd.
- Shandong Laiwu Wenhe Chemicals Co., Ltd.
- Shandong Wanshan Chemical Co., Ltd.
- Shanxi Jiankai Fine Chemicals Co., Ltd.
- WEIFANG ENTACHEM CO.,LTD
- Wuhan Xinyingda Chemicals Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure Development and High-Performance Concrete Demand
- 4.2.2 Expansion of Agrochemical and Textile Dispersant Applications
- 4.2.3 Cost-Efficient Water Reduction in Concrete Formulations
- 4.2.4 Formaldehyde-Free and Lower-Emission Product Innovation
- 4.2.5 Renewable Naphthalene Feedstock Development
- 4.3 Market Restraints
- 4.3.1 Competition from Polycarboxylate Ether Superplasticizers
- 4.3.2 Formaldehyde Exposure and Emission Compliance Requirements
- 4.3.3 Feedstock and Energy-Price Volatility
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Form
- 5.1.1 Liquid
- 5.1.2 Powder
- 5.2 By Application
- 5.2.1 Dispersant and Wetting Agent
- 5.2.2 Plasticizer
- 5.2.3 Surfactants
- 5.2.4 Other Applications
- 5.3 By End-User Industry
- 5.3.1 Building and Construction
- 5.3.2 Agriculture
- 5.3.3 Textile and Leather
- 5.3.4 Household Cleaning
- 5.3.5 Other End-Use Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Bailin Group Co., Ltd
- 6.4.2 Enaspol a.s.
- 6.4.3 Giovanni Bozzetto S.p.A.
- 6.4.4 Himadri Speciality Chemical Ltd
- 6.4.5 Hubei Aging Chemical Co., Ltd.
- 6.4.6 Kao Corporation
- 6.4.7 MUHU (China) Construction Materials Co., Ltd.
- 6.4.8 Nease Performance Chemicals
- 6.4.9 PCC Group
- 6.4.10 Shandong Jufu Chemical Technology Co., Ltd.
- 6.4.11 Shandong Laiwu Wenhe Chemicals Co., Ltd.
- 6.4.12 Shandong Wanshan Chemical Co., Ltd.
- 6.4.13 Shanxi Jiankai Fine Chemicals Co., Ltd.
- 6.4.14 WEIFANG ENTACHEM CO.,LTD
- 6.4.15 Wuhan Xinyingda Chemicals Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


