

|
시장보고서
상품코드
2155546
자동차 랩핑 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Automotive Wrap - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
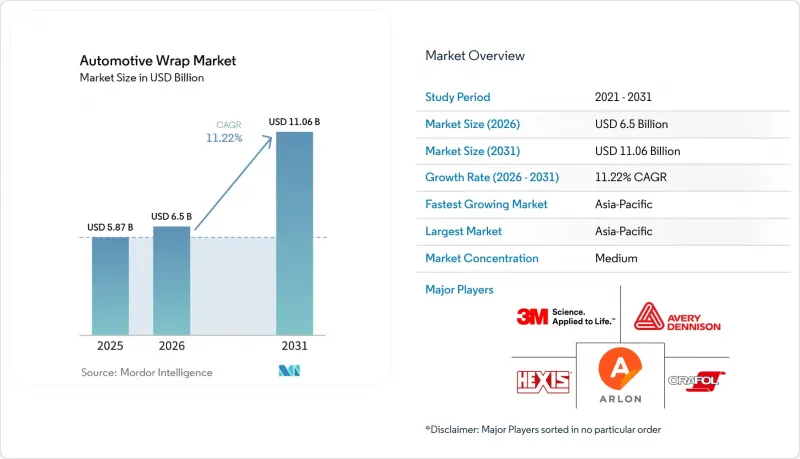
에 의하면, 자동차 랩핑 시장 규모는 2025년에 58억 7,000만 달러로 평가되었고, 2026년 65억 달러에서 2031년까지 110억 6,000만 달러에 이를 것으로 예측되며, 예측 기간(2026년-2031년) CAGR은 11.22%를 기록할 전망입니다.
세계 자동차 래핑 시장 동향 및 인사이트
차량 커스터마이징 및 미적 개인화
전문용 필름이 소비자에게 더 쉽게 구할 수 있게 됨에 따라, 차량 개인화는 일부 애호가라는 좁은 계층을 넘어 확산되고 있습니다. 구매자들은 기존의 재도장으로는 같은 유연성으로 구현할 수 없는 풀 컬러 변경이나 매트, 새틴, 크롬, 컬러 시프트 등의 마감을 원하고 있습니다. 2024년 미국의 특수 차량 개조 지출은 526억 5,000만 달러에 달했으며, 이러한 애프터마켓 활동에서 차량 외관 관련 제품의 점유율이 확대되고 있습니다. 자동차 래핑 시장은 이러한 추세의 혜택을 받고 있습니다. 필름을 부착함으로써 출고 시 도장을 영구적으로 변경하지 않고도 차량의 외관을 바꿀 수 있기 때문입니다. 일부 자동차 제조업체는 공장 출고 시 디자인과 어울리는 디자인을 제공하는 딜러 연계 프로그램을 시범적으로 도입하고 있으며, 소매 수요에 더해 기업 간 거래(B2B)의 새로운 판로가 생길 가능성이 있습니다. 또한, 이러한 프로그램들은 자동차 래핑 시장 전체에서 시공 업체와 필름에 대한 성능 면에서의 기대치를 높이는 결과로 이어지고 있습니다.
플릿 브랜딩과 모바일 광고
인구 밀도가 높은 도시 지역에서 래핑이 적용된 차량은 현지 교통 상황에 따라 하루에 3만에서 7만 회에 달하는 시인 효과를 창출할 수 있습니다. 이러한 시인성 덕분에 차량 운영 사업자에게는 다른 광고 형식과 더불어 차량 그래픽을 활용해야 할 명확한 이유가 생깁니다. 물류 및 전자상거래 사업자들은 차량 브랜딩을 자사 운영 모델의 실용적인 요소로 인식하기 시작했습니다. 3년에서 5년에 이르는 교체 주기로 인해 필름 공급업체와 시공 업체에게는 일회성 소매 업무가 아닌 지속적인 수주가 발생합니다. 라스트 마일 배송, 라이드셰어, 음식 배달 차량은 아시아태평양 및 유럽의 차량 래핑 시장 잠재 고객 기반을 확대되고 있습니다. 또한, 부분 래핑은 중요한 식별 정보나 브랜딩 영역을 커버함으로써 소규모 사업자의 진입 비용을 절감합니다.
높은 시공 비용과 숙련된 인력에 대한 의존
전문가가 차량 전체를 래핑하는 데는 차량의 크기와 차체의 복잡성에 따라 14-28시간의 작업 시간이 소요됩니다. 수요가 높은 북미에서는 숙련된 시공자의 시급이 95달러에 달하여 고품질 시공 비용을 상승시키고 있습니다. 미국에는 연방 정부가 의무화한 시공자 인증 기준이 없기 때문에 시공 품질에 편차가 발생하고 있습니다. 해당 지역에 자격을 갖춘 시공자가 없는 경우, 구매자는 구매를 미룰 가능성이 있습니다. 제조업체나 업계 단체의 교육 프로그램은 SEMA(Specialty Equipment Market Association)가 지원하는 전문 역량 개발을 포함하여 기술자 양성에 기여하고 있습니다. 그러나 교육 수용 능력의 한계로 인해 북미, 유럽, 아시아태평양의 소규모 도시에서 자동차 래핑 시장의 성장은 여전히 제약을 받고 있습니다.
부문 분석
2025년, 캐스트 필름은 자동차 래핑 시장 점유율의 55.13%를 차지했습니다. 제조 공정으로 인해 내부 응력이 감소하기 때문에 복합 곡면, 깊은 홈, 리벳으로 고정된 표면에도 필름이 밀착됩니다. 이러한 특성 덕분에 캐스트 필름은 마감 품질과 가장자리의 안정성이 중요한 차량 전체에 시공하기에 적합합니다. 3M사는 까다로운 조건에서의 시공을 위해 설계된 차량 래핑 필름을 제공하며, 전문 시공업체들이 프리미엄 필름 시스템을 선호하는 추세를 뒷받침하고 있습니다. 캐스트 필름은 시공이 어려운 3차원 표면에서 여전히 표준 제품으로 자리 잡고 있으며, 이는 자동차 래핑 시장에서 해당 제품의 매출에 크게 기여하고 있습니다.
캘린더 성형 필름은 2031년까지 연평균 성장률(CAGR) 12.78%를 나타낼 것으로 예측됩니다. 이 필름은 평평한 패널이 많고 높은 밀착성이 크게 요구되지 않는 상용 차량 플리트나 부분 래핑 작업에 최적입니다. 차량 함대 운영자가 제한된 예산 내에서 광범위한 래핑을 원할 경우, 이 필름의 낮은 재료비가 큰 장점이 됩니다. 개량된 가소제, 에어 릴리스형 접착제 및 구조화된 라이너 덕분에 기존 제품에 비해 취급 편의성과 내구성이 향상되었습니다. 이러한 변화로 인해, 이전에는 캐스트 필름에 대한 의존도가 높았던 중간 정도의 곡면에서도 캘린더 성형 필름의 사용 범위가 확대되고 있습니다. 윈도우 필름은 단열, 자외선 차단, 사생활 보호와 같은 명확한 기능을 수행하는 한편, 특수 필름은 크롬 느낌, 텍스처, 카본 파이버 느낌, 컬러 시프트 마감 등을 제공합니다. ORAFOL사는 2025년에 ORACAL 970RA 시리즈의 색상 유형을 139가지로 확대했는데, 이는 프리미엄 특수 용도 분야에서 색상 선택의 폭이 여전히 중요하게 여겨지고 있음을 반영합니다.
지역별 분석
아시아태평양은 2025년 자동차 래핑 시장의 32.56%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 13.82%를 나타낼 것으로 예측됩니다. 중국의 신에너지차 보유 대수는 2026년 1분기에 3,500만 대를 넘어섰으며, 이로 인해 프리미엄 래핑 및 보호 제품에 대한 수요가 뒷받침되고 있습니다. 인도에서는 체계적인 디테일링 거점이 확대되고 있으며, 인도와 네팔 전역에서 125개 이상의 CarzSpa 스튜디오가 운영되고 있습니다. 일본과 한국에서는 높은 자동차 보유 밀도와 정밀한 시공에 대한 수요로 인해 프리미엄 용도가 뒷받침되고 있습니다. 아세안(ASEAN) 국가들에서는 자동차 보유 대수와 애프터마켓의 보급이 확대됨에 따라 추가적인 수요가 예상됩니다.
북미에는 성숙한 차량 커스터마이징 생태계가 확립되어 있습니다. 2024년 미국의 차량 개조 지출은 526억 5,000만 달러에 달하며, 외관 관련 제품은 애프터마켓의 주요 활동 중 하나가 되었습니다. 유럽에서는 독일, 영국, 프랑스, 북유럽 국가에서 수요가 견조하며, 이들 지역에서는 프리미엄 캐스트 필름과 인증 시공이 정착되어 있습니다. 남미에서는 브라질과 아르헨티나에서 수요가 확대되고 있으나, 경제 변동이 지출의 안정성에 영향을 미치고 있습니다. 플릿 브랜딩과 체계화된 자동차 서비스 체인이 이러한 시장의 기초적인 수요를 뒷받침하고 있습니다. 중동 및 아프리카에서는 걸프협력회의(GCC) 국가들의 고급차에 대한 고액 지출에 더해, 물류 및 운송 프로그램에서 수요도 증가하고 있습니다.
북미, 독일, 일본 등 디테일링 네트워크가 성숙한 시장에서는 차량 1대당 지출액이 높은 경향을 보입니다. 인도, 동남아시아, 브라질에서는 프랜차이즈 서비스 네트워크의 확장에 따라 판매 대수 증가세가 두드러집니다. 아시아태평양에서도 고급차 보유 대수와 전기차 보급이 확대됨에 따라, 고부가가치 캐스트 필름 및 열가소성 폴리우레탄(TPU) 필름으로의 전환이 진행되고 있습니다. 두바이, 리야드, 요하네스버그의 유통 파트너십 및 공인 시공업체 네트워크가 프리미엄 고객에 대한 접근을 뒷받침하고 있습니다. 북미 및 유럽은 평균 판매 가격, 시공업체의 기술력, 그리고 건당 매출액 측면에서 우위를 유지하고 있습니다. 이러한 요인들이 2031년까지 자동차 래핑 시장의 지속적인 지역적 확장을 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사의 전제조건과 시장의 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter의 Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 차량 유형별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 러시아
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- 3M
- A.P.A. S.p.A.
- Arlon Graphics, LLC
- Avery Dennison Corporation
- Eastman Chemical Company
- Fedrigoni S.P.A.
- Grafityp
- Guangzhou Carbins Film Co., Ltd.
- HEXIS S.A.S.
- JMR Graphics, Inc.
- KPMF
- Mactac
- ORAFOL Europe GmbH
- TeckWrap International
- The VViViD Shop
- XPEL
제7장 시장 기회와 향후 전망
LSH 26.10.29According to Mordor Intelligence, the automotive wrap market size was valued at USD 5.87 billion in 2025 and is estimated to grow from USD 6.50 billion in 2026 to reach USD 11.06 billion by 2031, at a CAGR of 11.22% during the forecast period (2026-2031).
Global Automotive Wrap Market Trends and Insights
Vehicle Customization and Aesthetic Personalization
Vehicle personalization has expanded beyond a narrow enthusiast audience as professional films have become more accessible to consumers. Buyers seek full-color changes and finishes such as matte, satin, chrome, and color-shifting options that conventional repainting cannot match with the same flexibility. U.S. specialty vehicle modification spending reached USD 52.65 billion in 2024, with vehicle appearance products forming a growing share of this aftermarket activity. The automotive wrap market benefits from this trend because an applied film can change a vehicle's appearance without permanently altering its factory finish. Some vehicle manufacturers are testing dealer-adjacent programs for factory-matched designs, creating a potential business-to-business channel alongside retail demand. These programs also raise performance expectations for installers and films across the automotive wrap market.
Fleet Branding and Mobile Advertising
Wrapped vehicles in dense urban areas can generate 30,000 to 70,000 visual impressions each day, depending on local traffic conditions. This visibility gives fleet operators a measurable reason to use vehicle graphics alongside other advertising formats. Logistics and e-commerce operators increasingly view vehicle branding as a practical part of their operating model. Replacement cycles of 3 to 5 years provide film suppliers and installers with recurring orders rather than one-time retail work. Last-mile delivery, ride-hailing, and food-delivery fleets expand the addressable base for the automotive wrap market in Asia-Pacific and Europe. Partial wraps also lower the entry cost for smaller operators by covering key identification and branding areas.
High Installation Cost and Skilled-Labor Dependency
A professional full-vehicle wrap requires 14 to 28 labor hours, depending on vehicle size and body complexity. Master installer hourly rates in high-demand North American locations have reached USD 95, increasing the cost of premium installations. The United States has no federally mandated installer certification standard, which contributes to uneven application quality. Buyers may delay purchases when qualified installers are not available in their area. Manufacturer and association training programs help develop technicians, including professional development work supported by the Specialty Equipment Market Association (SEMA). However, limited training capacity continues to constrain growth in the automotive wrap market in smaller cities across North America, Europe, and Asia-Pacific.
Other drivers and restraints analyzed in the detailed report include:
- Paint Preservation and Reversible Vehicle Modification
- Expansion of Automotive Aftermarket and Detailing Networks
- Film Performance Degradation Under Severe Climate Exposure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cast films accounted for 55.13% of the automotive wrap market share in 2025. Their manufacturing process produces low internal stress, allowing the film to conform to compound curves, deep channels, and riveted surfaces. These characteristics make cast films suitable for full-vehicle applications where finish quality and edge stability are important. 3M provides vehicle wrap films designed for demanding applications, supporting professional installers' preference for premium film systems. Cast films remain the reference product for difficult three-dimensional surfaces, which contributes significantly to their revenue within the automotive wrap market.
Calendered films are forecast to grow at a 12.78% CAGR through 2031. They are well-suited to commercial fleet and partial-wrap work, where flat panels reduce the need for high conformability. Their lower material cost is relevant when fleet operators seek broad coverage within controlled budgets. Improved plasticizers, air-release adhesives, and structured liners are improving handling and durability compared with earlier products. These changes expand the use of calendered film on moderate curves that previously relied more heavily on cast films. Window films serve distinct functions through heat rejection, ultraviolet attenuation, and privacy, while specialty films offer chrome, textured, carbon-fiber-effect, and color-shifting finishes. ORAFOL expanded its ORACAL 970RA range to 139 color variants in 2025, reflecting the continued importance of color choice in premium specialty applications.
Complete Report Scope:
- By Product Type
- Cast Films
- Calendared Films
- Window Films
- Other Product Types
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Trucks
- Buses
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 32.56% of the automotive wrap market share in 2025 and is forecast to grow at a 13.82% CAGR through 2031. New energy vehicle ownership in China exceeded 35 million units in the first quarter of 2026, thereby supporting demand for premium wrap and protection products. India is expanding its organized detailing base, with more than 125 CarzSpa studios operating across India and Nepal. Japan and South Korea support premium applications through high vehicle ownership density and demand for precise installation. ASEAN countries contribute additional units as vehicle ownership and aftermarket adoption expand.
North America has a mature vehicle customization ecosystem. U.S. vehicle modification spending reached USD 52.65 billion in 2024, with appearance products among the key aftermarket activities. Europe has strong demand in Germany, the United Kingdom, France, and the Nordic countries, where premium cast films and certified installation are well established. South America shows growing demand in Brazil and Argentina, although economic volatility affects spending consistency. Fleet branding and organized automotive service chains support baseline demand in these markets. The Middle East and Africa combine high spending on luxury vehicles in Gulf Cooperation Council markets with growing demand from logistics and transport programs.
Markets with mature detailing networks, including North America, Germany, and Japan, tend to support higher per-vehicle spending. India, Southeast Asia, and Brazil offer stronger unit growth as franchise service networks expand. Asia-Pacific is also shifting toward higher-value cast and thermoplastic polyurethane (TPU) films as premium vehicle ownership and electric vehicle adoption increase. Distribution partnerships and authorized installer networks in Dubai, Riyadh, and Johannesburg support access to premium customers. North America and Europe retain advantages in average selling prices, installer sophistication, and revenue per installation. These factors support continued geographic expansion of the automotive wrap market through 2031.
- 3M
- A.P.A. S.p.A.
- Arlon Graphics, LLC
- Avery Dennison Corporation
- Eastman Chemical Company
- Fedrigoni S.P.A.
- Grafityp
- Guangzhou Carbins Film Co., Ltd.
- HEXIS S.A.S.
- JMR Graphics, Inc.
- KPMF
- Mactac
- ORAFOL Europe GmbH
- TeckWrap International
- The VViViD Shop
- XPEL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Vehicle Customization and Aesthetic Personalization
- 4.2.2 Fleet Branding and Mobile Advertising
- 4.2.3 Paint Preservation and Reversible Vehicle Modification
- 4.2.4 Expansion of Automotive Aftermarket and Detailing Networks
- 4.2.5 Increasing Adoption of Electric and Premium Vehicles
- 4.3 Market Restraints
- 4.3.1 High Installation Cost and Skilled-Labor Dependency
- 4.3.2 Film Performance Degradation Under Severe Climate Exposure
- 4.3.3 PVC, Adhesive, and End-of-Life Recycling Constraints
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Cast Films
- 5.1.2 Calendared Films
- 5.1.3 Window Films
- 5.1.4 Other Product Types
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Trucks
- 5.2.4 Buses
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 ASEAN Countries
- 5.3.1.6 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 NORDIC Countries
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 3M
- 6.4.2 A.P.A. S.p.A.
- 6.4.3 Arlon Graphics, LLC
- 6.4.4 Avery Dennison Corporation
- 6.4.5 Eastman Chemical Company
- 6.4.6 Fedrigoni S.P.A.
- 6.4.7 Grafityp
- 6.4.8 Guangzhou Carbins Film Co., Ltd.
- 6.4.9 HEXIS S.A.S.
- 6.4.10 JMR Graphics, Inc.
- 6.4.11 KPMF
- 6.4.12 Mactac
- 6.4.13 ORAFOL Europe GmbH
- 6.4.14 TeckWrap International
- 6.4.15 The VViViD Shop
- 6.4.16 XPEL
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


