

|
시장보고서
상품코드
2155618
단조 합금 알루미늄 휠 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Forged Alloy Aluminum Wheel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
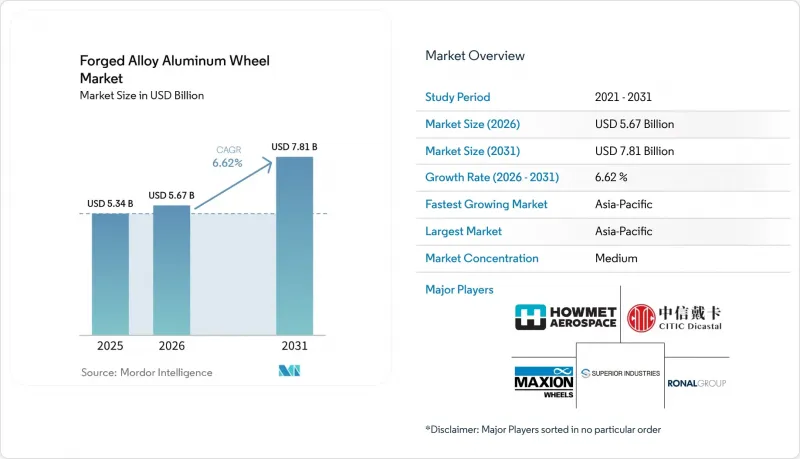
에 따르면 단조 합금 알루미늄 휠 시장 규모는 2025년에 53억 4,000만 달러로 추정되며, 2026년 56억 7,000만 달러에서 2031년까지 78억 1,000만 달러로 확대되어, 예측 기간(2026-2031년) 동안 CAGR은 6.62%에 달할 것으로 전망됩니다.
세계 단조 합금 알루미늄 휠 시장의 동향 및 인사이트
전기자동차(EV)의 경량화 및 비현가 중량 최적화
전기자동차(EV) 플랫폼의 등장으로 자동차 제조사들이 휠의 질량을 평가하는 방식이 바뀌었습니다. 배터리 팩은 차량 중량을 크게 증가시키기 때문에 회전 질량은 가속, 제동, 방향 전환 시 에너지 소비에 있어 중요한 요인이 되고 있습니다. 단조 휠의 구조는 정격 하중 용량을 유지하면서 더 얇은 단면과 최적화된 하중 경로를 실현합니다. 엔지니어들이 비현가 중량을 독립적인 조달 사양이 아닌 서스펜션 및 브레이크 시스템 설계의 일부로 다루게 되면, 단조 합금 알루미늄 휠 시장은 그 혜택을 누리게 될 것입니다. 이러한 접근 방식을 통해 휠 선정이 차량 개발 과정의 더 이른 단계에서 이루어지게 되어, 인증 공급업체의 역할이 강화될 것입니다. 또한 경량 휠에 관한 연구에 따르면, 차량의 경량화는 전력 소비 감소 및 주행 거리 향상으로 이어지는 것으로 나타났습니다.
프리미엄 차량 및 고성능 양산차
프리미엄 차량에서는 핸들링, 디자인, 브랜드 포지셔닝을 강화하기 위해 단조 휠이 채택되고 있습니다. 페라리는 2025년에 1만 3,640대를 납품했으나, 모델 체인지 기간 중에도 생산 대수는 보합세를 보였습니다. 단조 합금 알루미늄 휠 시장의 이 부문은 플릿용이나 주류 전기자동차 용도와는 다른 수요 패턴을 보이고 있습니다. 고성능 차량에 휠을 장착하는 것은 차량의 수명주기 전반에 걸쳐 교체 및 커스터마이징에 대한 수요를 뒷받침하는 결과로 이어집니다. 순정 사양과 애프터마켓 수요의 관계로 인해, 공급업체와의 파트너십은 초기 생산 프로그램을 넘어서는 가치를 지닙니다. 이 채널은 단순히 높은 생산량뿐만 아니라 제품 엔지니어링과 확립된 브랜드 인지도에 의존하고 있습니다.
높은 단조·기계 가공·금형 비용
단조에는 전용 프레스 설비, 휠 전용 금형 및 기계 가공 공정이 필요하며, 이로 인해 저비용 주조 휠에 비해 비용이 높아집니다. 이러한 비용 구조는 가격에 민감한 차량 플랫폼에서의 채택을 제한할 가능성이 있습니다. 또한, 공급업체는 생산 프로그램 기간 동안 금형 비용을 회수하기 위해 충분한 생산량을 확보해야 하므로, 휠 직경, 볼트 패턴, 지역별 사양의 빈번한 변경에 대응하기 어려워집니다. 단조 합금 알루미늄 휠 시장은 성능, 하중 지지 능력, 또는 차량의 포지셔닝이 높은 제조 비용을 정당화할 수 있는 용도에서 여전히 가장 적합합니다.
부문 분석
2025년, 승용차는 단조 알루미늄 휠 시장 점유율의 71.78%를 차지했습니다. 이러한 위상은 승용차의 거대한 세계 생산 기반 규모와 프리미엄 차량 및 전기자동차 모델에서 단조 휠이 확고하게 자리 잡은 사용 현황을 반영합니다. OEM의 사양 결정 주기에 따라 차량이 생산에 들어가기 훨씬 전에 휠 선정이 확정되기 때문에 상용차 수주가 변동하더라도 승용차 수요는 유지되고 있습니다. 또한 승용차 용도에서는 스타일링, 승차감, 브레이크 클리어런스 및 에너지 효율 요건이 중시되며, 제조사가 구조적 성능을 저해하지 않으면서 휠의 질량을 줄이려고 할 때 단조 구조가 유리합니다. 승용차 부문은 생산량이 많고, 진행 중인 전동화 추세, 그리고 교체용 휠 수요를 견인하는 대규모의 기존 차량 기반을 바탕으로 단조 합금 알루미늄 휠 시장의 중심을 계속 차지하고 있습니다.
상용차 시장은 2031년까지 연평균 성장률(CAGR) 7.52%로 성장할 것으로 예측됩니다. 차량 운영 사업자들이 휠 무게와 적재 용량, 그리고 운영 효율성을 저울질하는 가운데, 상용차용 단조 합금 알루미늄 휠 시장은 확대되고 있습니다. 트럭 및 버스 구매자의 경우, 차축 제한이 유효 적재량에 영향을 미칠 때 휠 무게 감소를 고려해야 할 직접적인 동기가 있습니다. MAXION Wheels사는 2026년 1월 튀르키예 마니사 공장에서 트럭용 단조 알루미늄 휠의 양산을 시작했으며, 남미에서 개최된 ‘Lat. Bus 2026’에서 자사의 트럭용 단조 알루미늄 휠 제품군을 발표했습니다. 이러한 동향은 주요 공급업체들이 상용차를 생산능력에 대한 투자가 가치 있는 분야로 간주하고 있음을 보여줍니다. 이 부문의 성장은 차량 교체 주기, 고객의 경제성, 그리고 가혹한 운용 조건에 대응할 수 있는 적합한 제품의 가용성에 좌우됩니다.
지역별 분석
아시아태평양은 2025년 단조 합금 알루미늄 휠 시장 점유율의 49.05%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 7.35%로 성장할 것으로 예측됩니다. 중국은 전기자동차 공급망과 알루미늄 부품 제조를 통해 이 지역의 위상을 뒷받침하고 있습니다. 2025년 3월, CITIC Dicastal과 SAIC-GM-Wuling은 광시 좡족 자치구에 스마트 알루미늄 부품 제조 시스템을 구축하기로 합의하여, 휠 및 알루미늄 부품의 생산능력을 주요 자동차 제조 거점과 연계하게 되었습니다. 인도 역시 합금 휠 생산 환경이 확대되고 있습니다. 2026년 2월, Steel Strips Wheels는 구자라트주 부지에 연간 120만 개의 초기 생산능력을 갖춘 새로운 합금 휠 공장을 건설하기 위해 1,900만 달러 규모의 계약을 체결했습니다. 현지 인증 요건 및 연비 기준으로 인해 인도 자동차 시장에 진출하는 공급업체들의 진입 장벽이 높아지고 있습니다.
유럽과 북미는 단조 합금 알루미늄 휠 시장에서 두 번째로 중요한 수요 거점으로 자리 잡고 있습니다. 유럽에서는 고급차 생산이 성능을 중시하는 휠에 대한 수요를 뒷받침하고 있는 반면, 두 지역 모두에서 차량 함대의 연비 효율 요건으로 인해 경량 트럭 및 버스용 휠에 대한 관심이 높아지고 있습니다. 2026년 4월, 하우메트 에어로스페이스(Haumet Aerospace)는 헝가리 세케슈페헤르바르에 위치한 하우메트 코펨(Haumet Kofem) 공장의 휠 생산능력을 확대하여, 대형 트럭 및 버스에 사용되는 ‘듀라브라이트(Dura-Bright)’ 휠의 유럽 시장용 생산능력을 증강했습니다. 볼베트(Volvet) 역시 유럽 휠 시장에서 생산 유연성과 친환경 알루미늄 이니셔티브를 중시하고 있습니다. 북미에서는 각 공급업체들이 계속해서 차량 프로그램의 조달 결정과 차량 함대의 운영 상황에 주목하고 있습니다.
남미에서는 상용차 차량군(fleet)에의 채택을 통해 단조 합금 알루미늄 휠 시장의 중요성이 높아지고 있습니다. MAXION Wheels사는 브라질 상파울루에서 개최된 ‘Lat.Bus 2026’에서 해당 지역용 단조 알루미늄 트럭용 휠을 발표하고, 상용차의 초기 목표 시장으로 브라질과 아르헨티나를 선정했습니다. 중동 및 아프리카는 규모는 작지만 성장세가 두드러지는 시장이며, 일부 국가에서는 고급차 수입이 애프터마켓 수요를 뒷받침하고 있습니다. 이 지역의 주요 시장은 사우디아라비아와 남아프리카공화국입니다. 규제 당국 및 세관 당국의 제품 감시가 강화되는 가운데, 인증 요건이 휠 수입의 선별 기준으로 부상하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 차종별
- 제품 구성별
- 최종 이용 산업별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- Accuride Corporation
- BORBET GmbH
- CITIC Dicastal Co., Ltd.
- Enkei International, Inc.
- Howmet Aerospace
- HRE Wheels
- KW automotive GmbH
- MAXION Wheels
- O.Z. S.p.A.
- RAYS, CO.LTD
- RONAL GROUP
- Steel Strips Wheels Limited
- Superior Industries International, Inc.
- TOPY INDUSTRIES LIMITED
- Zhejiang Wanfeng Auto Wheel Co., Ltd.
제7장 시장 기회와 향후 전망
KSM 26.10.30According to Mordor Intelligence, the forged alloy aluminum wheel market size was estimated at USD 5.34 billion in 2025 and is estimated to grow from USD 5.67 billion in 2026 to USD 7.81 billion by 2031, at a CAGR of 6.62% during the forecast period (2026-2031).
Global Forged Alloy Aluminum Wheel Market Trends and Insights
EV Lightweighting and Unsprung-Mass Optimization
Electric vehicle platforms have changed how vehicle manufacturers assess wheel mass. Battery packs add substantial vehicle weight, making rotating mass a key factor in energy consumption during acceleration, braking, and directional changes. Forged-wheel construction supports thinner sections and optimized load paths while retaining rated load capacity. The forged alloy aluminum wheel market benefits when engineers treat unsprung mass as part of suspension and brake-system design rather than as a separate purchasing specification. This approach moves wheel selection earlier into the vehicle development process and strengthens the role of approved suppliers. Lightweight wheel research also links vehicle mass reduction with lower electricity consumption and improved driving range.
Premium Vehicle and High-Performance Production
Premium vehicles use forged wheels to support handling, design, and brand positioning. Ferrari delivered 13,640 vehicles in 2025, with output held flat during its model changeover. This segment of the forged aluminum alloy wheel market exhibits a different demand pattern from that of fleet and mainstream electric vehicle applications. Wheel fitment on high-performance vehicles can also support demand for replacement and customization over the vehicle life cycle. The relationship between original equipment fitment and aftermarket demand makes supplier partnerships valuable beyond the initial production program. This channel relies on product engineering and established brand recognition rather than high production output alone.
High Forging, Machining, and Tooling Cost
Forging requires dedicated press capacity, wheel-specific tooling, and machining operations, which create a cost premium over lower-cost cast-wheel alternatives. This cost structure can limit adoption on price-sensitive vehicle platforms. Suppliers must also secure sufficient output to recoup tooling costs over the duration of a production program, making frequent changes in wheel diameter, bolt pattern, and regional variants harder to support. The forged alloy aluminum wheel market remains most suitable for applications where performance, load capacity, or vehicle positioning justifies the higher manufacturing cost.
Other drivers and restraints analyzed in the detailed report include:
- OEM Adoption for Large-Diameter and High-Load Platforms
- Aftermarket Customization and Digital Distribution
- Aluminum, Energy, and Alloy-Input Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Passenger vehicles held 71.78% of the forged alloy aluminum wheel market share in 2025. Their position reflects the large global production base for passenger cars and the established use of forged wheels on premium and electric vehicle models. Original equipment specification cycles lock in wheel choices well before a vehicle enters production, supporting passenger-vehicle demand even when commercial-vehicle orders fluctuate. Passenger vehicle applications also emphasize styling, ride quality, brake clearance, and energy-efficiency requirements that favor forged construction when manufacturers seek to reduce wheel mass without compromising structural performance. The passenger vehicle category remains central to the forged alloy aluminum wheel market, with higher production volumes, ongoing electrification trends, and a large installed base driving demand for replacement wheels.
Commercial vehicles are forecast to grow at a CAGR of 7.52% through 2031. The forged alloy aluminum wheel market for commercial vehicles is expanding as fleet operators weigh wheel weight against payload capacity and operating efficiency. Truck and bus buyers have a direct incentive to evaluate lower wheel weight where axle limits affect usable payload. MAXION Wheels began serial production of forged aluminum truck wheels in January 2026 at its Manisa, Turkiye facility, and introduced its forged aluminum truck wheel portfolio in South America at Lat. Bus 2026. These developments indicate that established suppliers view commercial vehicles as an area warranting investment in capacity. Segment growth depends on fleet replacement cycles, customer economics, and the availability of qualified products for demanding operating conditions.
Complete Report Scope:
- By Vehicle Type
- Passenger Vehicles
- Commercial Vehicles
- By Product Configuration
- One-Piece Wheels
- Multi-Piece Wheels
- By End-User Industry
- OEM
- Aftermarket
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 49.05% of the forged alloy aluminum wheel market share in 2025 and is forecast to grow at a CAGR of 7.35% through 2031. China supports the regional position through its electric-vehicle supply chains and aluminum-component manufacturing. In March 2025, CITIC Dicastal and SAIC-GM-Wuling agreed to build an intelligent aluminum parts manufacturing system in Guangxi, connecting wheel and aluminum-component capabilities to a major vehicle manufacturing base. India also offers a growing production environment for alloy wheels. In February 2026, Steel Strips Wheels signed a USD 19 million agreement to build a new alloy-wheel facility in Bhuj, Gujarat, with an initial capacity of 1.2 million wheels per year. Local certification and fuel-efficiency requirements raise the entry threshold for suppliers serving the Indian vehicle market.
Europe and North America form the second major demand cluster for the forged alloy aluminum wheel market. Premium vehicle production supports demand for performance-oriented fitments in Europe, while fleet efficiency requirements drive interest in lower-weight truck and bus wheels across both regions. In April 2026, Howmet Aerospace expanded wheel production capacity at its Howmet-Kofem facility in Szekesfehervar, Hungary, adding European capacity for Dura-Bright wheels used on heavy-duty trucks and buses. BORBET also emphasizes production flexibility and green aluminum credentials in the European wheel market. In North America, suppliers remain attentive to vehicle program sourcing decisions and fleet operating conditions.
South America is gaining relevance in the forged alloy aluminum wheel market through commercial fleet applications. MAXION Wheels introduced forged aluminum truck wheels for the region at Lat.Bus 2026 in Sao Paulo, Brazil, with Brazil and Argentina identified as the initial target markets for commercial vehicles. The Middle East and Africa represent a smaller but growing base, where premium vehicle imports support aftermarket demand in select countries. Saudi Arabia and South Africa are the primary markets in the region. Certification requirements are emerging as a filter for wheel imports as regulators and customs authorities increase product oversight.
- Accuride Corporation
- BORBET GmbH
- CITIC Dicastal Co., Ltd.
- Enkei International, Inc.
- Howmet Aerospace
- HRE Wheels
- KW automotive GmbH
- MAXION Wheels
- O.Z. S.p.A.
- RAYS,CO.LTD
- RONAL GROUP
- Steel Strips Wheels Limited
- Superior Industries International, Inc.
- TOPY INDUSTRIES LIMITED
- Zhejiang Wanfeng Auto Wheel Co., Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV Lightweighting and Unsprung-Mass Optimization
- 4.2.2 Fleet Efficiency and Emissions Compliance
- 4.2.3 Premium Vehicle and High-Performance Production
- 4.2.4 OEM Forged-Wheel Adoption for Large-Diameter and High-Load Platforms
- 4.2.5 Forged-Wheel E-Commerce and Customization-Led Aftermarket Expansion
- 4.3 Market Restraints
- 4.3.1 High Forging, Machining, and Tooling Cost
- 4.3.2 Aluminum, Energy, and Alloy-Input Price Volatility
- 4.3.3 Forged-Wheel Fitment, Load-Rating, and Counterfeit-Compliance Risk
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Rivalry Among Existing Competitors
5 Market Size and Growth Forecasts (Value)
- 5.1 By Vehicle Type
- 5.1.1 Passenger Vehicles
- 5.1.2 Commercial Vehicles
- 5.2 By Product Configuration
- 5.2.1 One-Piece Wheels
- 5.2.2 Multi-Piece Wheels
- 5.3 By End-User Industry
- 5.3.1 OEM
- 5.3.2 Aftermarket
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 NORDIC Countries
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Accuride Corporation
- 6.4.2 BORBET GmbH
- 6.4.3 CITIC Dicastal Co., Ltd.
- 6.4.4 Enkei International, Inc.
- 6.4.5 Howmet Aerospace
- 6.4.6 HRE Wheels
- 6.4.7 KW automotive GmbH
- 6.4.8 MAXION Wheels
- 6.4.9 O.Z. S.p.A.
- 6.4.10 RAYS,CO.LTD
- 6.4.11 RONAL GROUP
- 6.4.12 Steel Strips Wheels Limited
- 6.4.13 Superior Industries International, Inc.
- 6.4.14 TOPY INDUSTRIES LIMITED
- 6.4.15 Zhejiang Wanfeng Auto Wheel Co., Ltd.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


