

|
시장보고서
상품코드
2155672
오픈 네트워크 테스트 및 인증 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Open Network Testing and Certification - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
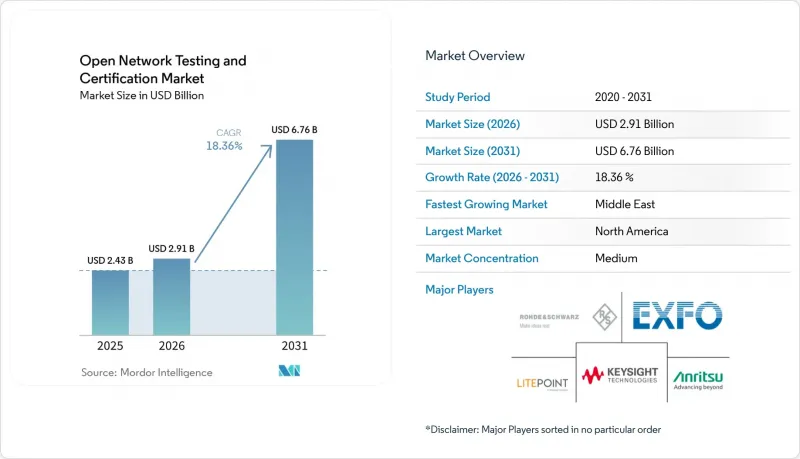
에 따르면 오픈 네트워크 테스트 및 인증 시장 규모는 2025년 24억 3,000만 달러에서 2026년에는 29억 1,000만 달러로 확대되어 2031년까지 67억 6,000만 달러에 달할 것으로 예측되며, 2026년부터 2031년까지 연평균 성장률(CAGR)은 18.36%가 될 전망입니다.
세계 오픈 네트워크 테스트 및 인증 시장의 동향과 인사이트
O-RAN의 표준화 및 인증 도입
O-RAN 인증 및 배지 프로그램은 적합성 인증서, 상호운용성 배지, 엔드투엔드 배지를 활용하여 ‘한 번 테스트하고 여러 번 배포’하는 워크플로우를 지원합니다. 이러한 구조를 통해 다중 벤더 조달 결정 시 공식 인증의 중요성이 높아지고 있습니다. 일본 OTIC는 2026년 1월, 라쿠텐 심포니에 적합성 인증 및 상호운용성 배지를 수여함으로써, 해당 기업에 대한 3가지 인증 클래스를 모두 완료했습니다. 인증의 반복을 통해, 고립된 실험실 활동이 각 실험실이 벤더 프로그램을 넘나들며 제공할 수 있는 재현 가능한 서비스로 변화하고 있습니다. ETSI는 2026년 2월, 공개 사양(PAS) 절차를 통해 O-RAN R1 인터페이스 시험 사양을 공식적으로 제정했습니다. 이러한 시험 요건이 유럽의 조달 및 기술 심사 절차에 통합됨에 따라, 개방형 네트워크 시험·인증 시장에서 규정 준수에 대한 보다 명확한 기준이 확립되고 있습니다.
5G 및 5G Advanced 네트워크의 확장
5G 구축에는 주파수 대역 인증부터 무선 적합성, 프론트홀 타이밍, 기능 테스트에 이르기까지 광범위한 검증이 필요합니다. 5G Advanced에서는 캐리어 애그리게이션, 매시브 MIMO 빔포밍, AI를 활용한 RAN 제어가 검증 작업에 추가됩니다. O-RAN 얼라이언스가 2026년 봄에 개최한 세계 플러그페스트에서는 다중 벤더에 의한 매시브 MIMO 통합 및 무선 기반 테스트가 진행되었습니다. Digital Catapult의 보고에 따르면, 참가자들은 영국에서 최초로 엔드투엔드 매시브 MIMO 테스트를 완료했습니다. 이러한 활동은 빔포밍 검증 작업이 실험실 연구 단계를 넘어 공식적인 상호운용성 프로그램으로 전환되었음을 보여줍니다. 통신 사업자들이 무선 성능과 AI 기반 네트워크 기능 모두에 대한 테스트를 필요로함에 따라, 오픈 네트워크 테스트 및 인증 시장이 그 혜택을 누리고 있습니다.
고급 테스트 및 계측 인프라의 높은 비용
캐리어급 O-RU 테스트 장비에는 신호 발생기, 스펙트럼 분석기, 에뮬레이터, 그리고 대부분의 경우 RF 차폐가 적용된 무선 통신 시험실이 필요합니다. 이러한 자산에는 시설당 수백만 달러의 투자가 필요할 수 있습니다. 미국 국립통신정보국(NTIA)은 2025년에 3개의 상용 Open RAN 시스템을 CRAIN 연구소에 통합했습니다. 이러한 노력을 통해 멀티 벤더 환경을 구축할 때 발생하는 구성 및 하드웨어 의존성이 명확해졌습니다. 이러한 비용 구조는 광범위한 계측 장비 포트폴리오와 표준 릴리스를 따라잡을 수 있는 자원을 보유한 벤더에게 유리하게 작용합니다. 또한, Lab-as-a-Service(LaaS) 시설에 대한 접근이 여전히 제한적인 남미와 아프리카에서는 현지 테스트 역량이 제한되는 결과로 이어집니다.
부문 분석
2025년 시점에서 테스트용 하드웨어는 전체 제공 부문의 44.28%를 차지했습니다. 물리적 RF 검증에는 여전히 캐리어급 신호 발생기, O-RU 적합성 시험 장비 및 스펙트럼 분석기가 필요합니다. 대규모 MIMO의 빔 패턴이나 S-플레인의 타이밍 허용 오차 점검에 있어서는 소프트웨어 기반 에뮬레이션으로는 이러한 도구를 대체할 수 없습니다. 로데 슈바르츠와 VIAVI는 VVDN Technologies의 실내용 O-RU에 대한 유럽 최초의 O-RAN 적합성 인증 과정에서 베를린의 i14y Lab을 지원했습니다. 두 회사는 R&S SMW200A 신호 발생기와 VIAVI TM500 O-RU 테스터를 함께 사용했습니다. 이 사례는 계측기의 품질과 소프트웨어 통합이 오픈 네트워크 테스트 및 인증 시장에서 여전히 핵심적인 역할을 하고 있는 이유를 보여줍니다.
프로페셔널 서비스 시장은 2026년부터 2031년까지 연평균 성장률(CAGR) 19.28%로 성장할 것으로 예측됩니다. 숙련된 Open RAN 테스트 엔지니어의 부족으로 인해 통신 사업자들은 매니지드 프로그램의 활용을 점점 더 늘리고 있습니다. 오픈 네트워크 테스트 및 인증 시장에서 테스트 소프트웨어는 전체 하드웨어 계층에 걸친 자동화, 오케스트레이션 및 분석 기능을 제공합니다. 새로운 O-RAN 사양이 발표될 때마다 테스트 케이스가 추가되어 지속적인 소프트웨어 업데이트가 필요합니다. Telecom Infra Project는 분산형 5G NR 스몰셀의 검증을 지원하기 위해 2025년에 ‘스몰셀 엔드투엔드 테스트 계획 버전 2’를 발표했습니다. 이 규격의 확장은 하드웨어, 소프트웨어 및 이를 연결하는 오픈 네트워크 테스트·인증 업계의 서비스를 지원하기 위한 것입니다.
2025년, 5G 네트워크 구축은 애플리케이션 수준 점유율의 48.52%를 차지했습니다. 통신 사업자는 사이트 가동을 시작하기 전에 무선 장치의 인증, 프론트홀 타이밍 검증 및 보안 보증을 완료해야 합니다. 이러한 활동으로 인해 구축 테스트는 오픈 네트워크 테스트 및 인증 시장 전체에서 수요의 핵심이 되고 있습니다. 프로젝트가 시범 운영에서 상용 구축으로 전환됨에 따라 Open RAN 통합 테스트는 독립적인 예산 항목으로 자리 잡고 있습니다. 디지털 트윈 플랫폼은 실제 배포 전에 동작 분석을 지원하고 잠재적인 장애 요인을 파악하는 데 활용되고 있습니다. 이러한 노력으로 인해 물리적 및 가상 네트워크 구성요소 전반에 걸친 협업 테스트의 필요성이 높아지고 있습니다.
클라우드 RAN 테스트는 2026년부터 2031년까지 연평균 성장률(CAGR) 20.34%로 성장할 것으로 예측됩니다. 통신 사업자가 컨테이너화된 RAN으로 전환함에 따라, 쿠버네티스(Kubernetes) 검증, 인프라 벤치마킹, 분산 컴퓨팅 동작 테스트에 대한 요구 사항이 대두되고 있습니다. 이러한 노력은 성능이 소프트웨어와 기반 컴퓨팅 환경 모두에 의존한다는 점에서 기존의 무선 적합성 테스트와는 다릅니다. 4G 네트워크 현대화는 통신 사업자가 O-RAN 준수 O-eNB 장비를 사용하여 레거시 시스템을 갱신하는 상황에서 여전히 중요한 위치를 차지하고 있습니다. 오픈 네트워크 테스트 및 인증 시장에서 통신 장비 검증은 장비가 현장에 도입되기 전 공급망의 적합성 평가도 지원하고 있습니다.
지역별 분석
2025년, 북미는 지역 점유율의 37.24%를 차지했습니다. 이 지역에는 OTIC 인증을 받은 시험소와 경험이 풍부한 테스트 엔지니어가 밀집해 있으며, 오픈 무선 시스템에 대한 연방 정부의 지원도 받고 있습니다. NTIA는 2025년, 3개의 상용 Open RAN 시스템을 CRAIN 연구소에 통합했습니다. 이 노력을 통해 다중 벤더 간의 통합 결과가 공개되었으며, 캐리어급 구성에 요구되는 기술적 요건이 명확해졌습니다. 키사이트는 2025년 10월, 11억 6,000만 파운드(14억 6,000만 달러)에 스피렌트의 인수를 완료했습니다. 이 거래를 통해 설계 에뮬레이션, 적합성 테스트, 코어 네트워크 시뮬레이션, 실제 네트워크의 서비스 보증 및 관련 자동화 워크플로 기능이 통합되었습니다.
아시아태평양은 일본의 인증 생태계, 한국의 ‘5G Advanced’ 계획, 그리고 인도, 중국, 동남아시아 전역에 걸친 광범위한 활동으로 인해 주요 수요 거점이 되고 있습니다. 일본의 OTIC는 2025년, NEC의 무선 유닛 ‘MB5420’에 대해 2개의 상호운용성 배지를 발급했습니다. NTT 동일본은 2026년 3월, 프라이빗 5G 환경에서 일본 최초로 공개된 멀티 벤더 RIC 연결성 테스트 결과를 발표했습니다. 유럽에는 베를린, 토리노, 마드리드, 파리에 4개의 인증 OTIC가 있습니다. 베를린에서 개최된 xG-ALOE 플러그페스트에서는 타이밍에 민감한 네트워크, 센싱, 보안 각 분야에 걸친 Open RAN 구성요소 테스트가 진행되었습니다.
중동 지역은 2026년부터 2031년까지 연평균 성장률(CAGR) 20.14%로 확대될 것으로 예측됩니다. GCC(걸프협력회의) 회원국의 통신 사업자들은 상용 Open RAN 도입을 추진하고 있으며, 적합성, 타이밍, 보안 검증에 대한 수요를 창출하고 있습니다. 자인 쿠웨이트와 패러렐 와이어리스는 2025년 2월 5G 독립형(SA) Open RAN 개념 증명(PoC)을 완료했으며, 다운로드 속도는 1.3 Gbps를 넘어섰습니다. 사우디아라비아의 TAWAL과 노키아는 2025년에 멀티테넌트형 Open RAN 엣지 클라우드 플랫폼의 실증 실험을 진행했습니다. 현지 OTIC(통신 인프라 테스트) 역량이 제한적이어서 이 지역에서는 전문 시설에 대한 수요가 발생하고 있습니다. 남미 및 아프리카는 높은 인프라 비용과 엔지니어링 역량 부족으로 인해 현지 테스트가 제약을 받고 있어, 여전히 초기 단계의 시장에 머물러 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
- 조사 가정과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
- 시장 개요
- 거시경제 요인이 시장에 미치는 영향
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 업계 밸류체인 분석
- 규제 상황
- 기술 전망
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제공별
- 용도별
- 최종사용자별
- 전개 모델별
- 네트워크 아키텍처별
- 서비스 유형별
- 지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 스페인
- 러시아
- 기타 유럽 국가
- 아시아태평양
- 중국
- 일본
- 인도
- 한국
- 동남아시아
- 기타 아시아태평양 국가
- 중동
- 사우디아라비아
- 아랍에미리트
- 튀르키예
- 기타 중동 국가
- 아프리카
- 남아프리카공화국
- 나이지리아
- 기타 아프리카 국가
- 북미
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율 분석
- 기업 개요
- Keysight Technologies, Inc.
- Rohde & Schwarz GmbH & Co. KG
- Anritsu Corporation
- EXFO Inc.
- LitePoint Corporation
- Artiza Networks, Inc.
- Teledyne LeCroy, Inc.
- Tektronix, Inc.
- National Instruments Corporation
- Averna Technologies Inc.
- Bird Technologies, Inc.
- CommScope, Inc.
- Radisys Corporation
- VeEX Inc.
- Calnex Solutions plc
- PCTEL, Inc.
제7장 시장 기회와 향후 전망
KSMAccording to Mordor Intelligence, the open network testing and certification market size is projected to expand from USD 2.43 billion in 2025 to USD 2.91 billion in 2026, and to USD 6.76 billion by 2031, registering a CAGR of 18.36% between 2026 and 2031.
Global Open Network Testing and Certification Market Trends and Insights
O-RAN Standardization and Certification Adoption
The O-RAN Certification and Badging Program uses conformance certificates, interoperability badges, and end-to-end badges to support test-once, deploy-many workflows. This structure is making formal credentials more important in multi-vendor procurement decisions. Japan OTIC awarded Rakuten Symphony conformance certification and an interoperability badge in January 2026, completing all 3 credential classes for the vendor. Repeated credentialing turns isolated lab activity into a repeatable service that laboratories can offer across vendor programs. ETSI formalized the O-RAN R1 interface test specification through its Publicly Available Specification process in February 2026. The open network testing and certification market gains a clearer basis for compliance as those test requirements enter European procurement and technical review processes.
5G and 5G Advanced Network Expansion
5G rollouts require validation from spectrum qualification through radio conformance, fronthaul timing, and feature testing. 5G Advanced adds carrier aggregation, massive MIMO beamforming, and AI-enabled RAN control to the validation workload. The O-RAN Alliance Spring 2026 Global PlugFest included multi-vendor massive MIMO integration and over-the-air testing. Digital Catapult reported that participants completed end-to-end massive MIMO testing at the United Kingdom's first. These activities show that beamforming validation has moved beyond laboratory research into formal interoperability programs. The open network testing and certification market benefits as operators require testing for both radio performance and AI-based network functions.
High Cost of Advanced Test and Measurement Infrastructure
Carrier-grade O-RU test rigs require signal generators, spectrum analyzers, emulators, and often RF-shielded over-the-air chambers. These assets can require several million dollars of investment for a single facility. The U.S. National Telecommunications and Information Administration integrated 3 commercial Open RAN systems into its CRAIN laboratory in 2025. Its work showed the configuration and hardware dependencies involved in establishing a multi-vendor environment. This cost favors vendors with broad instrument portfolios and resources to keep pace with standards releases. It also limits local testing capacity in South America and Africa, where access to Lab-as-a-Service facilities remains constrained.
Other drivers and restraints analyzed in the detailed report include:
- Multi-Vendor Interoperability Risk
- Cloud-Native and Virtualized RAN Validation Demand
- Multi-Domain Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Testing Hardware held 44.28% of the offering segment in 2025. Physical RF validation still requires carrier-grade signal generators, O-RU conformance rigs, and spectrum analyzers. Software emulation cannot replace those tools for massive MIMO beam patterns or S-plane timing tolerance checks. Rohde and Schwarz and VIAVI supported the Berlin i14y Lab in its first European O-RAN conformance certification for an indoor O-RU from VVDN Technologies. Their approach paired the R and S SMW200A signal generator with the VIAVI TM500 O-RU Tester. This example shows why instrument quality and software integration remain central to the open network testing and certification market.
Professional Services is projected to grow at a 19.28% CAGR from 2026 to 2031. Operators increasingly use managed programs because experienced Open RAN test engineers are scarce. In the open network testing and certification market, Testing Software provides automation, orchestration, and analytics across the hardware layer. Each new O-RAN specification release adds test cases and requires continuing software updates. The Telecom Infra Project released the Small Cell End-to-End Test Plan Version 2 in 2025 to support validation of disaggregated 5G NR small cells. This standard expansion supports hardware, software, and the open network testing and certification industry services that connect them.
5G Network Deployment accounted for 48.52% of the application-level share in 2025. Operators must qualify radio units, validate fronthaul timing, and complete security assurance before site activation. These activities make deployment testing the core source of demand across the open network testing and certification market. Open RAN Integration testing is becoming a separate budget area as projects move from trials to commercial deployments. Digital twin platforms are being used to support behavioral analysis and identify potential failure conditions before production deployment. This work expands the need for coordinated testing across physical and virtual network components.
Cloud RAN Testing is forecast to grow at a 20.34% CAGR from 2026 to 2031. Carrier migration to containerized RAN creates requirements for Kubernetes validation, infrastructure benchmarking, and distributed-compute behavioral testing. This work differs from conventional radio conformance because performance depends on both software and the underlying compute environment. 4G Network Modernization remains relevant where operators refresh legacy systems using O-RAN-compliant O-eNB equipment. Within the open network testing and certification market, Telecom Equipment Validation also supports supply-chain qualification before equipment reaches field deployment.
Complete Report Scope:
- By Offering
- Testing Hardware
- Testing Software
- Professional Services
- By Application
- 5G Network Deployment
- 4G Network Modernization
- Open RAN Integration
- Telecom Equipment Validation
- Cloud RAN Testing
- Other Applications
- By End User
- Telecom Network Operators
- Network Equipment Manufacturers
- System Integrators
- Certification Laboratories
- By Deployment Model
- Cloud-Based
- On-Premises
- Hybrid
- By Network Architecture
- Virtualized RAN
- Cloud RAN
- Disaggregated RAN
- By Service Type
- Managed Testing
- Consulting
- Integration
- Certification
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Southeast Asia
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 37.24% regional share in 2025. The region has a dense concentration of OTIC-qualified laboratories, experienced test engineers, and federal support for open wireless systems. NTIA integrated 3 commercial Open RAN systems into its CRAIN laboratory during 2025. The work produced public multi-vendor integration results and showed the technical demands of carrier-grade configurations. Keysight completed its acquisition of Spirent in October 2025 for GBP 1.16 billion (USD 1.46 billion). The transaction combined design emulation, conformance testing, core-network simulation, live-network service assurance, and related automated workflow capabilities.
Asia-Pacific is a major volume center because of Japan's certification ecosystem, South Korea's 5G Advanced plans, and wider activity across India, China, and Southeast Asia. Japan OTIC issued 2 interoperability badges to NEC's MB5420 radio unit in 2025. NTT EAST published Japan's first disclosed multi-vendor RIC connectivity test in a private 5G setting in March 2026. Europe has 4 qualified OTICs in Berlin, Turin, Madrid, and Paris. The Berlin xG-ALOE Plugfest tested Open RAN components across timing-sensitive networking, sensing, and security domains.
The Middle East is projected to expand at a 20.14% CAGR from 2026 to 2031. GCC operators are moving into commercial Open RAN deployments, creating demand for conformance, timing, and security validation. Zain Kuwait and Parallel Wireless completed a 5G standalone Open RAN proof of concept in February 2025 with download speeds exceeding 1.3 Gbps. Saudi Arabia's TAWAL and Nokia demonstrated a live multi-tenant Open RAN edge-cloud platform in 2025. Limited local OTIC capacity creates an opening for specialized facilities in the region. South America and Africa remain earlier-stage markets because high infrastructure costs and limited engineering capacity constrain local testing.
- Keysight Technologies, Inc.
- Rohde & Schwarz GmbH & Co. KG
- Anritsu Corporation
- EXFO Inc.
- LitePoint Corporation
- Artiza Networks, Inc.
- Teledyne LeCroy, Inc.
- Tektronix, Inc.
- National Instruments Corporation
- Averna Technologies Inc.
- Bird Technologies, Inc.
- CommScope, Inc.
- Radisys Corporation
- VeEX Inc.
- Calnex Solutions plc
- PCTEL, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 O-RAN Standardization and Certification Adoption
- 4.3.2 5G and 5G Advanced Network Expansion
- 4.3.3 Multi-Vendor Interoperability Risk
- 4.3.4 Cloud-Native and Virtualized RAN Validation Demand
- 4.3.5 Operator Demand for Vendor-Neutral Test Once and Deploy Many Workflows
- 4.3.6 AI-Assisted Continuous Testing and Digital Twin Simulation
- 4.4 Market Restraints
- 4.4.1 Multi-Domain Integration Complexity
- 4.4.2 High Cost of Advanced Test and Measurement Infrastructure
- 4.4.3 Evolving O-RAN Specifications and Test Case Volatility
- 4.4.4 Limited Availability of Specialized Open RAN Test Engineering Talent
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Competitive Rivalry
- 4.8.2 Threat of New Entrants
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Bargaining Power of Buyers
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Offering
- 5.1.1 Testing Hardware
- 5.1.2 Testing Software
- 5.1.3 Professional Services
- 5.2 By Application
- 5.2.1 5G Network Deployment
- 5.2.2 4G Network Modernization
- 5.2.3 Open RAN Integration
- 5.2.4 Telecom Equipment Validation
- 5.2.5 Cloud RAN Testing
- 5.2.6 Other Applications
- 5.3 By End User
- 5.3.1 Telecom Network Operators
- 5.3.2 Network Equipment Manufacturers
- 5.3.3 System Integrators
- 5.3.4 Certification Laboratories
- 5.4 By Deployment Model
- 5.4.1 Cloud-Based
- 5.4.2 On-Premises
- 5.4.3 Hybrid
- 5.5 By Network Architecture
- 5.5.1 Virtualized RAN
- 5.5.2 Cloud RAN
- 5.5.3 Disaggregated RAN
- 5.6 By Service Type
- 5.6.1 Managed Testing
- 5.6.2 Consulting
- 5.6.3 Integration
- 5.6.4 Certification
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 South America
- 5.7.2.1 Brazil
- 5.7.2.2 Argentina
- 5.7.2.3 Rest of South America
- 5.7.3 Europe
- 5.7.3.1 Germany
- 5.7.3.2 United Kingdom
- 5.7.3.3 France
- 5.7.3.4 Italy
- 5.7.3.5 Spain
- 5.7.3.6 Russia
- 5.7.3.7 Rest of Europe
- 5.7.4 Asia-Pacific
- 5.7.4.1 China
- 5.7.4.2 Japan
- 5.7.4.3 India
- 5.7.4.4 South Korea
- 5.7.4.5 Southeast Asia
- 5.7.4.6 Rest of Asia-Pacific
- 5.7.5 Middle East
- 5.7.5.1 Saudi Arabia
- 5.7.5.2 United Arab Emirates
- 5.7.5.3 Turkey
- 5.7.5.4 Rest of Middle East
- 5.7.6 Africa
- 5.7.6.1 South Africa
- 5.7.6.2 Nigeria
- 5.7.6.3 Rest of Africa
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Keysight Technologies, Inc.
- 6.4.2 Rohde & Schwarz GmbH & Co. KG
- 6.4.3 Anritsu Corporation
- 6.4.4 EXFO Inc.
- 6.4.5 LitePoint Corporation
- 6.4.6 Artiza Networks, Inc.
- 6.4.7 Teledyne LeCroy, Inc.
- 6.4.8 Tektronix, Inc.
- 6.4.9 National Instruments Corporation
- 6.4.10 Averna Technologies Inc.
- 6.4.11 Bird Technologies, Inc.
- 6.4.12 CommScope, Inc.
- 6.4.13 Radisys Corporation
- 6.4.14 VeEX Inc.
- 6.4.15 Calnex Solutions plc
- 6.4.16 PCTEL, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


