

|
시장보고서
상품코드
2157015
의료용 사출성형기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Medical Injection Molding Machine - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
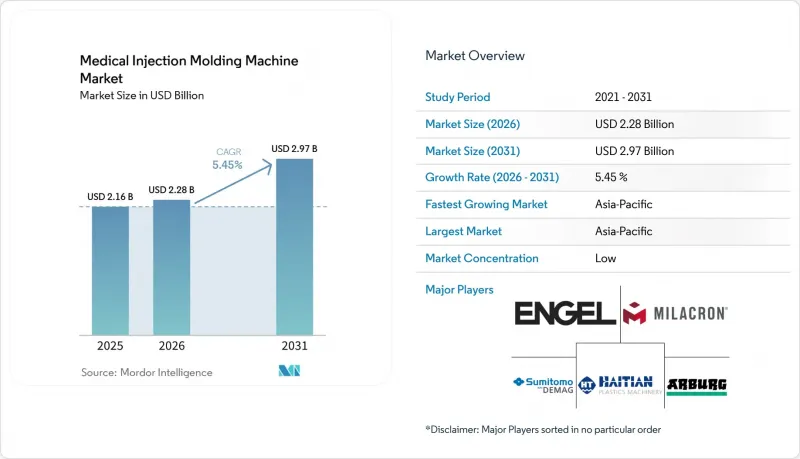
에 따르면 의료용 사출성형기 시장 규모는 2025년에 21억 6,000만 달러로 평가되며, 2026년 22억 8,000만 달러에서 2031년까지 29억 7,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 5.45%에 달할 전망입니다.
전 세계 의료용 사출성형기 시장의 동향 및 인사이트
일회용 및 최소 침습 의료기기에 대한 수요
일회용 의료 제품은 주사기, 정맥내 커넥터, 카테터 어셈블리 및 펜형 주사기 부품을 위한 다캐비티 성형기의 지속적인 구매를 지원하고 있습니다. 감염 관리에 대한 필요성, 예방 접종 프로그램 및 주사용 생물제제 요법이 이러한 생산 기반을 지탱하고 있습니다. 글루카곤 유사 펩티드-1(GLP-1) 전달 기기에 대한 수요가 증가함에 따라 펜형 주사기 제조사들은 더 짧은 기간 내에 성형 능력을 확대하고 있습니다. 장쑤 완하이 의료기기는 2025년 7월, 창저우에 3억 9,000만 위안(약 5,400만 달러)을 투자하여 펜형 주사기 제조 시설 건설을 시작했습니다. 연간 생산 능력은 자동 주사기를 포함해 3억 1,000만 개를 목표로 하고 있습니다. 또한 이 회사는 차세대 시스템에 대해 미국 식품의약국(FDA)의 510(k) 승인을 획득하기 위한 절차를 진행 중입니다. 의료용 사출성형기 시장에서는 ISO 10993의 생체 적합성 요건 및 재료의 추적성 요건을 충족하기 위해, 지정된 생산 구역에서 작동유를 배제할 수 있는 전동 프레스가 선호되고 있습니다.
진단용 및 약물전달용 부품의 정밀 생산
마이크로유체 칩, 프리필 가능한 주사기 배럴 및 약물전달용 펜 본체에는 엄격한 치수 관리가 요구됩니다. 서보 구동식 전동 및 하이브리드 성형기는 안정적인 사출 속도를 제공할 수 있지만, 유온 변동은 유압식 성형 공정에 영향을 미칠 가능성이 있습니다. 2026년 'Journal of Process Control' 저널에 실린 연구에 따르면 모델 예측형 캐비티 압력 제어를 통해 제조업체가 버진 수지와 재생 수지 배치를 전환할 때도 부품 품질의 편차를 0.21% 이내로 억제할 수 있었다고 보고되었습니다. 규제 대상 프로그램의 경우, 제조업체가 공정 성능을 문서화해야 하므로 캐비티별 데이터 로깅의 중요성이 높아지고 있습니다. 또한 웨어러블형 약물 투여 제품이나 현장 진단 기기에서도 샷 중량이 0.1g 미만으로 감소하고 있습니다. 이러한 용도에는 전용 마이크로 사출성형 유닛이 필요하며, 기존 성형기군이 가동 중이라 하더라도 의료용 사출성형기 시장에서 새로운 설비 투자가 필요할 가능성이 있습니다.
높은 초기 투자 비용과 총 소유 비용
클린룸 기능을 갖춘 전동식 의료용 사출성형기는 동급의 유압식 장비에 비해 가격이 30%-50% 더 비쌀 수 있습니다. 도입을 결정할 때는 클린룸 인프라, 온도 제어 장치, 재료 건조 및 이송 시스템, 자동화, 예방 정비 등도 고려해야 합니다. 이러한 연간 운영 비용은 기계 구매 가격의 15%-20%에 달할 수 있습니다. 생산량이 불확실하거나 생산 로트가 작은 경우, 소규모 수탁제조업체에게는 더 큰 어려움이 발생합니다. 이러한 과제는 비용 회수에 시간이 걸리는 남미, 중동 및 아프리카에서 특히 두드러집니다. 유럽이나 일본의 공급업체로부터의 납기가 지연될 경우, 의료용 사출성형기 시장의 구매자에게는 의료기기 프로그램이 규제상의 지연을 겪을 때 자금 조달 위험이 더욱 높아질 가능성이 있습니다.
부문 분석
2025년, 의료용 사출성형기 시장 규모의 42.45%를 전동식이 차지했습니다. 클린룸 호환성과 재현성이 높은 생산성은 북미 및 유럽의 의료기기 프로그램에서 검증된 생산에 활용되는 기반을 마련하고 있습니다. 유압식 성형기는 높은 클램핑력이 필요한 정형외과용 부품의 하우징이나 의료기기의 구조 부품에서 여전히 중요한 역할을 하고 있습니다. 그러나 더 많은 용도에서 클린룸 요구 사항이 확대됨에 따라 의료용 사출성형기 시장 전체에서 그 위상은 점차 낮아지고 있습니다. ARBURG GmbH+Co KG는 2025년 10월, 사노피(Sanofi)와 공동으로 ‘NextGen Medical Solution’을 발표했습니다. 이 솔루션에서는 전동식 ALLROUNDER 570 A와 8캐비티 금형을 사용하여 인젝터 펜 캡을 성형하고 있습니다.
하이브리드 방식은 2031년까지 연평균 성장률(CAGR) 6.06%로 확대될 것으로 예측됩니다. 이 방식은 전기식 특유의 청정성과, 두꺼운 벽면과 고압을 요구하는 의료용 부품에 필요한 성형력을 겸비하고 있습니다. Haitian Plastics Machinery사는 CHINAPLAS 2026에서 다캐비티 정밀 성형 및 의료용 ‘MA5/Ultra’를 출시했습니다. ARBURG GmbH+Co KG는 2026년 1월부터 의료용 인서트 성형용 ‘ALLROUNDER 475 V’의 전 세계 판매를 시작했습니다. 이 기종은 기존의 유압식 수직 프레스기와 비교하여 에너지 소비량을 최대 60% 절감했습니다.
핫 러너는 2025년 의료용 사출성형기 시장 규모의 58.11%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 6.23%로 확대될 것으로 예측됩니다. 이 기술을 통해 많은 일회용 의료 용도에서 재사용할 수 없는 콜드 러너 스크랩이 제거됩니다. 또한 다중 캐비티 금형에서 캐비티 간의 균형을 유지하는 데에도 도움이 됩니다. 탑 클린 패키징 그룹(Top Clean Packaging Group)은 의료용 폴리에테르에테르케톤(PEEK) 성형을 위한 셧오프식 핫러너 시스템을 통해 스프루가 제거되어 프로젝트의 수익성이 향상되었다고 보고했습니다. 환자가 접촉하는 부품에서 게이트 잔여물을 최소화해야 하는 경우에는 니들 밸브 게이트가 채택됩니다.
콜드 러너 시스템은 다중 소재 성형, 인서트 성형 및 소량 생산 개발 프로그램에 적합합니다. 가열 매니폴드에 대한 투자가 생산 경제성 측면에서 타당하지 않은 경우에도 적절한 대안이 될 수 있습니다. 스미토모(SHI) 데마그 플라스틱 머시너리(Sumitomo(SHI) Demag Plastic Machinery)는 K 2025에서 48 캐비티 핫러너 금형, 사이클 타임 3초, 연간 생산량 4억 3,200만 개의 의료용 컵 부품을 생산하는 ‘PAC-E 420’ 클린 토글 프레스를 전시했습니다. 일본의 공급업체들은 의료용 사출성형기 시장에서 기존부터 핫러너 통합을 활용하여 정밀 플랫폼의 차별화를 꾀해 왔습니다.
지역별 분석
아시아태평양은 2025년에 시장 점유율의 30.72%를 차지하며, 2031년까지 연평균 성장률(CAGR) 6.37%로 확대될 것으로 예측됩니다. 국내 위탁개발생산 기관(CDMO) 및 OEM 각사는 수출 프로그램을 위해 전동 및 하이브리드 기계군의 교체를 추진하고 있습니다. 인도의 의료기기용 ‘생산 연계형 인센티브 제도(PLIS)’는 4개의 의료기기 전용 산업단지를 대상으로 하고 있습니다. 루브리졸(Lubrizol)과 폴리호스 인디아(Polyhose India)는 2025년 첸나이에 ISO 13485 인증을 획득한 의료용 튜브 제조 시설을 개설했습니다.
일본은 닛세이 플라스틱 공업, 도요 이노벡스, 시바우라 기계, 파낙 주식회사, 일본제강소를 통해 여전히 높은 정밀 제조 능력을 유지하고 있습니다. 닛세이 플라스틱 공업과 도요 이노벡스는 2026년 4월 1일 GMS 그룹 산하에서의 사업 통합을 완료했습니다. 한국, 태국, 베트남, 말레이시아에서는 공급망 다각화를 도모하는 의료기기 제조업체들의 활동이 활발해지고 있습니다. 북미에서는 클래스 II 및 클래스 III 의료기기 생산에 주력하고 있습니다. ‘품질관리 시스템 규정’에 따라 미국의 규제 대상 프로그램에 참여하는 성형 제조업체들 사이에서 설비 감사가 촉진되고 있습니다.
유럽에서는 독일, 영국, 프랑스, 이탈리아, 북유럽 국가에서 높은 수요가 나타나고 있습니다. 규제 관련 문서의 요건과 에너지 효율 요건이 해당 지역의 전기 기기 수요를 지원하고 있습니다. 남미, 중동 및 아프리카에서는 의료 분야에 대한 투자 및 수입 대체와 연계된 비교적 소규모의 수요 기반이 나타나고 있습니다. 브라질, 아르헨티나, 사우디아라비아, 남아프리카공화국에서는 특정 분야의 활동이 활발하지만, 환율 변동 및 기술 지원의 제한으로 인해 도입이 용이한 하이브리드형이나 서보 유압식 플랫폼이 선호되는 경향이 있습니다. 의료용 사출성형기 시장은 고사양이 요구되는 지역부터 비용 효율을 중시하는 지역에 이르기까지 공급업체들에게 독자적인 비즈니스 기회를 제공하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
- 조사 전제조건과 시장 정의
- 조사 범위
제2장 조사 방법
제3장 개요
제4장 시장 구도
- 시장 개요
- 시장 성장 촉진요인
- 시장 성장 억제요인
- 밸류체인 분석
- Porter's Five Forces 분석
제5장 시장 규모와 성장 예측
- 제품 유형별
- 시스템 유형별
- 소재별
- 용도별
- 지역별
- 아시아태평양
- 중국
- 인도
- 일본
- 한국
- ASEAN 국가
- 기타 아시아태평양 국가
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 독일
- 영국
- 프랑스
- 이탈리아
- 북유럽 국가
- 기타 유럽 국가
- 남미
- 브라질
- 아르헨티나
- 기타 남미 국가
- 중동 및 아프리카
- 사우디아라비아
- 남아프리카공화국
- 기타 중동 및 아프리카 국가
- 아시아태평양
제6장 경쟁 구도
- 시장 집중도
- 전략적 동향
- 시장 점유율·순위 분석
- 기업 개요
- ARBURG GmbH+Co KG
- Chen Hsong CO.,LTD
- ENGEL
- FANUC Corporation
- Haitian Plastics Machinery
- Husky Technologies
- KraussMaffei Group GmbH
- Milacron Holdings, LLC
- NISSEI PLASTIC INDUSTRIAL CO., LTD.
- Shibaura Machine
- Sumitomo(SHI) Demag Plastics Machinery GmbH
- The Japan Steel Works, LTD.
- TOYO INNOVEX Co., Ltd.
- UBE Machinery Inc.
- WITTMANN Technology GmbH
제7장 시장 기회와 향후 전망
KSA 26.10.29According to Mordor Intelligence, the medical injection molding machine market size was valued at USD 2.16 billion in 2025 and is estimated to grow from USD 2.28 billion in 2026 to reach USD 2.97 billion by 2031, at a CAGR of 5.45% during the forecast period (2026-2031).
Global Medical Injection Molding Machine Market Trends and Insights
Demand for Single-Use and Minimally Invasive Devices
Single-use medical products are supporting sustained purchases of high cavity machines for syringes, intravenous connectors, catheter assemblies, and pen injector components. Infection control needs, immunization programs, and injectable biologic therapies support this production base. Pen injector manufacturers are expanding molding capacity on shorter schedules as demand for glucagon-like peptide-1 delivery devices grows. Jiangsu Wanhai Medical Instruments Co., Ltd. began construction of a CNY 390 million investment (approximately USD 54 million) pen injector facility in Changzhou in July 2025, with annual capacity targeted at 310 million units, including autoinjectors. The company is also pursuing U.S. Food and Drug Administration 510(k) clearance for its next-generation systems. Within the medical injection molding machine market, ISO 10993 biocompatibility needs and material traceability requirements favor electric presses because they eliminate hydraulic oil from classified production areas.
Precision Production of Diagnostic and Drug-Delivery Components
Microfluidic chips, prefillable syringe barrels, and drug-delivery pen bodies require tight dimensional control. Servo-driven electric and hybrid machines can provide consistent injection velocity, while oil-temperature variation can affect hydraulic production runs. A 2026 Journal of Process Control study reported that model-predictive cavity-pressure control kept part-mass deviation within 0.21% when manufacturers switched between virgin and recycled polymer batches. Per-cavity data logging is becoming more important in regulated programs because manufacturers must document process performance. Wearable drug-delivery products and point-of-care diagnostic devices are also reducing shot weights below 0.1 g. These applications require dedicated micro-injection units and can require new capital equipment in the medical injection molding machine market, even when an existing molding fleet remains operational.
High Capital and Total Cost of Ownership
All-electric medical injection molding equipment with cleanroom features can carry a 30%-50% price premium over comparable hydraulic equipment. The acquisition decision also includes cleanroom infrastructure, temperature-control units, material drying and conveying systems, automation, and preventive maintenance. These annual operating requirements can add 15%-20% of the machine purchase cost. Smaller contract manufacturers face greater difficulty when volumes are uncertain or production runs are short. The challenge is particularly relevant in South America and Middle East and Africa, where cost recovery can take longer. Longer delivery times from European and Japanese suppliers can further increase financing exposure for medical injection molding machine market buyers when device programs face regulatory delays.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Electric, Cleanroom-Compatible Presses
- Expansion of Medical-Device Manufacturing in Asia-Pacific
- Validation and Qualification Burden
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Electric held 42.45% of the medical injection molding machine market size in 2025. Its cleanroom compatibility and repeatable output support use in validated production for North American and European device programs. Hydraulic machines remain relevant for orthopedic component housings and structural device parts that require high clamping force. Their position is declining across the medical injection molding machine market as cleanroom mandates expand across more applications. ARBURG GmbH + Co KG presented its NextGen Medical Solution with Sanofi in October 2025, using an all-electric ALLROUNDER 570 A and an 8-cavity mold for injector pen caps.
Hybrid is projected to advance at a 6.06% CAGR through 2031. It combines electric cleanliness with the force needed for thicker-wall and higher-pressure medical parts. Haitian Plastics Machinery launched the MA5/Ultra at CHINAPLAS 2026 for multi-cavity precision and medical applications. ARBURG GmbH + Co KG began worldwide sales of the ALLROUNDER 475 V in January 2026 for medical insert molding, with energy use up to 60% lower than conventional hydraulic vertical presses.
Hot runner held 58.11% of the medical injection molding machine market size in 2025 and is projected to advance at a 6.23% CAGR through 2031. It eliminates cold runner scrap that cannot be reused in many single-use medical applications. The technology also helps preserve cavity-to-cavity balance in high-cavity molds. Top Clean Packaging Group reported that its shut-off hot runner system for medical-grade polyether ether ketone molding eliminated sprues and improved project profitability. Needle-valve gating is used where a low gate vestige is required for patient-contact parts.
Cold runner systems continue to suit multi-material, insert-molded, and lower-volume development programs. They can be appropriate where heated-manifold investment is not supported by production economics. Sumitomo (SHI) Demag Plastics Machinery GmbH demonstrated its PAC-E 420 clean-toggle press at K 2025 with a 48-cavity hot runner mold, a 3-second cycle time, and an annual output of 432 million medical cup components. Japanese suppliers have historically used hot runner integration to differentiate precision platforms in the medical injection molding machine market.
Complete Report Scope:
- By Product Type
- Electric
- Hydraulic
- Hybrid
- By System Type
- Hot Runner
- Cold Runner
- By Material
- Plastics
- Metals
- Other Materials
- By Application
- Consumables
- Medical Equipment Components
- Patient Aids
- Orthopedic Instruments
- Dental Products
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific held 30.72% of the market share in 2025 and is projected to advance at a 6.37% CAGR through 2031. Domestic contract development and manufacturing organizations and original equipment manufacturers are updating electric and hybrid fleets for export programs. India's Production Linked Incentive Scheme for medical devices covers 4 dedicated medical device parks. Lubrizol and Polyhose India opened an ISO 13485-certified medical tubing facility in Chennai in 2025.
Japan retains substantial precision manufacturing capability through NISSEI PLASTIC INDUSTRIAL CO., LTD., TOYO INNOVEX Co., Ltd., Shibaura Machine, FANUC Corporation, and The Japan Steel Works, LTD. NISSEI PLASTIC INDUSTRIAL CO., LTD. and TOYO INNOVEX Co., Ltd. completed their business integration under GMS Group Co., Ltd. on April 1, 2026. South Korea, Thailand, Vietnam, and Malaysia are attracting activity from device companies diversifying supply chains. North America concentrates on Class II and Class III device production. The Quality Management System Regulation is prompting equipment audits among molders serving U.S.-regulated programs.
Europe has sophisticated demand across Germany, the United Kingdom, France, Italy, and the Nordic countries. Regulatory documentation needs and energy-efficiency requirements support electric equipment in the region. South America and Middle East and Africa have smaller demand bases tied to healthcare investment and import substitution. Brazil, Argentina, Saudi Arabia, and South Africa support targeted activity, while currency volatility and limited technical support can favor accessible hybrid and servo-hydraulic platforms. The medical injection molding machine market offers suppliers distinct opportunities across high-specification and cost-sensitive geographies.
- ARBURG GmbH + Co KG
- Chen Hsong CO.,LTD
- ENGEL
- FANUC Corporation
- Haitian Plastics Machinery
- Husky Technologies
- KraussMaffei Group GmbH
- Milacron Holdings, LLC
- NISSEI PLASTIC INDUSTRIAL CO., LTD.
- Shibaura Machine
- Sumitomo (SHI) Demag Plastics Machinery GmbH
- The Japan Steel Works, LTD.
- TOYO INNOVEX Co., Ltd.
- UBE Machinery Inc.
- WITTMANN Technology GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Demand for Single-Use and Minimally Invasive Devices
- 4.2.2 Precision Production of Diagnostic and Drug-Delivery Components
- 4.2.3 Shift Toward Electric, Cleanroom-Compatible Presses
- 4.2.4 Expansion of Medical-Device Manufacturing in Asia-Pacific
- 4.2.5 Cavity-Level Digital Control for Faster Validation
- 4.3 Market Restraints
- 4.3.1 High Capital and Total Cost of Ownership
- 4.3.2 Validation and Qualification Burden
- 4.3.3 Shortage of Specialized Tooling and Process Engineers
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Electric
- 5.1.2 Hydraulic
- 5.1.3 Hybrid
- 5.2 By System Type
- 5.2.1 Hot Runner
- 5.2.2 Cold Runner
- 5.3 By Material
- 5.3.1 Plastics
- 5.3.2 Metals
- 5.3.3 Other Materials
- 5.4 By Application
- 5.4.1 Consumables
- 5.4.2 Medical Equipment Components
- 5.4.3 Patient Aids
- 5.4.4 Orthopedic Instruments
- 5.4.5 Dental Products
- 5.4.6 Other Applications
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 NORDIC Countries
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 ARBURG GmbH + Co KG
- 6.4.2 Chen Hsong CO.,LTD
- 6.4.3 ENGEL
- 6.4.4 FANUC Corporation
- 6.4.5 Haitian Plastics Machinery
- 6.4.6 Husky Technologies
- 6.4.7 KraussMaffei Group GmbH
- 6.4.8 Milacron Holdings, LLC
- 6.4.9 NISSEI PLASTIC INDUSTRIAL CO., LTD.
- 6.4.10 Shibaura Machine
- 6.4.11 Sumitomo (SHI) Demag Plastics Machinery GmbH
- 6.4.12 The Japan Steel Works, LTD.
- 6.4.13 TOYO INNOVEX Co., Ltd.
- 6.4.14 UBE Machinery Inc.
- 6.4.15 WITTMANN Technology GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment


