

|
시장보고서
상품코드
2125139
대용량 웨어러블 주사기 시장 : 동향 및 예측(-2035년)Large Volume Wearable Injectors Market - Trends and Forecast, Till 2035 |
||||||

대용량 웨어러블 주사기 시장: 개요
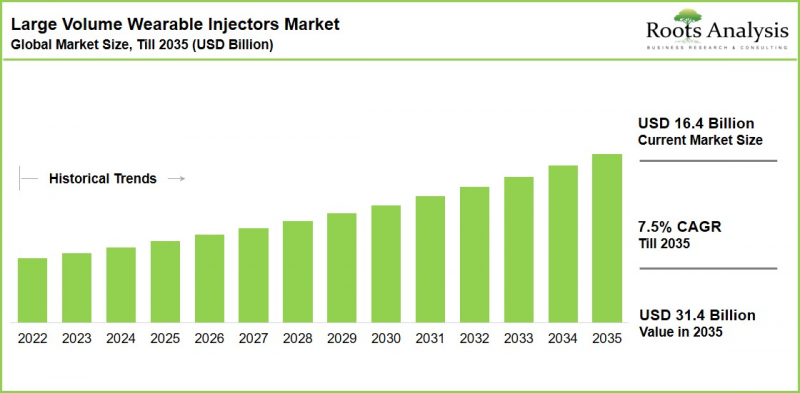
Roots Analysis의 조사에 따르면 세계의 대용량 웨어러블 주사기 시장 규모는 올해 164억 달러에서 2035년에는 314억 달러로 확대하며, 2035년 예측 기간의 CAGR 7.5%로 성장할 것으로 추정되고 있습니다.
대용량 웨어러블 주사기 시장: 성장 및 동향
만성질환 및 복잡한 질환으로 인한 전 세계적 부담 증가에 더해, 모노클로널 항체나 항체-약물 접합체(ADC) 등 대용량 및 고점도의 생물제제 파이프라인이 확대됨에 따라 신체 착용형 투여 형태에 대한 수요가 지속적으로 견인되고 있습니다. 신체 착용형 패치 펌프 및 체외형 주입식 펌프를 포함한 대용량 웨어러블 주사기는 임상 현장 이외의 장소에서도 이러한 약물을 기초 투여, 볼러스 투여 또는 지속 피하 투여할 수 있으며, 정맥내 주입에 대한 의존도를 낮춥니다.
제약사들이 환자 중심의 재택 케어 모델로 전환하는 가운데, 웨어러블 주사기는 기존 생물제제의 수명주기관리 툴로서, 또한 개발 후기 단계에 있는 파이프라인 후보의 차별화 요인으로 점점 더 중요한 위치를 차지하고 있습니다. Enable Injections나 West Pharmaceutical Services와 같은 의료기기 개발 기업은 제약 기업과의 라이선싱 계약 및 공동 개발 계약을 지속적으로 확대하고 있으며, 이는 재택 투여용 대량 투여형으로 환자가 즉시 사용할 수 있는 투여 시스템에 대한 신뢰가 높아지고 있음을 반영합니다.
성장의 원동력: 시장 확장을 지원하는 전략적 요인
시장 성장은 정기적이고 대량 투여가 필요한 암, 자가면역, 심혈관, 신경계 질환의 유병률 증가와 더불어 자가 투여 및 재택 치료로의 광범위한 전환에 힘입어 가속화되고 있습니다. 웨어러블 주사기는 병원이나 수액 치료 센터를 방문해야 할 필요성을 줄이고, 치료 투여에 드는 전반적인 비용 부담을 경감하며, 복약 순응도를 향상시킵니다. 이러한 이점들은 제약사와 보험사 모두에게 이 기술의 매력을 더욱 높여주고 있습니다.
웨어러블 주사기 시장: 주요 인사이트
이 보고서는 웨어러블 주사기 시장의 현황을 상세히 분석하고, 업계내 잠재적인 성장 기회를 파악하고 있습니다. 주요 조사 결과는 다음과 같습니다.
- 대용량 웨어러블 주사기 개발 기업은 주로 직접 라이선싱 계약이나 공동 개발 계약을 통해 제약 기업과 제휴하고 있습니다. 이로 인해 전문 의료기기 물류 분야에서 기존 네트워크를 보유한 전통적 유통업체라 하더라도 이 분야의 동향을 파악하기 어려운 상황에 처해 있습니다.
- 많은 웨어러블 주사기가 온도에 민감한 생물제제와 함께 사용되므로 전문 콜드 체인 및 라스트 마일 물류 파트너가 웨어러블 주사기 공급망에서 필수적인 역할을 담당하는 주체로 부상하고 있습니다.
- 이 분야에 진출하고자 하는 유통업체나 물류 파트너는 GMP를 준수하는 검증된 취급 절차를 확립하고 있으며, 복합 제품의 규제 요건에 정통함을 입증해야 합니다.
- 신체에 착용하는 암, 자가면역 질환, 신경질환 치료용 생물제제의 파이프라인이 확대됨에 따라 전문 유통 인프라에 대한 수요 증가가 지속될 것으로 예상됩니다.
- 점적식 형태에서 패치 펌프형 설계로의 전환에 따라 소규모이면서 기동성이 높은 물류 및 판매 채널 파트너들이 기존 주요 기업과 어깨를 나란히 하며 시장에 진입할 기회가 생기고 있습니다.
- SHL Medical의 Weibel CDS 인수 등 의료기기 개발 기업 간의 통합이 진행되고 있으며, 소규모 지역 사업자에게는 진입 장벽이 높아지고 있는 반면, 틈새 분야나 특정 치료법에 특화된 유통 파트너에게는 진입 기회가 생기고 있습니다.
- 유통업체와 채널 파트너는 물류 비용뿐만 아니라 의료기기 교육 지원, 환자용 도입 자료, 재고 관리 등의 부가가치 서비스 분야에서 점점 더 치열한 경쟁을 펼치고 있습니다.
- 승인된 생물제제의 수명주기관리 툴로서 웨어러블 주사기에 대한 관심이 높아짐에 따라 유통 지원이 필요한 의약품·의료기기 복합 제품의 잠재적 시장 규모가 확대될 것으로 예상됩니다.
웨어러블 주사기 시장
시장 규모 및 기회 분석은 다음 매개변수를 기준으로 분류됩니다.
기기 유형별
- 패치 펌프
- 주입 펌프
사용 형태별
- 일회용
- 재사용 가능(일회용 부품 사용)
치료 분야별
- 암
- 심혈관계 질환
- 신경계 질환
- 자가면역 질환
- 기타 질환
지역별
- 북미
- 미국
- 캐나다
- 멕시코
- 유럽
- 프랑스
- 독일
- 영국
- 이탈리아
- 스페인
- 기타 유럽
- 아시아태평양
- 중국
- 인도
- 일본
- 기타 아시아태평양
- 라틴아메리카
- 아르헨티나
- 브라질
- 중동·북아프리카
- 이집트
- 이스라엘
- 사우디아라비아
이 보고서에서는 전 세계 대용량 웨어러블 주사기 시장을 조사하여, 시장 개요, 배경, 시장 영향 요인 분석, 시장 규모 추이 및 전망, 각종 분류별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 정리하여 전해드립니다.
목차
제1장 서문
제2장 조사 방법
제3장 시장 역학
제4장 거시경제 지표
제5장 개요
제6장 서론
제7장 비인슐린약용 대용량 웨어러블 주입기 : 시장 상황 개요
제8장 비인슐린약용 의약품·의료기기 콤비네이션 제품 : 시장 상황 개요
제9장 제품의 경쟁력 분석
제10장 대용량 웨어러블 주사기 개발 기업 : 기업 개요
제11장 의약품·의료기기 콤비네이션 제품 : 기기 개요
제12장 제휴·협업
제13장 주요인수 대상 기업
제14장 특허 분석
제15장 대용량 웨어러블 주사기 : 유망 약제 후보
제16장 임상시험 분석
제17장 자금조달과 투자 분석
제18장 SWOT 분석
제19장 사례 연구 : 의료기기 개발 공급망에서 CMO의 역할
제20장 의료기기에 관한 규제·상환 제도의 현황
제21장 시장 영향 분석 : 촉진요인, 저해요인, 기회, 과제
제22장 대용량 웨어러블 주사기 시장
제23장 대용량 웨어러블 주사기 시장 : 디바이스 유형별
제24장 대용량 웨어러블 주사기 시장 : 사용 형태별
제25장 대용량 웨어러블 주사기 시장 : 치료 영역별
제26장 대용량 웨어러블 주사기 시장 : 지역별
제27장 결론
제28장 이그제큐티브 인사이트
제29장 부록 I : 표형식 데이터
제30장 부록 II : 기업 및 조직 리스트
KSA 26.09.11LARGE VOLUME WEARABLE INJECTORS MARKET: OVERVIEW
As per Roots Analysis, the global large volume wearable injectors market is estimated to grow from USD 16.4 billion in the current year to USD 31.4 billion by 2035, at a CAGR of 7.5% during the forecast period, till 2035.
Large Volume Wearable Injectors Market: Growth and Trends
The rising global burden of chronic and complex diseases, coupled with the growing pipeline of high-volume, high-viscosity biologics such as monoclonal antibodies and antibody-drug conjugates, continues to drive demand for on-body delivery formats. Large volume wearable injectors, including on-body patch pumps and off-body infusion-style pumps, allow sustained basal, bolus, or continuous subcutaneous delivery of these drugs outside the clinical setting, reducing dependence on intravenous infusion.
As pharmaceutical companies shift toward patient-centric, home-based care models, wearable injectors are increasingly positioned as a life-cycle management tool for existing biologics as well as a differentiator for late-stage pipeline candidates. Device developers such as Enable Injections and West Pharmaceutical Services continue to expand licensing and co-development arrangements with pharmaceutical sponsors, reflecting rising confidence in large-volume, patient-ready delivery systems for home administration.
Growth Drivers: Strategic Enablers of Market Expansion
Market growth is being propelled by the rising prevalence of oncological, autoimmune, cardiovascular, and neurological disorders that require regular, high-volume biologic dosing, alongside the broader shift toward self-administration and home care. Wearable injectors reduce the need for hospital or infusion-center visits, lower the overall cost burden of therapy administration, and improve medication adherence. These benefits are reinforcing their appeal to both pharmaceutical sponsors and payers.
Market Challenges: Critical Barriers Impeding Progress
Despite favorable prospects, the market faces headwinds from the relatively high cost of advanced on-body devices and limited reimbursement coverage in several geographies, which restricts adoption among cost-sensitive patient populations. Prolonged regulatory review timelines for novel drug-device combination products, particularly with agencies such as the USFDA, add further cost and delay to product launches, creating near-term uncertainty for developers and their commercial partners.
Wearable Injectors Market: Key Insights
The report delves into the current state of the wearable injectors market and identifies potential growth opportunities within industry. Some key findings include:
- Large volume wearable injector developers predominantly engage pharmaceutical sponsors through direct licensing and co-development agreements. This limits the visibility that traditional distributors have into this segment, despite their established reach into specialty medical device logistics.
- Specialty cold-chain and last-mile logistics partners are emerging as critical enablers of the wearable injector supply chain, given that many of these devices are paired with temperature-sensitive biologics.
- Distributors and logistics partners seeking entry into this space must demonstrate validated GMP-aligned handling protocols and familiarity with combination-product regulatory requirements.
- The growing pipeline of oncology, autoimmune, and neurological biologics compatible with on-body delivery is expected to sustain elevated demand for specialized distribution infrastructure.
- The shift from infusion-style formats toward patch pump designs is opening opportunities for smaller, more agile logistics and channel partners to enter alongside established players.
- Consolidation among device developers, such as SHL Medical's acquisition of Weibel CDS, is raising barriers to entry for smaller regional players while creating openings for niche, modality-specific distribution partners.
- Distributors and channel partners increasingly compete on value-added services, including device training support, patient onboarding materials, and inventory management, rather than on logistics cost alone.
- Rising interest in wearable injectors as a life-cycle management tool for approved biologics is expected to broaden the addressable base of drug-device combinations requiring distribution support.
Wearable Injectors Market
The market sizing and opportunity analysis has been segmented across the following parameters:
By Type of Device
- Patch Pumps
- Infusion Pumps
By Usability
- Disposable
- Reusable (Disposable Components)
By Therapeutic Area
- Oncological Disorders
- Cardiovascular Disorders
- Neurological Disorders
- Autoimmune Disorders
- Other Disorders
By Geographical Regions
- North America
- US
- Canada
- Mexico
- Europe
- France
- Germany
- UK
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Rest of Asia-Pacific
- Latin America
- Argentina
- Brazil
- Middle East and North Africa
- Egypt
- Israel
- Saudi Arabia
Wearable Injectors Market: Key Segments
Market Share by Usability: Disposable Devices Hold the Largest Market Share
According to our proprietary market report, disposable devices account for the largest share of the global market, and this trend is expected to persist throughout the forecast period. This can be attributed to the growing preference for single-use drug delivery systems that offer enhanced convenience, improved patient safety, and simplified treatment administration, particularly in home healthcare settings.
Disposable wearable injectors eliminate the need for cleaning, sterilization, and routine maintenance, thereby reducing the burden on both patients and caregivers while minimizing the risk of device-related contamination and cross-infection. Further, the increasing adoption of self-administered therapies, coupled with the rising demand for home-based healthcare and patient-centric drug delivery solutions, is expected to support the continued dominance of the disposable devices segment during the forecast period.
Market Share by Therapeutic Area: Oncology Segment Accounts for the Largest Revenue Share
According to our market analysis, the oncology segment currently holds the largest share of the market. This dominance is primarily driven by the rising global burden of cancer, expanding commercialization of oncology biologics, and increasing preference for subcutaneous administration of large-volume therapies outside conventional clinical settings.
Large volume wearable injectors enable the controlled administration of monoclonal antibodies, immunotherapies, and supportive oncology treatments. This allows patients to receive therapy in home care settings while reducing the need for prolonged hospital visits. The growing emphasis on improving patient convenience, optimizing healthcare resources, and expanding access to home-based cancer care is further strengthening the adoption of wearable injectors within this therapeutic area.
Meanwhile, the neurological disorders segment is anticipated to register the highest CAGR during the forecast period. This lucrative growth is supported by recent regulatory approvals for wearable drug delivery technologies, increasing availability of biologic therapies for neurological conditions, and the growing adoption of home-based treatment approaches for diseases such as Parkinson's disease.
Market Share by Device Type: Patch Pumps are Expected to Witness the Fastest Growth
Based on device type, the market is segmented into patch pumps and infusion-style wearable injectors. Infusion-style wearable injectors continue to maintain a significant market presence owing to their established use in administering high-volume biologics.
On the other hand, patch pumps will grow at higher CAGR during the forecast period. The increasing adoption of patch pumps is driven by their compact, lightweight, and skin-adhered design, which enhances patient comfort, mobility, and discretion during therapy. These devices are particularly well suited for the subcutaneous administration of large-volume biologics in chronic disease management, enabling patients to receive treatment outside traditional healthcare facilities.
Continuous technological innovations, including Bluetooth connectivity, smartphone-enabled monitoring, automated dose tracking, and digital health integration, are improving treatment adherence and overall user experience. As pharmaceutical and medical device companies continue to develop next-generation wearable platforms capable of delivering high-viscosity biologics with greater precision, patch pumps are expected to gain a larger share of the market over the forecast period.
Market Share by Region: North America Holds the Largest Share, While Asia-Pacific is the Fastest-Growing Regional Market
North America accounts for the largest share of the non-insulin large volume wearable injectors market. The region's leadership is supported by its well-established healthcare infrastructure, favorable reimbursement landscape, widespread adoption of advanced drug delivery technologies, and the strong presence of leading pharmaceutical companies, and medical device manufacturers. Additionally, the increasing prevalence of chronic diseases, growing utilization of biologic therapies, and continued investments in innovative wearable drug delivery platforms are expected to sustain the region's dominant position.
In contrast, the Asia-Pacific market is projected to register the highest CAGR during the forecast period. This growth is driven by rapidly expanding healthcare infrastructure, increasing healthcare expenditure, rising disposable incomes, and improving access to advanced biologic therapies across emerging economies such as China and India. Furthermore, favorable government initiatives to strengthen healthcare systems, growing awareness of self-administered drug delivery technologies, and increasing investments by global pharmaceutical and medical device companies are expected to create significant opportunities for market expansion across the region.
Example Players in Wearable Injectors Market
- Becton Dickinson (BD)
- Enable Injections
- E3D Elcam Drug Delivery Devices
- Stevanato Group
- Ypsomed
Expert Interview and Industry Insights
The opinions and insights presented in this study were influenced by discussions conducted with multiple stakeholders. The research report features detailed transcripts of interviews held with the following industry stakeholders:
- Chief Executive Officer, Small Company, US
- Chief Executive Officer, Mid-Sized Company, US
- Chief Executive Officer, Small Company, Denmark
- Former President and Chief Executive Officer, Mid-Sized Company, US
- Vice President and Chief Scientist, Large Company, Israel
- Former Vice President and General Manager, Biologics, Very Large Company, US
- Anonymous, Large Company, Switzerland
- Engineering Project Manager / Senior System Engineer, Small Company, Switzerland
- Vice President, Marketing and Alliance Management, Mid-Sized Company, US
WEARABLE INJECTORS MARKET: RESEARCH COVERAGE
- Market Sizing and Opportunity Analysis: An in-depth analysis of the market by value and volume, focusing on key segments, including type of device, usability, therapeutic area, and geographical regions.
- Non-Insulin Market Landscape: A detailed assessment of large volume wearable injectors developed for non-insulin drugs, covering type of device, status of development, drug reservoir volume, therapeutic area, and drug container / filling attributes.
- Drug-Device Combination Landscape: An analysis of marketed and pipeline drug-device combinations built on wearable injector platforms, covering the same set of technical and commercial parameters.
- Product Competitiveness Analysis: A comparative evaluation of leading large volume wearable injectors and drug-device combinations against defined product attributes and market positioning criteria.
- Company Profiles: In-depth profiles of prominent device developers, covering year of establishment, headquarters location, company size, product portfolio, and recent developments.
- Device Profiles: Individual profiles of marketed drug-device combinations built on wearable injector platforms, including device design and intended therapeutic use.
- Partnerships and Collaborations: An analysis of partnerships inked by large volume wearable injector developers, based on year, type of partnership, type of partner, type of device, and geography.
- Key Acquisition Targets: A scoring-based assessment identifying potential acquisition targets among non-insulin drug delivery device developers.
- Patent Analysis: A review of the patent landscape, covering patent type, publication trends, jurisdiction, applicant type, and the most active players by patent filings.
- Likely Drug Candidates: An assessment of marketed and clinical-stage drugs most likely to be delivered via large volume wearable injectors, based on defined suitability criteria.
- Clinical Trial Analysis: A review of registered clinical trials evaluating large volume wearable injectors, covering trial phase, recruitment status, sponsor type, therapeutic area, and geography.
- Funding and Investment Analysis: A detailed analysis of funding instances in this domain, based on year, type of funding, amount invested, target indication, and the most active investors and players.
- SWOT Analysis and Growth Opportunities: A strategic assessment of the market's strengths, weaknesses, opportunities, and threats, along with an evaluation of future growth avenues, including life-cycle management and multi-indication use.
- Case Study: A focused assessment of the role played by contract manufacturing organizations in the wearable injector device development supply chain, including a list of active CMOs.
- Regulatory and Reimbursement Landscape: A region-wise review of the regulatory approval pathways and reimbursement frameworks applicable to combination medical devices across North America, Europe, Asia-Pacific, and the Rest of the World.
- Market Impact Analysis: An assessment of the key drivers, restraints, opportunities, and challenges shaping the evolution of the large volume wearable injectors market.
- Executive Insights: Anonymized snapshots and interview transcripts capturing perspectives from senior executives and technical leaders across device developer organizations.
KEY QUESTIONS ANSWERED IN THIS REPORT
- Which are the leading companies developing large volume wearable injectors?
- Which region dominates the market, and which is growing the fastest?
- What are the key trends observed in this market?
- What factors are likely to influence the evolution of this market?
- What are the primary challenges faced by device developers and their commercial partners?
- What is the current and future market size?
- What is the CAGR of this market through 2035?
- How is current and future market opportunity distributed across type of device, usability, therapeutic area, and geography?
- What opportunities exist for distributors and logistics partners entering this space?
REASONS TO BUY THIS REPORT
- Top-Down and Bottom-Up Triangulated Forecasting: Market estimates are built using a hybrid methodology that cross-validates top down macro assessments against bottom-up, device-level and company-level data, minimizing forecast bias.
- Distribution and Channel-Partner Lens: Unlike conventional device capability reports, this study explicitly maps the cold-chain, logistics, and value-added service opportunities available to distribution partners entering the wearable injector supply chain.
- 653 Pages Across 30 Chapters: Comprehensive coverage spanning market sizing, competitive benchmarking, patent landscape, clinical trial activity, funding and M&A analysis, and regulatory / reimbursement mapping across 20+ countries.
- Primary Research-Backed Insights: Findings are validated through direct interviews with CEOs, chief scientists, and commercial leaders across small, mid-sized, and large device developers, ensuring insights reflect real operating conditions rather than desk research alone.
- Actionable Segmentation: Four-parameter segmentation (type of device, usability, therapeutic area, geography) enables precise opportunity sizing for any go-to-market or investment thesis.
ADDITIONAL BENEFITS
- Complementary PPT Insight Packs
- Complementary Excel Data Packs for all Analytical Modules in the Report
- 15% Free Content Customization
- Detailed Report Walkthrough Session with Research Team
- Free Updated Report if the Report is 6-12 Months Old or Older
TABLE OF CONTENTS
1. PREFACE
- 1.1. Introduction
- 1.2. Report Coverage
- 1.3. Market Segmentation
- 1.4. Key Market Insights
- 1.5. Market Share Insights
- 1.6. Key Questions Answered
2. RESEARCH METHODOLOGY
- 2.1. Chapter Overview
- 2.2. Research Assumptions
- 2.2.1. Market Landscape and Market Trends
- 2.2.2. Market Forecast and Opportunity Analysis
- 2.2.3. Comparative Analysis
- 2.3. Database Building
- 2.3.1. Data Collection
- 2.3.2. Data Validation
- 2.3.3. Data Analysis
- 2.4. Project Methodology
- 2.4.1. Secondary Research
- 2.4.1.1. Annual Reports
- 2.4.1.2. Academic Research Papers
- 2.4.1.3. Company Websites
- 2.4.1.4. Investor Presentations
- 2.4.1.5. Regulatory Filings
- 2.4.1.6. White Papers
- 2.4.1.7. Industry Publications
- 2.4.1.8. Conferences and Seminars
- 2.4.1.9. Government Portals
- 2.4.1.10. Media and Press Releases
- 2.4.1.11. Newsletters
- 2.4.1.12. Industry Databases
- 2.4.1.13. Roots Proprietary Databases
- 2.4.1.14. Paid Databases and Sources
- 2.4.1.15. Social Media Portals
- 2.4.1.16. Other Secondary Sources
- 2.4.2. Primary Research
- 2.4.2.1. Types of Primary Research
- 2.4.2.1.1. Qualitative Research
- 2.4.2.1.2. Quantitative Research
- 2.4.2.1.3. Hybrid Approach
- 2.4.2.2. Advantages of Primary Research
- 2.4.2.3. Techniques for Primary Research
- 2.4.2.3.1. Interviews
- 2.4.2.3.2. Surveys
- 2.4.2.3.3. Focus Groups
- 2.4.2.3.4. Observational Research
- 2.4.2.3.5. Social Media Interactions
- 2.4.2.4. Key Opinion Leaders Considered in Primary Research
- 2.4.2.4.1. Company Executives (CXOs)
- 2.4.2.4.2. Board of Directors
- 2.4.2.4.3. Company Presidents and Vice Presidents
- 2.4.2.4.4. Research and Development Heads
- 2.4.2.4.5. Technical Experts
- 2.4.2.4.6. Subject Matter Experts
- 2.4.2.4.7. Scientists
- 2.4.2.4.8. Doctors and Other Healthcare Providers
- 2.4.2.5. Ethics and Integrity
- 2.4.2.5.1. Research Ethics
- 2.4.2.5.2. Data Integrity
- 2.4.2.1. Types of Primary Research
- 2.4.3. Analytical Tools and Databases
- 2.4.1. Secondary Research
- 2.5. Robust Quality Control
3. MARKET DYNAMICS
- 3.1. Chapter Overview
- 3.2. Forecast Methodology
- 3.2.1. Top-down Approach
- 3.2.2. Bottom-up Approach
- 3.2.3. Hybrid Approach
- 3.3. Market Assessment Framework
- 3.3.1. Total Addressable Market (TAM)
- 3.3.2. Serviceable Addressable Market (SAM)
- 3.3.3. Serviceable Obtainable Market (SOM)
- 3.3.4. Currently Acquired Market (CAM)
- 3.4. Forecasting Tools and Techniques
- 3.4.1. Qualitative Forecasting
- 3.4.2. Correlation
- 3.4.3. Regression
- 3.4.4. Extrapolation
- 3.4.5. Convergence
- 3.4.6. Sensitivity Analysis
- 3.4.7. Scenario Planning
- 3.4.8. Data Visualization
- 3.4.9. Time Series Analysis
- 3.4.10. Forecast Error Analysis
- 3.5. Key Considerations
- 3.5.1. Demographics
- 3.5.2. Government Regulations
- 3.5.3. Reimbursement Scenarios
- 3.5.4. Market Access
- 3.5.5. Supply Chain
- 3.5.6. Industry Consolidation
- 3.5.7. Pandemic / Unforeseen Disruptions Impact
- 3.6. Limitations
4. MACRO-ECONOMIC INDICATORS
- 4.1. Chapter Overview
- 4.2. Market Dynamics
- 4.2.1. Time Period
- 4.2.1.1. Historical Trends
- 4.2.1.2. Current and Forecasted Estimates
- 4.2.2. Currency Coverage
- 4.2.2.1. Major Currencies Affecting the Market
- 4.2.2.2. Factors Affecting Currency Fluctuations
- 4.2.2.3. Impact of Currency Fluctuations on the Industry
- 4.2.3. Foreign Currency Exchange Rate
- 4.2.3.1. Impact of Foreign Exchange Rate Volatility on the Market
- 4.2.3.2. Strategies for Mitigating Foreign Exchange Risk
- 4.2.4. Recession
- 4.2.4.1. Assessment of Current Economic Conditions and Potential Impact on the Market
- 4.2.4.2. Historical Analysis of Past Recessions and Lessons Learnt
- 4.2.5. Inflation
- 4.2.5.1. Measurement and Analysis of Inflationary Pressures in the Economy
- 4.2.5.2. Potential Impact of Inflation on the Market Evolution
- 4.2.6. Interest Rates
- 4.2.6.1. Interest Rates and Their Impact on the Market
- 4.2.6.2. Strategies for Managing Interest Rate Risk
- 4.2.7. Commodity Flow Analysis
- 4.2.7.1. Type of Commodity
- 4.2.7.2. Origins and Destinations
- 4.2.7.3. Values and Weights
- 4.2.7.4. Modes of Transportation
- 4.2.8. Global Trade Dynamics
- 4.2.8.1. Import Scenario
- 4.2.8.2. Export Scenario
- 4.2.8.3. Trade Policies
- 4.2.8.4. Strategies for Mitigating the Risks Associated with Trade Barriers
- 4.2.8.5. Impact of Trade Barriers on the Market
- 4.2.9. War Impact Analysis
- 4.2.9.1. Russian-Ukraine War
- 4.2.9.2. Israel-Hamas War
- 4.2.10. COVID Impact / Related Factors
- 4.2.10.1. Global Economic Impact
- 4.2.10.2. Industry-specific Impact
- 4.2.10.3. Government Response and Stimulus Measures
- 4.2.10.4. Future Outlook and Adaptation Strategies
- 4.2.11. Other Indicators
- 4.2.11.1. Fiscal Policy
- 4.2.11.2. Consumer Spending
- 4.2.11.3. Gross Domestic Product
- 4.2.11.4. Employment
- 4.2.11.5. Taxes
- 4.2.11.6. Stock Market Performance
- 4.2.11.7. Cross Border Dynamics
- 4.2.1. Time Period
- 4.3. Conclusion
5. EXECUTIVE SUMMARY
6. INTRODUCTION
- 6.1. Chapter Overview
- 6.2. Introduction to Drug Delivery Devices
- 6.3. Conventional Parenteral Drug Delivery Devices
- 6.3.1. Needlestick Injuries
- 6.3.2. Incidence and Cost Burden
- 6.3.3. Prevention of Needlestick Injuries
- 6.3.4. Government Legislations for the Prevention of Needlestick Injuries
- 6.4. Emergence of Self-Administration Devices
- 6.4.1. Key Driving Factors
- 6.4.1.1. Rising Burden of Chronic Diseases
- 6.4.1.2. Healthcare Cost Savings
- 6.4.1.3. Need for Immediate Treatment in Emergency Situations
- 6.4.1.4. Growing Injectable Drugs Market
- 6.4.1.5. Need for Improving Medication Adherence
- 6.4.1. Key Driving Factors
- 6.5. Available Self-Injection Devices
- 6.5.1. Prefilled Syringes
- 6.5.2. Pen-Injectors
- 6.5.3. Needle-Free Injectors
- 6.5.4. Autoinjectors
- 6.5.5. Large Volume Wearable Injectors
- 6.6. Regulatory Considerations
- 6.6.1. Medical Devices
- 6.6.2. Drug Device Combination Products
- 6.7. Future Perspectives
7. LARGE VOLUME WEARABLE INJECTORS FOR NON-INSULIN DRUGS: MARKET LANDSCAPE
- 7.1. Chapter Overview
- 7.2. Large Volume Wearable Injectors for Non-Insulin Drugs: Overall Market Landscape
- 7.2.1. Analysis by Type of Device
- 7.2.2. Analysis by Status of Development
- 7.2.3. Analysis by Type of Drug Delivery
- 7.2.4. Analysis by Usability
- 7.2.5. Analysis by Drug Reservoir Volume
- 7.2.6. Analysis by Type of Drug Molecule
- 7.2.7. Analysis by Type of Dose
- 7.2.8. Analysis by Dose of Drug
- 7.2.9. Analysis by Mode of Injection
- 7.2.10. Analysis by Therapeutic Area
- 7.2.11. Analysis by Type of Drug Container
- 7.2.12. Analysis by Mode of Drug Filling
- 7.3. Large Volume Wearable Injectors for Non-Insulin Drugs: Developer Landscape
- 7.3.1. Analysis by Year of Establishment
- 7.3.2. Analysis by Company Size
- 7.3.3. Analysis by Location of Headquarters
- 7.3.4. Leading Players: Analysis by Number of Large Volume Wearable Injectors Developed for Non-Insulin
8. DRUG DEVICE COMBINATIONS FOR NON-INSULIN DRUGS: MARKET LANDSCAPE
- 8.1. Chapter Overview
- 8.2. Drug Device Combinations for Non-Insulin Drugs: Overall Market Landscape
- 8.2.1. Analysis by Type of Device
- 8.2.2. Analysis by Status of Development
- 8.2.3. Analysis by Type of Drug Delivery
- 8.2.4. Analysis by Usability
- 8.2.5. Analysis by Drug Reservoir Volume
- 8.2.6. Analysis by Type of Drug Molecule
- 8.2.7. Analysis by Type of Dose
- 8.2.8. Analysis by Dose of Drug
- 8.2.9. Analysis by Mode of Injection
- 8.2.10. Analysis by Therapeutic Area
- 8.2.11. Analysis by Type of Drug Container
- 8.2.12. Analysis by Mode of Drug Filling
- 8.3. Drug Device Combinations for Non-Insulin Drugs: Developer Landscape
- 8.3.1. Analysis by Year of Establishment
- 8.3.2. Analysis by Company Size
- 8.3.3. Analysis by Location of Headquarters
- 8.3.4. Device Developers: Distribution by Number of Drug Device Combination Developed
9. PRODUCT COMPETITIVENESS ANALYSIS
- 9.1. Chapter Overview
- 9.2. Assumptions / Key Parameters
- 9.3. Methodology
- 9.4. Product Competitiveness Analysis
- 9.4.1. Product Competitiveness Analysis: Large Volume Wearable Injectors for Non-Insulin Drugs
- 9.4.2. Product Competitiveness Analysis: Drug Device Combinations for Non-Insulin Drugs
- 9.4.3. Product Competitiveness Analysis: Large Volume Wearable Injectors for Insulin
10. LARGE VOLUME WEARABLE INJECTOR DEVELOPERS: COMPANY PROFILES
- 10.1. Chapter Overview
- 10.2. Key Players Developing Large Volume Wearable Injectors for Non-Insulin
- 10.2.1. CCBio
- 10.2.1.1. Company Overview
- 10.2.1.2. Product Portfolio
- 10.2.1.3. Recent Developments and Future Outlook
- 10.2.2. E3D Elcam Drug Delivery Devices
- 10.2.3. Enable Injections
- 10.2.4. Gerresheimer
- 10.2.5. Sonceboz
- 10.2.6. Weibel CDS (Acquired by SHL Medical)
- 10.2.7. West Pharmaceuticals
- 10.2.1. CCBio
- 10.3. Key Players Developing Large Volume Wearable Injectors for Insulin
- 10.3.1. CeQur
- 10.3.2. Debiotech
- 10.3.3. Eli Lilly
- 10.3.4. Insulet
- 10.3.5. Medtronic
- 10.3.6. Medtrum Technologies
- 10.3.7. PharmaSens
- 10.3.8. Roche
- 10.3.9. SOOIL Development
11. DRUG-DEVICE COMBINATIONS: DEVICE PROFILES
- 11.1. Chapter Overview
- 11.2. Neulasta(R) (pegfilgrastim) OnPro(TM) Kit
- 11.3. D-mine(R) Pump
- 11.4. Lasix(R) ONYU
- 11.5. The LUTREPULSE(R) System
- 11.6. ND0612L Next generation patch pump
- 11.7. Unnamed (Developed by Phillips Medisize)
- 11.8. FUROSCIX(R)
- 11.9. SMT-201 Pump
- 11.10. SMT-301 Pump
- 11.11. ULTOMRIS(R) Smartdose Injector (ravulizumab-cwvz)
- 11.12. EMPAVELI(R) Injector
- 11.13. SKYRIZI(R) On Body Injector (risankizumab)
- 11.14. VYALEV(TM) Pump (foscarbidopa and foslevodopa)
- 11.15. UDENYCA(R) on-body injector
- 11.16. ONAPGO(TM)
- 11.17. Remunity(R) Pump
- 11.18. G-Lasta(R) BodyPod
- 11.19. Sarclisa (isatuximab) On-Body Injector
12. PARTNERSHIPS AND COLLABORATIONS
- 12.1. Chapter Overview
- 12.2. Partnership Models
- 12.3. Large Volume Wearable Injectors: Partnerships and Collaborations
- 12.3.1. Analysis by Year of Partnership
- 12.3.2. Analysis by Type of Partnership
- 12.3.3. Analysis by Year and Type of Partnership
- 12.3.4. Analysis by Type of Partner
- 12.3.5. Analysis by Type of Device
- 12.3.6. Most Active Players: Analysis by Number of Partnerships
- 12.3.7. Analysis by Geography
- 12.3.7.1. Local and International Agreements
- 12.3.7.2. Intercontinental and Intracontinental Agreements
13. KEY ACQUISITION TARGETS
- 13.1. Chapter Overview
- 13.2. Scope and Methodology
- 13.3. Scoring Criteria and Key Assumptions
- 13.4. Potential Acquisition Targets: Non-Insulin Drug Delivery Device Developers
- 13.5. Concluding Remarks
14. PATENT ANALYSIS
- 14.1. Chapter Overview
- 14.2. Scope and Methodology
- 14.3. Large Volume Wearable Injectors: Patent Analysis
- 14.3.1. Analysis by Type of Patent
- 14.3.2. Analysis by Patent Publication Year
- 14.3.3. Analysis by Patent Application Year
- 14.3.4. Analysis of Granted Patents and Patent Applications by Publication Year
- 14.3.5. Analysis by Jurisdiction
- 14.3.6. Analysis by Type of Applicant
- 14.3.7. Analysis by Patent Age
- 14.3.8. Analysis by CPC Symbol
- 14.3.9. Most Active Players: Analysis by Number of Patents
- 14.4. Large Volume Wearable Injectors: Patent Benchmarking Analysis
- 14.4.1. Analysis by Patent Characteristics
- 14.5. Patent Valuation
- 14.6. Leading Patents by Number of Citations
15. LARGE VOLUME WEARABLE INJECTORS: LIKELY DRUG CANDIDATES
- 15.1. Chapter Overview
- 15.2. Marketed Drugs
- 15.2.1. Most Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.2.2. Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.2.3. Less Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.2.4. Least Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.3. Clinical Stage Drugs
- 15.3.1. Most Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.3.2. Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.3.3. Less Likely Candidates for Delivery via Large Volume Wearable Injectors
- 15.3.4. Least Likely Candidates for Delivery via Large Volume Wearable Injectors
16. CLINICAL TRIAL ANALYSIS
- 16.1. Chapter Overview
- 16.2. Scope and Methodology
- 16.3. Large Volume Wearable Injectors: Clinical Trial Analysis
- 16.3.1. Analysis by Trial Recruitment Status
- 16.3.2. Analysis by Trial Registration Year
- 16.3.3. Analysis of Enrolled Patient Population by Trial Registration Year
- 16.3.4. Analysis by Trial Phase
- 16.3.5. Analysis of Enrolled Patient Population by Trial Phase
- 16.3.6. Analysis by Trial Registration Year and Trial Recruitment Status
- 16.3.7. Analysis by Study Design
- 16.3.8. Analysis by Type of Sponsor / Collaborator
- 16.3.9. Analysis by Therapeutic Area
- 16.3.10. Most Active Players: Analysis by Number of Registered Trials
- 16.3.11. Most Popular Large Volume Wearable Injectors: Analysis by Number of Registered Trials
- 16.3.12. Analysis by Geography
- 16.3.12.1. Analysis by Trial Recruitment Status and Geography
- 16.3.12.2. Analysis of Enrolled Patient Population by Trial Recruitment Status and Geography
17. FUNDING AND INVESTMENT ANALYSIS
- 17.1. Chapter Overview
- 17.2. Types of Funding
- 17.3. Large Volume Wearable Injectors: Funding and Investment Analysis
- 17.3.1. Analysis by Year of Funding
- 17.3.2. Analysis of Amount Invested by Year
- 17.3.3. Analysis by Type of Funding
- 17.3.4. Analysis by Type of Device
- 17.3.5. Analysis of Amount Invested by Year and Type of Funding
- 17.3.6. Analysis of Amount Invested by Type of Device
- 17.3.7. Analysis by Target Disease Indication
- 17.3.8. Most Active Players: Analysis by Number of Funding Instances
- 17.3.9. Most Active Players: Analysis by Amount Invested
- 17.3.10. Leading Investors: Analysis by Number of Funding Instances
- 17.3.11. Analysis by Geography
18. SWOT ANALYSIS
- 18.1. Chapter Overview
- 18.2. SWOT Analysis
- 18.2.1. Strengths
- 18.2.2. Weaknesses
- 18.2.3. Opportunities
- 18.2.4. Threats
- 18.3. Large Volume Wearable Injectors: Future Growth Opportunities
- 18.3.1. Rising Focus on Self-Administration of Drugs
- 18.3.2. Possibility of Integration with Mobile Applications
- 18.3.3. Potential Life Cycle Management Tool
- 18.3.4. Potential Usability for Multiple Therapeutic Areas
19. CASE STUDY: ROLE OF CONTRACT MANUFACTURING ORGANIZATIONS IN DEVICE DEVELOPMENT SUPPLY CHAIN
- 19.1. Chapter Overview
- 19.2. Device Development Supply Chain
- 19.3. Role of Contract Manufacturing Organizations (CMOs) in Device Development
- 19.4. List of CMOs
- 19.4.1. Geographical Distribution of CMOs
- 19.5. Medical Devices Design and Development Service Providers
20. REGULATORY AND REIMBURSEMENT LANDSCAPE FOR MEDICAL DEVICES
- 20.1. Chapter Overview
- 20.2. General Regulatory and Reimbursement Guidelines for Medical Devices
- 20.3. Regulatory and Reimbursement Landscape in North America
- 20.3.1. The US Scenario
- 20.3.1.1. Regulatory Authority
- 20.3.1.2. Review / Approval Process
- 20.3.1.3. Reimbursement Landscape
- 20.3.1.3.1 . Payer Mix
- 20.3.1.3.2 . Reimbursement Process
- 20.3.2. The Canadian Scenario
- 20.3.2.1. Regulatory Authority
- 20.3.2.2. Review / Approval Process
- 20.3.2.3. Reimbursement Landscape
- 20.3.2.3.1 . Payer Mix
- 20.3.2.3.2 . Reimbursement Process
- 20.3.3. The Mexican Scenario
- 20.3.3.1. Regulatory Authority
- 20.3.3.2. Review / Approval Process
- 20.3.3.3. Reimbursement Landscape
- 20.3.3.3.1 . Payer Mix
- 20.3.1. The US Scenario
- 20.4. Regulatory and Reimbursement Landscape in Europe
- 20.4.1. Overall Scenario
- 20.4.1.1. Overall Regulatory Authority
- 20.4.1.2. Overall Review / Approval Process
- 20.4.2. The UK Scenario
- 20.4.2.1. Regulatory Authority
- 20.4.2.2. Review / Approval Process
- 20.4.2.3. Reimbursement Landscape
- 20.4.2.3.1 . Payer Mix
- 20.4.2.3.2 . Reimbursement Process
- 20.4.3. The French Scenario
- 20.4.3.1. Regulatory Authority
- 20.4.3.2. Review / Approval Process
- 20.4.3.3. Reimbursement Landscape
- 20.4.3.3.1 . Payer Mix
- 20.4.3.3.2 . Reimbursement Process
- 20.4.4. The German Scenario
- 20.4.4.1. Regulatory Authority
- 20.4.4.2. Review / Approval Process
- 20.4.4.3. Reimbursement Landscape
- 20.4.4.3.1 . Payer Mix
- 20.4.4.3.2 . Reimbursement Process
- 20.4.5. The Italian Scenario
- 20.4.5.1. Regulatory Authority
- 20.4.5.2. Review / Approval Process
- 20.4.5.3. Reimbursement Landscape
- 20.4.5.3.1 . Payer Mix
- 20.4.5.3.2 . Reimbursement Process
- 20.4.6. The Spanish Scenario
- 20.4.6.1. Regulatory Authority
- 20.4.6.2. Review / Approval Process
- 20.4.6.3. Reimbursement Landscape
- 20.4.6.3.1 . Payer Mix
- 20.4.6.3.2 . Reimbursement Process
- 20.4.1. Overall Scenario
- 20.5. Regulatory and Reimbursement Landscape in Asia-Pacific and Rest of the World
- 20.5.1. The Australian Scenario
- 20.5.1.1. Regulatory Authority
- 20.5.1.2. Review / Approval Process
- 20.5.1.3. Reimbursement Landscape
- 20.5.1.3.1 . Payer Mix
- 20.5.1.3.2 . Reimbursement Process
- 20.5.2. The Brazilian Scenario
- 20.5.2.1. Regulatory Authority
- 20.5.2.2. Review / Approval Process
- 20.5.2.3. Reimbursement Landscape
- 20.5.2.3.1. Payer Mix
- 20.5.2.3.2. Reimbursement Process
- 20.5.3. The Chinese Scenario
- 20.5.3.1. Regulatory Authority
- 20.5.3.2. Review / Approval Process
- 20.5.3.3. Reimbursement Landscape
- 20.5.3.3.1. Payer Mix
- 20.5.3.3.2. Reimbursement Process
- 20.5.1. The Australian Scenario
21. MARKET IMPACT ANALYSIS: DRIVERS, RESTRAINTS, OPPORTUNITIES AND CHALLENGES
- 21.1. Chapter Overview
- 21.2. Market Drivers
- 21.3. Market Restraints
- 21.4. Market Opportunities
- 21.5. Market Challenges
- 21.6. Conclusion
22. LARGE VOLUME WEARABLE INJECTORS MARKET
- 22.1. Chapter Overview
- 22.2. Key Assumptions and Methodology
- 22.3. Global Large Volume Wearable Injectors Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 22.3.1. Scenario Analysis
- 22.3.1.1. Conservative Scenario
- 22.3.1.2. Optimistic Scenario
- 22.3.1. Scenario Analysis
- 22.4. Global Large Volume Wearable Injectors Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 22.4.1. Scenario Analysis
- 22.4.1.1. Conservative Scenario
- 22.4.1.2. Optimistic Scenario
- 22.4.1. Scenario Analysis
- 22.5. Key Market Segmentations
23. LARGE VOLUME WEARABLE INJECTORS MARKET, BY TYPE OF DEVICE
- 23.1. Chapter Overview
- 23.2. Key Assumptions and Methodology
- 23.3. Large Volume Wearable Injectors Market: Distribution by Type of Device (By Value)
- 23.3.1. Wearable Patch Pump Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 23.3.2. Wearable Infusion Pump Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 23.4. Large Volume Wearable Injectors Market: Distribution by Type of Device (By Volume)
- 23.4.1. Wearable Patch Pump Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 23.4.2. Wearable Infusion Pump Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 23.5. Data Triangulation and Validation
24. LARGE VOLUME WEARABLE INJECTORS MARKET, BY USABILITY
- 24.1. Chapter Overview
- 24.2. Key Assumptions and Methodology
- 24.3. Large Volume Wearable Injectors Market: Distribution by Usability (By Value)
- 24.3.1. Disposable Large Volume Wearable Injectors Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 24.3.2. Reusable (Disposable Components) Large Volume Wearable Injectors Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 24.4. Large Volume Wearable Injectors Market: Distribution by Usability (By Volume)
- 24.4.1. Disposable Large Volume Wearable Injectors Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 24.4.2. Reusable (Disposable Components) Large Volume Wearable Injectors Market, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 24.5. Data Triangulation and Validation
25. LARGE VOLUME WEARABLE INJECTORS MARKET, BY THERAPEUTIC AREA
- 25.1. Chapter Overview
- 25.2. Key Assumptions and Methodology
- 25.3. Large Volume Wearable Injectors Market: Distribution by Therapeutic Area (By Value)
- 25.3.1. Large Volume Wearable Injectors Market Targeting Oncological Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 25.3.2. Large Volume Wearable Injectors Market Targeting Cardiovascular Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 25.3.3. Large Volume Wearable Injectors Market Targeting Autoimmune Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 25.3.4. Large Volume Wearable Injectors Market Targeting Neurological Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 25.3.5. Large Volume Wearable Injectors Market Targeting Other Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 25.4. Large Volume Wearable Injectors Market: Distribution by Therapeutic Area (By Volume)
- 25.4.1. Large Volume Wearable Injectors Market Targeting Oncological Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 25.4.2. Large Volume Wearable Injectors Market Targeting Cardiovascular Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 25.4.3. Large Volume Wearable Injectors Market Targeting Autoimmune Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 25.4.4. Large Volume Wearable Injectors Market Targeting Neurological Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 25.4.5. Large Volume Wearable Injectors Market Targeting Other Disorders, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 25.5. Data Triangulation and Validation
26. LARGE VOLUME WEARABLE INJECTORS MARKET, BY GEOGRAPHICAL REGIONS
- 26.1. Chapter Overview
- 26.2. Key Assumptions and Methodology
- 26.3. Large Volume Wearable Injectors Market: Distribution by Geographical Regions (By Value)
- 26.3.1. Large Volume Wearable Injectors Market in North America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 26.3.2. Large Volume Wearable Injectors Market in Europe, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 26.3.3. Large Volume Wearable Injectors Market in Asia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 26.3.4. Large Volume Wearable Injectors Market in Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 26.3.5. Large Volume Wearable Injectors Market in Middle East and North Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Value)
- 26.4. Large Volume Wearable Injectors Market : Distribution by Geographical Regions (By Volume)
- 26.4.1. Large Volume Wearable Injectors Market in North America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 26.4.2. Large Volume Wearable Injectors Market in Europe, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 26.4.3. Large Volume Wearable Injectors Market in Asia, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 26.4.4. Large Volume Wearable Injectors Market in Latin America, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 26.4.5. Large Volume Wearable Injectors Market in Middle East and North Africa, Historical Trends (Since 2022) and Forecasted Estimates (Till 2035) (By Volume)
- 26.5. Market Dynamics Assessment
- 26.5.1. Penetration Growth (P-G) Matrix
- 26.5.2. Market Movement Analysis
- 26.6. Data Triangulation and Validation


