|
시장보고서
상품코드
2101960
자동차 배기 시스템 시장 기회, 성장 촉진요인, 업계 동향 분석 및 예측(2026-2035년)Automotive Exhaust System Market Opportunity, Growth Drivers, Industry Trend Analysis, and Forecast 2026 - 2035 |
||||||

세계의 자동차 배기 시스템 시장은 2025년에 394억 달러 규모에 달하고, CAGR 4.9%로 성장하여 2035년까지 652억 달러에 달할 것으로 예측됩니다.
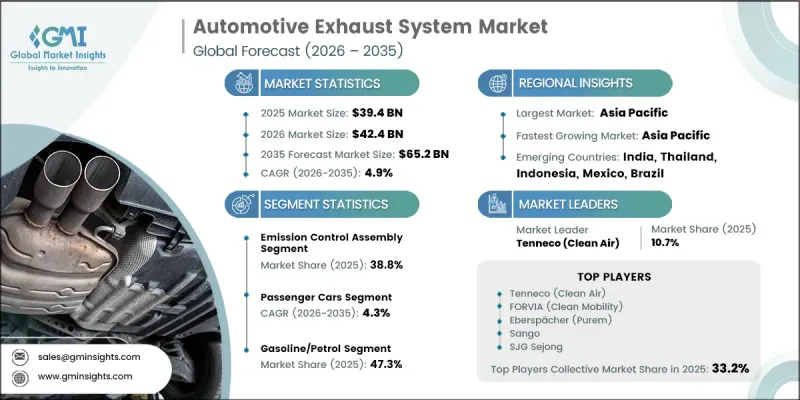
시장 확대는 주요 자동차 시장에서 도입되고 있는 점점 더 엄격해지는 자동차 배기가스 규제에 힘입고 있으며, 이로 인해 제조사들은 더욱 첨단 배기 기술을 채택하도록 촉진되고 있습니다. 자동차 제조사들이 진화하는 환경 기준을 충족하기 위해 첨단 배기가스 제어 시스템을 도입함에 따라, 규제 준수는 계속해서 업계 성장을 좌우하는 가장 영향력 있는 요인으로 남아 있습니다. 상용차 배기 시스템은 승용차용보다 가격이 상당히 높기 때문에 상용차는 전체 시장 규모에 크게 기여하고 있습니다. 동시에, 화물 운송 활동의 증가가 첨단 배기 솔루션을 탑재한 대형 차량에 대한 수요를 뒷받침하고 있습니다. 또 다른 중요한 성장 요인은 전 세계적으로 내연기관 차량(ICE 차량)의 보유 대수가 노후화되고 있다는 점이며, 이로 인해 애프터마켓을 통해 배기 부품 교체 수요가 꾸준히 발생하고 있습니다. 전기자동차로의 전환이 신차 내연기관차 생산에 서서히 영향을 미치고 있는 반면, 기존 차량의 방대한 보유 대수로 인해 배기가스 관련 부품의 유지보수 및 교체 수요는 계속해서 존재하고 있으며, 이는 OEM 및 애프터마켓 양쪽 채널에서 사업을 전개하는 제조사에게 장기적인 비즈니스 기회를 창출하고 있습니다.
| 시장 범위 | |
|---|---|
| 시작 연도 | 2025년 |
| 예측 기간 | 2026-2035년 |
| 초기 시장 규모 | 394억 달러 |
| 예측액 | 652억 달러 |
| CAGR | 4.9% |
자동차 배기 시스템 시장은 엄격한 환경 규제를 충족하면서 차량 성능 향상에 기여하는 효율적인 배기가스 관리 기술에 대한 수요가 증가함에 따라 계속해서 혜택을 받고 있습니다. 최신 배기 시스템에는 유해 배기가스 저감, 연비 향상 및 엔진 작동 최적화를 목적으로 하는 여러 구성요소가 통합되어 있습니다. 소재 기술, 시스템 내구성, 열 관리 및 제조 공정의 지속적인 발전 덕분에 공급업체들은 더 가볍고, 더 효율적이며 고성능의 배기 어셈블리를 개발할 수 있게 되었습니다. 또한, 첨단 배기가스 저감 기술에 대한 투자 증가와 노후화된 배기 부품의 지속적인 교체가 업계를 뒷받침하고 있으며, 이는 전 세계 시장에서 안정적인 수익 기회를 지속적으로 창출하고 있습니다.
배기가스 제어 어셈블리 부문은 2025년에 38.8%의 점유율을 차지했으며, 2026년부터 2035년까지 연평균 성장률(CAGR) 6.4%로 성장할 것으로 전망됩니다. 이 부문의 성장은 제조사가 더욱 엄격해진 환경 규제를 준수할 수 있도록 설계된 첨단 배기가스 제어 기술의 탑재 증가에 힘입고 있습니다. 자동차 제조사가 배기가스 성능 향상과 규제 준수를 우선시함에 따라 경·중·대형 차량을 불문하고 첨단 배기 후처리 시스템의 채택이 확대되고 있으며, 수요는 계속해서 강세를 보이고 있습니다.
승용차 부문은 2025년에 65.2%의 점유율을 차지했으며, 2026년부터 2035년까지 연평균 성장률(CAGR) 4.3%로 성장할 것으로 전망됩니다. 승용차의 생산 대수가 많기 때문에 배기 매니폴드, 촉매 변환기, 머플러 및 첨단 배기가스 제어 시스템에 대한 수요는 계속해서 견조합니다. 연비 효율과 차량 배기가스 저감에 대한 관심이 높아짐에 따라, 승용차 모델 전반에 걸쳐 더욱 첨단 배기 기술의 도입이 진행되고 있습니다. 또한, 스포츠 유틸리티 차량(SUV)의 생산 대수가 증가하고 있는 점도 고성능 배기 시스템에 대한 수요 확대에 기여하고 있습니다.
2025년, 북미 자동차 배기 시스템 시장 규모는 77억 달러에 달했습니다. 이 지역은 확고한 자동차 제조 산업과 소형차의 견조한 생산 대수에 힘입어 배기 부품 및 배기가스 제어 시스템에 대한 지속적인 수요를 뒷받침하고 있습니다. 점점 더 엄격해지는 환경 규제의 지속적인 도입으로 인해 첨단 배기 후처리 기술의 채택이 더욱 촉진되고 있습니다. 또한, 상용차 활동의 증가와 애프터마켓용 배기 부품에 대한 견조한 교체 수요가 예측 기간 동안 시장의 꾸준한 확장을 뒷받침할 것으로 전망됩니다.
자주 묻는 질문
목차
제1장 조사 방법
제2장 주요 요약
제3장 업계 인사이트
제4장 경쟁 구도
제5장 시장 추정 및 예측 : 구성요소별, 2022-2035년
제6장 시장 추정 및 예측 : 차량별, 2022-2035년
제7장 시장 추정 및 예측 : 연료별, 2022-2035년
제8장 시장 추정 및 예측 : 판매 채널별, 2022-2035년
제9장 시장 추정 및 예측 : 지역별, 2022-2035년
제10장 기업 개요
KSM 26.08.05The Global Automotive Exhaust System Market was valued at USD 39.4 billion in 2025 and is estimated to grow at a CAGR of 4.9% to reach USD 65.2 billion by 2035.
Market expansion is driven by increasingly stringent vehicle emission regulations introduced across major automotive markets, encouraging manufacturers to adopt more advanced exhaust technologies. Regulatory compliance continues to be the most influential factor shaping industry growth, as automakers integrate sophisticated emission control systems to meet evolving environmental standards. Commercial vehicles contribute significantly to overall market value because exhaust systems for these vehicles command considerably higher prices than those used in passenger cars. At the same time, rising freight transportation activity is supporting demand for heavy-duty vehicles equipped with advanced exhaust solutions. Another important growth driver is the aging global fleet of internal combustion engine vehicles, which continues to generate consistent demand for replacement exhaust components through the aftermarket. While the transition toward electric vehicles is gradually affecting new ICE vehicle production, the large installed base of conventional vehicles continues to require maintenance and replacement of emission-related components, creating long-term opportunities for manufacturers operating in both original equipment and aftermarket channels.
| Market Scope | |
|---|---|
| Start Year | 2025 |
| Forecast Year | 2026-2035 |
| Start Value | $39.4 Billion |
| Forecast Value | $65.2 Billion |
| CAGR | 4.9% |
The automotive exhaust system market continues to benefit from the growing need for efficient emission management technologies that help improve vehicle performance while meeting strict environmental requirements. Modern exhaust systems integrate multiple components designed to reduce harmful emissions, improve fuel efficiency, and optimize engine operation. Continuous advancements in material technologies, system durability, thermal management, and manufacturing processes are enabling suppliers to develop lighter, more efficient, and higher-performing exhaust assemblies. The industry is also supported by increasing investments in advanced emission reduction technologies and the ongoing replacement of aging exhaust components, which continues to generate steady revenue opportunities across global markets.
The emission control assembly segment held a 38.8% share in 2025 and is anticipated to grow at a CAGR of 6.4% between 2026 and 2035. Growth in this segment is supported by the increasing installation of advanced emission control technologies designed to help manufacturers comply with stricter environmental regulations. The rising adoption of sophisticated exhaust after-treatment systems across light-, medium-, and heavy-duty vehicles continues to strengthen demand as automakers prioritize improved emission performance and regulatory compliance.
The passenger cars segment held 65.2% share in 2025 and is projected to grow at a CAGR of 4.3% from 2026 to 2035. The high production volume of passenger vehicles continues to generate substantial demand for exhaust manifolds, catalytic converters, mufflers, and advanced emission control systems. Increasing emphasis on fuel efficiency and lower vehicle emissions is encouraging the integration of more advanced exhaust technologies across passenger vehicle models. In addition, growing production of sport utility vehicles is contributing to higher demand for high-performance exhaust systems.
North America Automotive Exhaust System Market accounted for USD 7.7 billion in 2025. The region benefits from a well-established automotive manufacturing industry and strong production volumes of light-duty vehicles, supporting sustained demand for exhaust components and emission control systems. Continued implementation of increasingly stringent environmental regulations is encouraging greater adoption of advanced exhaust after-treatment technologies. Furthermore, rising commercial vehicle activity and strong replacement demand for aftermarket exhaust components are expected to support steady market expansion throughout the forecast period.
Key players operating in the global automotive exhaust system industry include FORVIA, Yutaka Giken, Tenneco, Sejong, Futaba, Sango, and Eberspacher. Companies operating in the automotive exhaust system market are focusing on technological innovation, product development, and strategic partnerships to strengthen their competitive position. Manufacturers are investing in lightweight materials, advanced emission control technologies, and high-efficiency exhaust systems that comply with evolving environmental regulations while improving vehicle performance. Businesses are also expanding their aftermarket product portfolios to address the growing replacement demand generated by aging vehicle fleets. Strengthening relationships with automotive manufacturers through long-term supply agreements and increasing production capabilities in high-growth regions remain important growth strategies.
Table of Contents
Chapter 1 Methodology
- 1.1 Research approach
- 1.2 Quality Commitments
- 1.2.1 GMI AI policy & data integrity commitment
- 1.2.1.1 Source consistency protocol
- 1.2.1 GMI AI policy & data integrity commitment
- 1.3 Research Trail & Confidence Scoring
- 1.3.1 Research Trail Components
- 1.3.2 Scoring Components
- 1.4 Data Collection
- 1.4.1 Partial list of primary sources
- 1.5 Data mining sources
- 1.5.1 Paid sources
- 1.5.1.1 Sources, by region
- 1.5.1 Paid sources
- 1.6 Base estimates and calculations
- 1.6.1 Base year calculation
- 1.7 Forecast model
- 1.7.1 Quantified market impact analysis
- 1.7.1.1 Mathematical impact of growth parameters on forecast
- 1.7.1 Quantified market impact analysis
- 1.8 Research transparency addendum
- 1.8.1 Source attribution framework
- 1.8.2 Quality assurance metrics
- 1.8.3 Our commitment to trust
Chapter 2 Executive Summary
- 2.1 Industry 360° synopsis
- 2.2 Key market trends
- 2.2.1 Regional
- 2.2.2 Component
- 2.2.3 Vehicle
- 2.2.4 Fuel
- 2.2.5 Sales Channel
- 2.3 TAM analysis, 2026-2035
- 2.4 CXO perspectives: Strategic imperatives
Chapter 3 Industry Insights
- 3.1 Industry ecosystem analysis
- 3.1.1 Supplier landscape
- 3.1.2 Profit margin
- 3.1.3 Cost structure
- 3.1.4 Value addition at each stage
- 3.1.5 Factor affecting the value chain
- 3.1.6 Disruptions
- 3.2 Industry impact forces
- 3.2.1 Growth drivers
- 3.2.1.1 Tightening global emission regulations
- 3.2.1.2 Commercial vehicle fleet growth
- 3.2.1.3 Aging vehicle parc expansion
- 3.2.1.4 Demand for lightweight exhaust systems
- 3.2.2 Industry pitfalls and challenges
- 3.2.2.1 Rising BEV adoption impact
- 3.2.2.2 Precious metal price volatility
- 3.2.3 Market opportunities
- 3.2.3.1 Hybrid vehicle transition demand
- 3.2.3.2 Aftermarket digitalization growth potential
- 3.2.3.3 Exhaust heat recovery systems
- 3.2.3.4 Hydrogen ICE adoption emergence
- 3.2.1 Growth drivers
- 3.3 Growth potential analysis
- 3.4 Technology and innovation landscape
- 3.4.1 Current technological trends
- 3.4.2 Emerging technologies
- 3.5 Pricing Analysis (Driven by primary research)
- 3.5.1 Historical Price Trend Analysis
- 3.5.2 Pricing Strategy by Player Type (Premium / Value / Cost-plus)
- 3.6 Cost breakdown analysis
- 3.7 Regulatory landscape
- 3.7.1 North America
- 3.7.1.1 U.S. EPA Emission Standards
- 3.7.1.2 Environment Canada Vehicle Emission Regulations
- 3.7.2 Europe
- 3.7.2.1 Euro 7 Standards
- 3.7.2.2 European Environment Agency (EEA)
- 3.7.3 Asia Pacific
- 3.7.3.1 China VI / China VII Regulations
- 3.7.3.2 Bharat Stage VI (India)
- 3.7.4 Latin America
- 3.7.4.1 PROCONVE Emission Standards (Brazil)
- 3.7.4.2 Mexico Vehicle Emission Regulations
- 3.7.5 Middle East & Africa
- 3.7.5.1 Saudi Vehicle Emission Standards
- 3.7.5.2 UAE Environmental Regulations
- 3.7.1 North America
- 3.8 Porter's analysis
- 3.9 PESTEL analysis
- 3.10 Patent analysis (Driven by primary research)
- 3.11 Impact of AI & Generative AI on the Market
- 3.11.1 AI-driven disruption of existing business models
- 3.11.2 Gen AI use cases & adoption roadmap by segment
- 3.11.3 Risks, limitations & regulatory considerations
- 3.12 Sustainability and environmental aspects
- 3.12.1 Sustainable practices
- 3.12.2 Waste reduction strategies
- 3.12.3 Energy efficiency in production
- 3.12.4 Eco-friendly initiatives
- 3.12.5 Carbon footprint considerations
- 3.13 Forecast assumptions & scenario analysis (Driven by primary research)
- 3.13.1 Base Case - key macro & industry variables driving CAGR
- 3.13.2 Optimistic Scenarios - Favorable macro and industry tailwinds
- 3.13.3 Pessimistic Scenario - Macroeconomic slowdown or industry headwinds
Chapter 4 Competitive Landscape, 2025
- 4.1 Introduction
- 4.2 Company market share analysis
- 4.2.1 North America
- 4.2.2 Europe
- 4.2.3 Asia Pacific
- 4.2.4 LATAM
- 4.2.5 MEA
- 4.3 Competitive analysis of major market players
- 4.4 Competitive positioning matrix
- 4.5 Key developments
- 4.5.1 Mergers & acquisitions
- 4.5.2 Partnerships & collaborations
- 4.5.3 New product launches
- 4.5.4 Expansion plans and funding
- 4.6 Company tier benchmarking
- 4.6.1 Tier classification criteria & qualifying thresholds
- 4.6.2 Tier positioning matrix by revenue, geography & innovation
Chapter 5 Market Estimates & Forecast, By Component, 2022 - 2035 ($Mn, Units)
- 5.1 Key trends
- 5.2 Exhaust manifold assembly
- 5.3 Emission control assembly
- 5.3.1 Catalytic converter
- 5.3.2 DOC (Diesel oxidation catalyst)
- 5.3.3 DPF (Diesel particulate filter)
- 5.3.4 GPF (Gasoline particulate filter)
- 5.3.5 SCR (Selective catalytic reduction)
- 5.3.6 LNT (Lean NOx trap)
- 5.4 Muffler & resonator assembly
- 5.5 Exhaust pipes & tailpipe assembly
Chapter 6 Market Estimates & Forecast, By Vehicle, 2022 - 2035 ($Mn, Units)
- 6.1 Key trends
- 6.2 Passenger Cars
- 6.2.1 Sedan
- 6.2.2 Hatchback
- 6.2.3 SUV
- 6.3 Commercial vehicles
- 6.3.1 Light commercial vehicles (LCV)
- 6.3.2 Medium commercial vehicles (MCV)
- 6.3.3 Heavy commercial vehicles (HCV)
Chapter 7 Market Estimates & Forecast, By Fuel, 2022 - 2035 ($Mn, Units)
- 7.1 Key trends
- 7.2 Gasoline/Petrol
- 7.3 Diesel
- 7.4 Alternative fuels
Chapter 8 Market Estimates & Forecast, By Sales Channel, 2022 - 2035 ($Mn, Units)
- 8.1 Key trends
- 8.2 OEM
- 8.3 Aftermarket
Chapter 9 Market Estimates & Forecast, By Region, 2022 - 2035 ($Mn, Units)
- 9.1 Key trends
- 9.2 North America
- 9.2.1 U.S.
- 9.2.2 Canada
- 9.3 Europe
- 9.3.1 Germany
- 9.3.2 UK
- 9.3.3 France
- 9.3.4 Italy
- 9.3.5 Spain
- 9.3.6 Sweden
- 9.3.7 Switzerland
- 9.3.8 Netherlands
- 9.4 Asia Pacific
- 9.4.1 China
- 9.4.2 India
- 9.4.3 Japan
- 9.4.4 South Korea
- 9.4.5 Australia
- 9.4.6 Singapore
- 9.4.7 Malaysia
- 9.5 Latin America
- 9.5.1 Brazil
- 9.5.2 Mexico
- 9.5.3 Argentina
- 9.6 MEA
- 9.6.1 South Africa
- 9.6.2 Saudi Arabia
- 9.6.3 UAE
Chapter 10 Company Profiles
- 10.1 Global players
- 10.1.1 Benteler
- 10.1.2 BOSAL
- 10.1.3 Eberspacher
- 10.1.4 FORVIA
- 10.1.5 Friedrich Boysen
- 10.1.6 Katcon
- 10.1.7 Marelli
- 10.1.8 Tenneco
- 10.2 Regional players
- 10.2.1 Dinex
- 10.2.2 Futaba
- 10.2.3 Hirotec
- 10.2.4 Sango
- 10.2.5 Sejong
- 10.2.6 Sharda Motor
- 10.2.7 Weifu
- 10.2.8 Yutaka
- 10.3 Emerging players
- 10.3.1 Airi Auto Technology
- 10.3.2 Eminox
- 10.3.3 REMUS
- 10.3.4 Tata AutoComp