|
시장보고서
상품코드
2097358
자동차 배기 시스템 시장 : 시장 점유율 분석, 산업 동향 및 통계 데이터, 성장 예측(2026-2031년)Automotive Exhaust System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
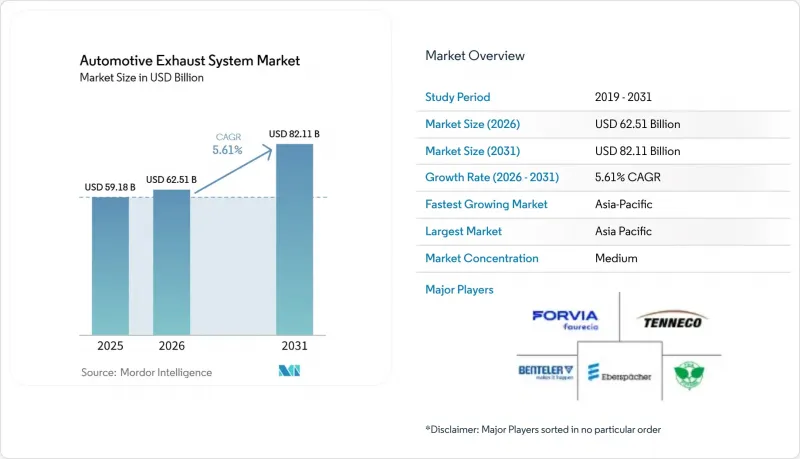
에 의하면, 자동차 배기 시스템 시장 규모는 2025년 591억 8,000만 달러로 평가되었고, 2025년에는 625억 1,000만 달러로 추정되며, 2025-2031년 CAGR 5.61%로 성장을 지속하여, 2031년에는 821억 1,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 컴포넌트별(배기 매니폴드 등), 연료 유형별(가솔린 등), 차종별(이륜차 등), 시스템 유형별(싱글 등), 판매 채널별(OEM, 애프터마켓) 및 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 및 수량(대수)으로 제시되어 있습니다.
세계의 자동차 배기 시스템 시장 동향 및 인사이트
더욱 엄격해진 유로 7/중국 VII 배기가스 규제
2027년 중반부터 유로 7에 따른 소형차 규제가 시행되며, 이어 2029년 중반에는 대형차 규제가 시행됩니다. 이러한 규제에서는 나노미터 규모의 미세 입자를 대상으로 한 PN10 측정이 도입됩니다. 또한, 차량 내 지속적인 모니터링이 의무화됩니다. 그 결과, 촉매 변환기 및 입자상 물질 필터는 광범위한 환경 조건에서 효율적으로 작동해야 합니다. 한편, 가까운 시일 내에 도입될 것으로 예상되며 수년에 걸쳐 단계적으로 시행될 예정인 중국의 ‘China VII’ 기준은 NOx 배출 제한을 대폭 강화하는 것을 목적으로 하고 있습니다. 이러한 변화로 인해 각 OEM 업체들은 듀얼 SCR 레이아웃의 채택과 멀티 가스 산소 센서의 통합을 추진해야 하는 상황에 놓여 있습니다.
터보 가솔린 승용차의 급속한 보급
최근 내연기관을 탑재한 차량의 대다수는 터보차저가 장착된 직분사 가솔린 엔진을 채택하고 있습니다. 이러한 엔진은 배기 엔탈피가 높기 때문에 스테인리스제 매니폴드, 세라믹 코팅, 그리고 극히 짧은 시간 내에 활성화되는 촉매의 사용이 필수적입니다. 최근 후타바는 토요타 및 렉서스 전용 스테인리스제 매니폴드의 양산을 시작했습니다. 동시에 NGK는 인도에서 향후 시행될 배기가스 규제를 준수하는 코르디아라이트(CordiaLite) 소재의 가솔린 미립자 필터(GPF) 공급 계약을 체결했습니다. 또한, 과도기적 공연비 제어에 현재 표준으로 채택되고 있는 와이드밴드 람다 센서는 극히 높은 온도에도 견딜 수 있습니다.
BEV 파워트레인의 보급 가속화
최근 배터리식 전기차(BEV)는 전 세계 경차 판매에서 큰 성장세를 보이고 있으며, 중국이 신에너지차 도입을 주도하고 있습니다. 미국에서는 연방 세액 공제 기한 만료에 따라 BEV 수요가 소폭 감소했으나, 캘리포니아주는 미래를 향한 야심찬 ‘배기관 배출가스 제로’ 목표 달성을 위해 계속해서 노력하고 있습니다. 후타바와 같은 공급업체들은 향후 몇 년 동안 매출이 크게 감소할 것으로 예상하고 있습니다. 이에 대응하기 위해 각사는 전기차용 배터리 냉각 플레이트 및 열 모듈로 투자를 전환하고 있습니다.
부문 분석
2025년에는 촉매 변환기가 총 매출의 34.46%를 차지했으며, 배기가스 제어 분야에서의 우위를 뚜렷이 드러낼 전망입니다. 지속적인 람다 값 및 NOx 모니터링을 중시하는 유로 7 및 중국 VII 규제의 영향으로, 산소 센서는 연평균 성장률(CAGR) 5.63%로 성장을 주도할 것으로 예측됩니다. 극한 온도를 견딜 수 있도록 설계된 보쉬의 와이드밴드 유닛은 불과 몇 초 만에 점화를 달성합니다. 듀얼 SCR 레이아웃에 따른 감지 지점의 확대에 따라, 자동차 배기 시스템에서 산소 센서에 대한 수요는 꾸준히 증가하고 있습니다. 입자 수에 관한 규제가 강화됨에 따라, 터보 가솔린 차량에서 가솔린 미립자 필터의 보급이 확대되고 있습니다. 머플러와 파이프는 상품화 추세가 가속화되고 있는 반면, 프리미엄 브랜드는 티타늄 테일파이프를 채택하여 차별화를 꾀하고 있습니다.
터보 가솔린 차량의 열적 요건을 충족하기 위해 주철 대신 스테인리스 매니폴드가 채택되고 있습니다. 중요한 진전으로, 후타바가 도요타 및 렉서스용으로 출시한 최신 제품은 차량 1대당 대폭적인 경량화를 실현했습니다. 개발 중인 모듈식 머플러는 금형 비용 절감이 기대되지만, 그 내구성에 대해서는 아직 입증되지 않았습니다. 저부가가치로 간주되기 쉬운 테일파이프도 슈퍼카용 트림에서는 티타늄 제품으로 업그레이드되어 놀라운 프리미엄 가격을 실현하고 있습니다. 규제가 실시간 준수(real-time compliance)로 전환되는 가운데, 촉매 및 센서는 부가가치를 높이는 반면, 프레스 성형 부품의 이익률은 축소될 전망입니다.
가솔린 차량은 터보 DI 채택률이 70%에 달한 점도 뒷받침되어, 2025년 매출의 58.71%를 차지했습니다. 가솔린 미립자 필터의 의무화로 인해 촉매 수요가 더욱 확대되고 있습니다. 대체 연료(CNG, LPG, 바이오메탄)는 5.73%라는 가장 높은 연평균 성장률(CAGR)을 나타낼 전망입니다. 인도의 CNG 차량 수는 매년 현저한 증가세를 보이며 시장을 주도하고 있습니다. 주요 촉진요인으로는 메탄 산화를 위해 미세 조정된 삼원 촉매와 적응형 람다 센서 등이 꼽힙니다.
LEZ(저배출구역) 규제로 인해 자동차 배기 시스템 시장에서 디젤의 점유율은 감소 추세를 보이고 있지만, 비도로용 차량 및 대형 차량에서는 여전히 중요한 위치를 차지하고 있습니다. 이러한 차량에는 특히 DPF와 결합된 듀얼 도징 SCR과 같은 첨단 아키텍처가 요구됩니다. 가까운 미래에 하이브리드 차량이 전 세계 판매 대수의 상당 부분을 차지할 것으로 예상되는 가운데, 내연기관의 중요성은 여전히 지속되고 있습니다. 이러한 추세에 따라 열용량이 낮고 신속하게 점화할 수 있는 솔루션에 대한 수요가 증가하고 있으며, 이는 콜드 스타트 시 발생하는 배기가스 급증을 효과적으로 억제하고 있습니다.
지역별 분석
아시아태평양은 2025년 매출의 36.75%를 차지한 것으로 평가되었으며, 2031년까지 연평균 성장률(CAGR) 5.71%를 기록할 전망입니다. 중국의 경차 생산 규모가 크고, 인도에서 CNG 도입이 확대되며, 비도로용 차량 부문의 판매가 호조를 보이는 점은 단기적인 성장이 기대됨을 시사합니다. 중국의 새로운 배기가스 기준 도입으로 촉매 및 센서 수요가 증가하는 한편, 인도에서 도입 예정인 규제에서는 규제 대상 오염 물질이 암모니아 및 이산화질소까지 확대됩니다. 하이브리드차 시장에서 일본의 확고한 입지는 간헐 운전용 배기 시스템에 대한 안정적인 수요를 보장하고 있습니다. 한국에서는 유럽 배기가스 기준 준수 및 현대자동차(현대)와 기아자동차(기아)의 하이브리드차에 대한 노력이 지역 시장의 안정을 뒷받침하고 있습니다.
유럽은 세계 판매에서 계속해서 매우 중요한 역할을 하고 있습니다. 이번 10년 후반에 도입될 예정인 ‘유로 7’ 기준에서는 정밀한 입자 계수 및 연속 모니터링과 같은 더욱 엄격한 조치가 의무화됩니다. 이러한 변화로 인해 최첨단 촉매 및 입자 필터에 대한 수요가 확대될 전망입니다. 수많은 저공해 구역의 확대에 따라 구형 차량의 교체 속도가 빨라지고 있으며, 사후 장착 개조 기회가 확대되고 있습니다. 배터리식 전기차(BEV)가 증가하는 한편, 제조업체들이 주행 거리 제한이나 수익성 등의 과제를 해결해 나가는 과정에서 하이브리드 차량은 여전히 중요한 위치를 차지하고 있습니다. 독일은 에버스파허, 벤텔러, 포시아와 같은 주요 공급업체를 보유하고 있어 이 지역의 견고한 통합 역량을 돋보이게 하고 있습니다.
북미는 생산 대수가 소폭 감소했음에도 불구하고 주요 수익원으로 두각을 나타내고 있습니다. 연방 정부의 정책 전환으로 인해 배터리 전기차 수요에 변동이 나타나고 있습니다. 그러나 캘리포니아주의 확고한 제로 배출 규제가 명확한 장기적 방향을 제시하고 있습니다. 테네코의 멕시코 밸브 생산 확대나 벤텔러의 사우스캐롤라이나주 배기 시스템 제조 설비 업그레이드 등 주목할 만한 투자는 각 제조업체들이 내연기관 플랫폼에 주력하고 있음을 뒷받침하고 있습니다. 촉매 변환기 도난 건수는 감소 추세에 있지만, 교체에 드는 비용은 여전히 막대한 수준입니다.
기타 혜택 :
- Excel 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 분석 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장률 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.08.07According to Mordor Intelligence, the automotive exhaust systems market size is expected to grow from USD 59.18 billion in 2025 to USD 62.51 billion in 2025 and is forecast to reach USD 82.11 billion by 2031 at 5.61% CAGR over 2025-2031.
This report is Segmented by Component (Exhaust Manifold and More), Fuel Type (Gasoline and More), Vehicle Type (Two-Wheeler and More), System Type (Single and More), Sales Channel (OEM and Aftermarket), and Geography. The Market Forecasts are Provided in Value (USD) and Volume (Units).
Global Automotive Exhaust System Market Trends and Insights
Stricter Euro 7 / China VII Emission Norms
Starting in mid-2027, Euro 7 will enforce light-duty regulations, followed by heavy-duty rules in mid-2029. These regulations introduce the PN10 measurement, targeting particles as small as nanometer-scale sizes. Additionally, they mandate continuous on-board monitoring. As a result, catalytic converters and particulate filters must now operate efficiently in a wide range of ambient conditions. Meanwhile, China's "China VII" standards, anticipated in the near future and set for a phased rollout over several years, aim to significantly tighten NOx limits. This shift is nudging OEMs towards adopting dual-SCR layouts and integrating multi-gas oxygen sensors.
Rapid Growth in Turbo-Gasoline Passenger Cars
In recent years, a significant majority of vehicles with combustion engines have been equipped with turbocharged direct-injection gasoline engines. These engines, with their heightened exhaust enthalpy, necessitate the use of stainless manifolds, ceramic coatings, and catalysts that activate in a very short time. Recently, Futaba commenced mass production of stainless manifolds specifically for Toyota and Lexus. Concurrently, NGK secured a contract to supply cordierite Gasoline Particulate Filters (GPF) in India, aligning with the country's upcoming emission regulations. Additionally, wideband lambda sensors, now standard for transient air-fuel control, can withstand extremely high temperatures.
Accelerating BEV Power-Train Penetration
In recent years, battery electric vehicles (BEVs) have gained significant traction in global light-vehicle sales, with China leading the market in new-energy vehicle adoption. While demand for BEVs in the U.S. experienced a slight decline following the expiration of a federal tax credit, California remains committed to its ambitious zero-tailpipe emissions target for the future. Suppliers, such as Futaba, are anticipating a substantial revenue shortfall in the coming years. In response, they are shifting their investments towards battery cooling plates and thermal modules for electric vehicles.
Other drivers and restraints analyzed in the detailed report include:
- Urban Low-Emission Zones Expansion
- OEM Shift to Lightweight Stainless & Titanium Alloys
- Raw-Material Price Volatility (Ni, Mo)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, catalytic converters accounted for 34.46% of total revenue, highlighting their dominance in emissions control. Driven by Euro 7 and China VII mandates emphasizing continuous lambda and NOx monitoring, oxygen sensors are projected to spearhead growth with a 5.63% CAGR. Bosch's wideband units, designed to endure extreme temperatures, achieve ignition in mere seconds. As dual-SCR layouts expand their sensing points, the demand for oxygen sensors in automotive exhaust systems is on a steady rise. Stricter limits on particulate numbers are paving the way for wider adoption of gasoline particulate filters in turbo-gasoline fleets. While mufflers and pipes trend towards commoditization, premium brands are distinguishing themselves with titanium tailpipes.
Stainless manifolds are now taking the place of cast iron to meet the thermal demands of turbo-gasoline. In a significant development, Futaba's latest launches for Toyota and Lexus are realizing notable weight reductions per vehicle. Although modular mufflers under development promise tooling savings, their durability remains unproven. Tailpipes, often viewed as low-value, are being upgraded to titanium for supercar trims, commanding impressive premiums. With a regulatory shift towards real-time compliance, catalysts and sensors stand to gain added value, while stamped components face shrinking margins.
Gasoline vehicles delivered 58.71% of 2025 revenue, aided by 70% turbo-DI adoption. Mandatory gasoline particulate filters reinforce catalyst pull-through. Alternate fuels-CNG, LPG, and biomethane-will post the highest CAGR of 5.73%. India's CNG fleet is experiencing significant annual growth, driving the market forward. Key enablers include three-way catalysts fine-tuned for methane oxidation and adaptive lambda sensors.
While diesel's share in the automotive exhaust systems market is declining due to LEZ bans, it still holds a notable position in off-highway and heavy vehicles. These vehicles require advanced architectures, specifically the dual-dosing SCR combined with DPF. As hybrids are expected to account for a substantial portion of global sales in the near future, the relevance of combustion persists. This trend bolsters the demand for solutions that are low in heat mass and quick to light off, effectively mitigating cold-start spikes.
Complete Report Scope:
- By Component
- Exhaust Manifold
- Muffler
- Catalytic Converter
- Exhaust Pipes
- Oxygen Sensor
- Tailpipe
- By Fuel Type
- Gasoline
- Diesel
- Alternate Fuels (Biofuels, CNG, LPG)
- By Vehicle Type
- Two-Wheeler
- Passenger Cars
- Light Commercial Vehicles (LCVs)
- Medium and Heavy Commercial Vehicles (HCVs)
- Buses and Coaches
- Off-highway Vehicles
- By System Type
- Single Exhaust System
- Dual Exhaust System
- Cat-Back Exhaust System
- Header Exhaust System
- By Sales Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific generated 36.75% of 2025 revenue and will post a 5.71% regional CAGR to 2031. China's significant light-vehicle production, India's growing adoption of CNG, and strong off-highway sales indicate positive near-term growth. The introduction of China's new emission standards will increase the need for catalysts and sensors, while India's upcoming regulations will expand pollutant coverage to include ammonia and nitrous oxide. Japan's strong presence in the hybrid vehicle market ensures steady demand for intermittent-duty exhaust systems. In South Korea, the alignment with European emission standards and the hybrid vehicle initiatives by Hyundai and Kia support regional market stability.
Europe continues to play a pivotal role in global sales. The forthcoming Euro 7 standards, set to roll out later this decade, will enforce stricter measures like advanced particulate counting and continuous monitoring. This shift is poised to boost the demand for cutting-edge catalysts and particulate filters. With the rise of numerous low-emission zones, there's a swift push to replace older vehicles, opening doors for retrofitting opportunities. While battery electric vehicles are on the rise, hybrids still hold a crucial position as manufacturers navigate challenges like range limitations and profitability. Germany's prominence is further highlighted by its hosting of major suppliers like Eberspacher, Benteler, and Faurecia, showcasing the region's robust integration capabilities.
North America stands out as a major revenue source, even as production sees a slight dip. Federal policy shifts have led to fluctuations in the demand for battery electric vehicles. Yet, California's steadfast zero-emission mandate charts a clear long-term course. Noteworthy investments, including Tenneco's valve production expansion in Mexico and Benteler's exhaust manufacturing upgrades in South Carolina, underscore manufacturers' dedication to internal combustion engine platforms. While there's been a decline in catalytic-converter thefts, the financial outlay on replacements remains significant.
- Faurecia (FORVIA)
- Tenneco
- Eberspacher Group
- Benteler International
- Futaba Industrial
- Bosal
- Yutaka Giken
- Sejong Industrial
- Magna International
- Sango Co.
- Friedrich Boysen
- Katcon
- Marelli
- Klarius Group
- AP Exhaust Technologies
- Akrapovic
- Scorpion Exhausts
- Vibrant Performance
- Jetex Exhausts
- Walker Emission Control
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stricter Euro 7 / China VII Emission Norms
- 4.2.2 Rapid Growth In Turbo-Gasoline Passenger Cars
- 4.2.3 Urban Low-Emission Zones (Lez) Expansion
- 4.2.4 OEM Shift To Lightweight Stainless & TI Alloys
- 4.2.5 Rising Demand For Aftermarket Performance Kits
- 4.2.6 Heat-Energy Recovery Integration With Hybrids
- 4.3 Market Restraints
- 4.3.1 Accelerating Bev Power-Train Penetration
- 4.3.2 Raw-Material Price Volatility (Ni, Mo)
- 4.3.3 Catalytic-Metals Theft Risk (Pt, Pd, Rh)
- 4.3.4 Euro-7 Acoustic Caps Limiting Sport Exhausts
- 4.4 Value Chain and Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Component
- 5.1.1 Exhaust Manifold
- 5.1.2 Muffler
- 5.1.3 Catalytic Converter
- 5.1.4 Exhaust Pipes
- 5.1.5 Oxygen Sensor
- 5.1.6 Tailpipe
- 5.2 By Fuel Type
- 5.2.1 Gasoline
- 5.2.2 Diesel
- 5.2.3 Alternate Fuels (Biofuels, CNG, LPG)
- 5.3 By Vehicle Type
- 5.3.1 Two-Wheeler
- 5.3.2 Passenger Cars
- 5.3.3 Light Commercial Vehicles (LCVs)
- 5.3.4 Medium and Heavy Commercial Vehicles (HCVs)
- 5.3.5 Buses and Coaches
- 5.3.6 Off-highway Vehicles
- 5.4 By System Type
- 5.4.1 Single Exhaust System
- 5.4.2 Dual Exhaust System
- 5.4.3 Cat-Back Exhaust System
- 5.4.4 Header Exhaust System
- 5.5 By Sales Channel
- 5.5.1 OEM
- 5.5.2 Aftermarket
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Rest of North America
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Turkey
- 5.6.5.4 South Africa
- 5.6.5.5 Egypt
- 5.6.5.6 Rest of Middle East and Africa
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Faurecia (FORVIA)
- 6.4.2 Tenneco
- 6.4.3 Eberspacher Group
- 6.4.4 Benteler International
- 6.4.5 Futaba Industrial
- 6.4.6 Bosal
- 6.4.7 Yutaka Giken
- 6.4.8 Sejong Industrial
- 6.4.9 Magna International
- 6.4.10 Sango Co.
- 6.4.11 Friedrich Boysen
- 6.4.12 Katcon
- 6.4.13 Marelli
- 6.4.14 Klarius Group
- 6.4.15 AP Exhaust Technologies
- 6.4.16 Akrapovic
- 6.4.17 Scorpion Exhausts
- 6.4.18 Vibrant Performance
- 6.4.19 Jetex Exhausts
- 6.4.20 Walker Emission Control
7 Market Opportunities & Future Outlook
- 7.1 White-space and Unmet-Need Assessment