
|
시장보고서
상품코드
2119929
탐지 도구 시장 : 제품 유형별(벽면 스캐너, 매설 설비 및 배관 탐지기, 금속 탐지기, 전압 및 전기 탐지기, 열화상 카메라, 검사 카메라), 기술별(전자식, 레이더식, 초음파식, 정전용량식) - 세계 예측(-2032년)Detection Tools Market by Product Type (Wall Scanners, Utility & Pipe Detectors, Metal Detectors, Voltage & Electrical Detectors, Thermal Cameras, Inspection Cameras), Technology (Electromagnetic, Radar, Ultrasonic, Capacitive) - Global Forecast to 2032 |
||||||

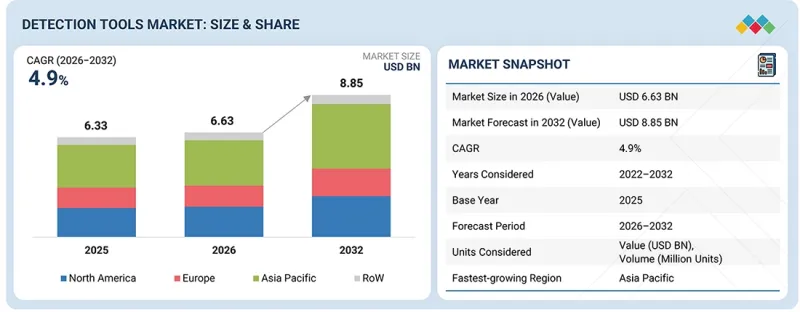
세계의 탐지 도구 시장 규모는 2026년 66억 3,000만 달러에서 2032년에는 88억 5,000만 달러로 성장할 것으로 예상되며, 예측 기간 동안 CAGR은 4.9%에 달할 것으로 전망됩니다.
정부 및 민간 기관이 교통망, 상업용 건물, 아파트, 전력망, 상수도관, 가스 공급 시스템, 통신 인프라 건설에 막대한 투자를 하고 있어 탐지 도구에 대한 수요가 증가하고 있습니다. 이러한 프로젝트에서는 굴착, 토공 작업 또는 유지보수 작업을 수행하기 전에 숨겨진 배관·케이블 등의 설비, 철근, 전기 배선, 지하 매설물을 정확하게 파악하여 우발적인 손상, 프로젝트 지연, 안전상의 위험을 방지해야 합니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2021-2032년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2032년 |
| 단위 | 금액(달러) |
| 부문 | 제품 유형, 기술, 지역별 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 기타 지역 |
벽면 스캐너, 매설 설비·배관 탐지기, 휴대용 금속 탐지기, 열화상 카메라, 검사 카메라 등의 탐지 도구는 비파괴 검사를 가능하게 하여 프로젝트의 효율적인 수행과 규제 준수를 지원합니다.
“레이더식 탐지 도구는 예측 기간 동안 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다.”
레이더식 탐지 도구는 뛰어난 탐지 정확도, 더 깊은 스캔 능력, 철근 콘크리트 및 조적 구조물 등 복잡한 구조물 내부에 숨겨진 여러 재료를 탐지할 수 있는 능력 덕분에 탐지 도구 시장에서 가장 빠른 성장을 기록할 것으로 예상됩니다. 이러한 도구는 정확도가 극히 중요한 고부가가치 건설 및 인프라 프로젝트에서 전문 계약업체, 공공사업체, 산업 설비 유지보수 팀에 의해 점점 더 많이 채택되고 있습니다. 초광대역 레이더 기술, 실시간 이미징, AI를 활용한 물체 인식, 디지털 시각화의 발전으로 인해 그 성능은 더욱 향상되고 적용 범위도 확대되고 있습니다.
“예측 기간 동안 전자기 부문이 주도적인 위치를 차지할 것으로 보입니다.”
전자기 기술은 휴대용 금속 탐지기, 매설 설비·배관 탐지기, 벽면 스캐너에 널리 활용되고 있기 때문에 기술별 탐지 도구 시장에서 예측 기간 동안 가장 큰 점유율을 차지할 것으로 예상됩니다. 전자기 감지 기술은 금속 물체, 전류가 흐르는 전선, 지하 케이블, 전도성 배관을 확실하게 감지할 수 있어 건설, 공공 사업, 산업, 시설 유지보수 등 폭넓은 용도에 적합합니다. 이 기술은 높은 탐지 정확도, 쉬운 조작, 휴대성을 비용 효율적으로 겸비하고 있어 전문 사용자 및 도급업체 사이에서 채택이 확대되고 있습니다. 또한, 센서의 감도, 신호 처리, 간섭 저감에 대한 지속적인 개선을 통해 탐지 성능이 향상되어, 전 세계 탐지 도구 시장 전체에서 전자기 기술의 우위를 더욱 공고히 하고 있습니다.
“2025년, 북미 탐지 도구 시장에서 미국이 가장 큰 점유율을 차지했습니다.”
미국은 활발한 건설 활동, 고도로 발달한 산업 부문, 정기적인 점검과 유지보수가 필요한 광대한 공공 인프라망을 배경으로 북미 탐지 도구 시장에서 최대 점유율을 차지했습니다. 미국에서는 건설, 제조, 에너지, 통신, 시설 관리 등 각 업계에서 첨단 탐지 기술의 도입률이 매우 높습니다. 인프라 현대화, 노후화된 건물의 개보수, 전력·상수도·교통망 확장을 위한 적극적인 투자가 벽면 스캐너, 매설 설비·배관 탐지기, 휴대용 열화상 카메라, 검사 카메라, 휴대용 금속 탐지기의 수요를 지속적으로 끌어올리고 있습니다.
본 보고서는 전 세계 탐지 도구 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 각종 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI의 영향, 특허, 혁신
제7장 규제 상황
제8장 고객 상황과 구매 행동
제9장 프리미엄 레이더 시장 기회 분석
제10장 탐지 도구 시장 : 제품 유형별
제11장 탐지 도구 시장 : 기술별
제12장 탐지 도구 시장 : 가격대별
제13장 탐지 도구 시장 : 유통 채널별
제14장 탐지 도구 시장 : 산업별
제15장 탐지 도구 시장 : 지역별
제16장 경쟁 구도
제17장 기업 개요
제18장 조사 방법
제19장 부록
KSM 26.09.07The global detection tools market is projected to grow from USD 6.63 billion in 2026 to USD 8.85 billion by 2032, at a CAGR of 4.9% during the forecast period. The demand for detection tools is increasing as governments and private organizations invest heavily in the construction of transportation networks, commercial buildings, residential complexes, power grids, water pipelines, gas distribution systems, and telecommunications infrastructure. These projects require accurate identification of concealed utilities, reinforcing bars, electrical wiring, and underground assets before drilling, excavation, or maintenance activities to prevent accidental damage, project delays, and safety hazards.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2021-2032 |
| Base Year | 2025 |
| Forecast Period | 2026-2032 |
| Units Considered | Value (USD Billion) |
| Segments | By Product Type, Technology and Region |
| Regions covered | North America, Europe, APAC, RoW |
Detection tools such as wall scanners, utility & pipe detectors, handheld metal detectors, thermal cameras, and inspection cameras enable non-destructive inspection, ensuring efficient project execution and regulatory compliance.
"Radar tools are expected to record the highest CAGR during the forecast period."
Radar-based detection tools are expected to register the fastest growth in the detection tools market by price tier due to their superior detection accuracy, deeper scanning capabilities, and ability to identify multiple concealed materials through complex structures such as reinforced concrete and masonry. These tools are increasingly adopted by professional contractors, utility companies, and industrial maintenance teams for high-value construction and infrastructure projects where precision is critical. Advancements in ultra-wideband radar technology, real-time imaging, AI-assisted object recognition, and digital visualization are further enhancing their performance and expanding their application scope.
"The electromagnetic segment will dominate the detection tools market during the forecast period."
Electromagnetic technology is expected to dominate the detection tools market by technology during the forecast period due to its widespread use in handheld metal detectors, utility & pipe detectors, and wall scanners. Electromagnetic sensing reliably detects metallic objects, live electrical wires, underground cables, and conductive pipes, making it suitable for a broad range of construction, utility, industrial, and facility maintenance applications. The technology offers a cost-effective combination of high detection accuracy, ease of operation, and portability, driving its adoption among both professional users and contractors. Additionally, continuous improvements in sensor sensitivity, signal processing, and interference reduction have enhanced detection performance, further strengthening the dominance of electromagnetic technology across the global detection tools market.
"The US accounted for the largest share of the North American detection tools market in 2025."
The US accounted for the largest share of the North American detection tools market due to its extensive construction activity, well-developed industrial sector, and vast network of utility infrastructure requiring regular inspection and maintenance. The country has a high rate of adoption of advanced detection technologies across the construction, manufacturing, energy, telecommunications, and facility management industries. Strong investments in infrastructure modernization, renovation of aging buildings, and expansion of power, water, and transportation networks continue to drive demand for wall scanners, utility & pipe detectors, handheld thermal cameras, inspection cameras, and handheld metal detectors.
- By Company Type: Tier 1 - 30%, Tier 2 - 40%, and Tier 3 - 30%
- By Designation: Directors - 40%, C-level Executives - 35%, and Others - 25%
- By Region: North America - 20%, Europe - 30%, Asia Pacific - 40%, and RoW - 10%
Prominent players profiled in this report include Hilti (Liechtenstein), Stanley Black & Decker Inc. (US), Robert Bosch GmbH (Germany), Milwaukee Tool (US), Leica Geosystems (Switzerland), Zircon Corporation (US), Klein (US), Fluke Corporation (US), Hikvision (China), Hioki E.E. Corporation (Japan).
Research Coverage:
The report defines, describes, and forecasts the detection tools market based on product type (wall scanner (stud finders, radar scanners), utility & pipe detectors (cable and pipe detectors, GPR scanners), metal detectors (handheld metal detectors, magnetic locators), voltage & electrical detectors, thermal-assisted detection tools, inspection cameras), price tier (single/multi-sensor tools (low price point (LPP) (<USD 50), mid price point (MPP) (USD 50-100), high price point (HPP) (>USD 100)), radar tools (low price point (LPP) (<USD 400), mid price point (MPP) (USD 400-2000), high price point (HPP) (>USD 2000)), inspection cameras (low price point (LPP) (<USD 50), mid price point (MPP) (USD 50-100), high price point (HPP) (>USD 100))), technology (electromagnetic detection, radar-based detection, ultrasonic detection, infrared-based detection, capacitive sensing, AI-enabled smart detection), distribution channel (manufacturer direct/web store, wholesalers/industrial distributors, specialist trade channels, DIY super stores, Ecommerce), industry (residential, commercial, industrial facilities, infrastructure & public utilities, oil & gas, mining, others), and region (North America, Europe, Asia Pacific, and RoW). It provides detailed information regarding drivers, restraints, opportunities, and challenges influencing the market's growth. It also analyzes competitive developments, including acquisitions, product launches, expansions, and actions taken by key players to grow in the market.
Reasons to Buy This Report:
The report will help market leaders/new entrants with information on the closest approximations of the revenue for the overall detection tools market and its subsegments. The report will help stakeholders understand the competitive landscape and gain more insight to position their business better and plan suitable go-to-market strategies. The report also helps stakeholders understand the market's pulse and provides information on key drivers, restraints, opportunities, and challenges.
The report will provide insights into the following points:
- Analysis of key drivers (Increasing infrastructure development and expansion of utility networks, growing adoption of predictive maintenance across industrial facilities), restraints (high cost of advanced detection tools, availability of low-cost alternatives and counterfeit products), opportunities (growing adoption of smart, AI-enabled, and connected detection tools, expansion into emerging markets driven by rapid industrialization and urbanization), and challenges (detection accuracy limitations in complex environments, shortage of skilled operators and interpretation expertise for advanced detection tools) of the detection tools market.
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product launches in the detection tools market.
- Market Development: Comprehensive information about lucrative markets. The report analyzes the detection tools market across various regions.
- Market Diversification: Exhaustive information about new products launched, untapped geographies, recent developments, and investments in the detection tools market
- Competitive Assessment: In-depth assessment of market share, growth strategies, and offerings of leading players, including Hilti (Liechtenstein), Stanley Black & Decker Inc. (US), Robert Bosch GmbH (Germany), Milwaukee Tool (US), and Leica Geosystems (Switzerland), in the detection tools market.
TABLE OF CONTENTS
1. INTRODUCTION
- 1.1. STUDY OBJECTIVES
- 1.2. MARKET DEFINITION AND SCOPE
- 1.3. STUDY SCOPE
- 1.3.1. MARKETS COVERED
- 1.3.2. GEOGRAPHIC SEGMENTATION
- 1.3.3. YEARS CONSIDERED FOR STUDY
- 1.4. CURRENCY
- 1.5. LIMITATIONS
- 1.6. STAKEHOLDERS
2. EXECUTIVE SUMMARY
- 2.1. KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2. KEY MARKET PARTICIPANTS: INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3. DISRUPTIVE TRENDS SHAPING THE MARKET
- 2.4. HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5. SNAPSHOT: GLOBAL MARKET SIZE, GROWTH RATE, AND FORECAST
3. PREMIUM INSIGHTS
4. MARKET OVERVIEW
- 4.1. INTRODUCTION
- 4.2. MARKET DYNAMICS
- 4.2.1. DRIVERS
- 4.2.2. RESTRAINTS
- 4.2.3. OPPORTUNITIES
- 4.2.4. CHALLENGES
- 4.3. INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4. STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
5. INDUSTRY TRENDS
- 5.1. PORTER'S FIVE FORCES ANALYSIS
- 5.2. MACROECONOMICS INDICATORS
- 5.2.1. INTRODUCTION
- 5.2.2. GDP TRENDS AND FORECAST
- 5.2.3. TRENDS IN THE GLOBAL MEASURING TOOLS INDUSTRY
- 5.3. VALUE CHAIN ANALYSIS
- 5.4. ECOSYSTEM ANALYSIS
- 5.5. PRICING ANALYSIS
- 5.5.1. AVERAGE SELLING PRICE TREND OF TYPE, BY KEY PLAYERS (2022-2025)
- 5.5.2. AVERAGE SELLING PRICE TREND BY TYPE (2022-2025)
- 5.5.2.1. Radar based Tools
- 5.5.2.2. Non-Radar Based Tools
- 5.5.2.3. Inspection Cameras
- 5.5.3. AVERAGE SELLING PRICE TREND, BY REGION (2022-2025)
- 5.6. TRADE ANALYSIS
- 5.6.1. IMPORT SCENARIO
- 5.6.2. EXPORT SCENARIO
- 5.7. KEY CONFERENCES AND EVENTS, 2025-2026
- 5.8. TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9. INVESTMENT AND FUNDING SCENARIO
- 5.10. CASE STUDY ANALYSIS
- 5.11. IMPACT OF 2025 US TARIFF - DETECTION TOOLS MARKET
- 5.11.1. INTRODUCTION
- 5.11.2. KEY TARIFF RATES
- 5.11.3. PRICE IMPACT ANALYSIS
- 5.11.4. IMPACT ON COUNTRIES/REGIONS
- 5.11.5. IMPACT ON INDUSTRIES
6. TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, AND INNOVATIONS
- 6.1. KEY EMERGING TECHNOLOGIES
- 6.2. COMPLEMENTARY TECHNOLOGIES
- 6.3. TECHNOLOGY ROADMAP
- 6.4. PATENT ANALYSIS
- 6.5. IMPACT OF AI ON DETECTION TOOLS MARKET
- 6.5.1. TOP USE CASES AND MARKET POTENTIAL
- 6.5.2. BEST PRACTICES IN THE DETECTION TOOLS MARKET
- 6.5.3. CASE STUDIES OF AI IMPLEMENTATION IN THE DETECTION TOOLS MARKET
- 6.5.4. INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.5.5. CLIENTS' READINESS TO ADOPT AI IN THE DETECTION TOOLS MARKET
7. REGULATORY LANDSCAPE
- 7.1. REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1. REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2. INDUSTRY STANDARDS
8. CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1. DECISION-MAKING PROCESS
- 8.2. BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.3. ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4. UNMET NEEDS FROM VARIOUS APPLICATIONS
9. PREMIUM RADAR MARKET OPPORTUNITY ANALYSIS
- 9.1. PRICE GAP ASSESSMENT (USD 2,000-8,000)
- 9.2. CUSTOMER REQUIREMENTS DRIVING PREMIUM ADOPTION
10. DETECTION TOOLS MARKET, BY PRODUCT TYPE
- 10.1. INTRODUCTION
- 10.2. WALL SCANNERS
- 10.2.1. STUD FINDERS
- 10.2.2. RADAR SCANNER
- 10.3. UTILITY & PIPE DETECTORS
- 10.3.1. CABLE & WIRE DETECTORS
- 10.3.2. GPR SCANNER
- 10.4. METAL DETECTORS
- 10.4.1. HANDHELD METAL DETECTORS
- 10.4.2. MAGNETIC LOCATORS
- 10.5. VOLTAGE & ELECTRICAL DETECTORS
- 10.6. THERMAL-ASSISTED DETECTION TOOLS
11. DETECTION TOOLS MARKET, BY TECHNOLOGY
- 11.1. INTRODUCTION
- 11.2. ELECTROMAGNETIC DETECTION
- 11.3. RADAR-BASED DETECTION
- 11.4. ULTRASONIC DETECTION
- 11.5. INFRARED-BASED DETECTION
- 11.6. CAPACITIVE SENSING
- 11.7. AI-ENABLED SMART DETECTION
12. DETECTION TOOLS MARKET, BY PRICE TIER
- 12.1. INTRODUCTION
- 12.2. MULTI-SENSOR TOOLS
- 12.2.1. LOW PRICE POINT (LPP) (<USD 50)
- 12.2.2. MID PRICE POINT (MPP) (USD 50-100)
- 12.2.3. HIGH PRICE POINT (HPP) (>USD 100)
- 12.3. RADAR TOOLS
- 12.3.1. LOW PRICE POINT (LPP) (<USD 400)
- 12.3.2. MID PRICE POINT (MPP) (USD 400-2,000)
- 12.3.3. HIGH PRICE POINT (HPP) (>USD 2,000)
- 12.4. INSPECTION CAMERAS
- 12.4.1. LOW PRICE POINT (LPP) (<USD 50)
- 12.4.2. MID PRICE POINT (MPP) (USD 50-100)
- 12.4.3. HIGH PRICE POINT (HPP) (>USD 100)
13. DETECTION TOOLS MARKET, BY DISTRIBUTION CHANNEL
- 13.1. INTRODUCTION
- 13.2. MANUFACTURER DIRECT/WEB STORE
- 13.3. WHOLESEALERS/INDUSTRIAL DISTRIBUTORS
- 13.4. SPECIALIST TRADE CHANNELS
- 13.5. DIY SUPER STORES
- 13.6. ECOMMERCE Note: 1-2 examples of companies operating under distribution channel ecosystem across each of the regions will be provided.
14. DETECTION TOOLS MARKET, BY INDUSTRY
- 14.1. INTRODUCTION
- 14.2. RESIDENTIAL
- 14.3. COMMERCIAL
- 14.4. INDUSTRIAL FACILITIES
- 14.5. INFRASTRUCTURE & PUBLIC UTILITIES
- 14.6. OIL & GAS
- 14.7. MINING
- 14.8. OTHERS
15. DETECTION TOOLS MARKET, BY REGION
- 15.1. INTRODUCTION
- 15.2. NORTH AMERICA
- 15.2.1. COMPETITOR OVERVIEW: RANKING ANALYSIS OF TOP 5 PLAYERS IN NORTH AMERICA
- 15.2.2. US
- 15.2.3. CANADA
- 15.2.4. MEXICO
- 15.3. EUROPE
- 15.3.1. COMPETITOR OVERVIEW: RANKING ANALYSIS OF TOP 5 PLAYERS IN EUROPE
- 15.3.2. GERMANY
- 15.3.3. UK
- 15.3.4. FRANCE
- 15.3.5. ITALY
- 15.3.6. SPAIN
- 15.3.7. POLAND
- 15.3.8. TURKEY
- 15.3.9. REST OF EUROPE
- 15.4. ASIA PACIFIC
- 15.4.1. COMPETITOR OVERVIEW: RANKING ANALYSIS OF TOP 5 PLAYERS IN ASIA PACIFIC
- 15.4.2. CHINA
- 15.4.3. JAPAN
- 15.4.4. INDIA
- 15.4.5. SOUTH KOREA
- 15.4.6. AUSTRALIA
- 15.4.7. REST OF ASIA PACIFIC
- 15.5. ROW
- 15.5.1. COMPETITOR OVERVIEW: RANKING ANALYSIS OF TOP 5 PLAYERS IN ROW
- 15.5.2. MIDDLE EAST
- 15.5.3. AFRICA
- 15.5.4. SOUTH AMERICA
- 15.5.4.1. Brazil
- 15.5.4.2. Rest of South America
16. DETECTION TOOLS MARKET, COMPETITIVE LANDSCAPE
- 16.1. OVERVIEW
- 16.2. KEY PLAYER STRATEGIES/RIGHT TO WIN
- 16.3. REVENUE ANALYSIS, 2021-2025
- 16.4. MARKET SHARE ANALYSIS, 2025
- 16.5. BRAND/PRODUCT COMPARISON
- 16.6. COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 16.6.1. STARS
- 16.6.2. EMERGING LEADERS
- 16.6.3. PERVASIVE PLAYERS
- 16.6.4. PARTICIPANTS
- 16.6.5. COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 16.6.5.1. Company Footprint
- 16.6.5.2. Region Footprint
- 16.6.5.3. Product Type Footprint
- 16.6.5.4. Industry Footprint
- 16.7. COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 16.7.1. PROGRESSIVE COMPANIES
- 16.7.2. RESPONSIVE COMPANIES
- 16.7.3. DYNAMIC COMPANIES
- 16.7.4. STARTING BLOCKS
- 16.7.5. COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 16.7.5.1. Detailed List of Key Startups/SMEs
- 16.7.5.2. Competitive Benchmarking of Key Startups/SMEs
- 16.8. COMPANY VALUATION AND FINANCIAL METRICS
- 16.9. COMPETITIVE SCENARIO
- 16.9.1. PRODUCT LAUNCHES
- 16.9.2. DEALS
- 16.9.3. EXPANSIONS
17. DETECTION TOOLS MARKET, COMPANY PROFILES
- 17.1. INTRODUCTION
- 17.2. KEY PLAYERS
- 17.2.1. CST/BERGER
- 17.2.2. DEWALT
- 17.2.3. FLUKE CORPORATION
- 17.2.4. HILTI
- 17.2.5. JOHNSON LEVEL & TOOL
- 17.2.6. LEICA GEOSYSTEMS
- 17.2.7. MAKITA CORPORATION
- 17.2.8. MILWAUKEE TOOL
- 17.2.9. RADIODETECTION
- 17.2.10. RIDGID
- 17.2.11. ROBERT BOSCH GMBH
- 17.2.12. STANLEY BLACK & DECKER
- 17.2.13. TOPCON CORPORATION
- 17.2.14. TRIMBLE
- 17.2.15. ZIRCON CORPORATION
- 17.2.16. LASERLINER
- 17.2.17. FRANKLIN SENSORS
- 17.2.18. TESLONG
- 17.2.19. ROTHENBERGER
- 17.2.20. HANMATEK
18. RESEARCH METHODOLOGY
- 18.1. RESEARCH DATA
- 18.1.1. SECONDARY DATA
- 18.1.1.1. Key Data from Secondary Sources
- 18.1.2. PRIMARY DATA
- 18.1.2.1. Key Data from Primary Sources
- 18.1.2.2. Key Primary Participants
- 18.1.2.3. Breakdown of Primary Interviews
- 18.1.2.4. Key Industry Insights
- 18.1.1. SECONDARY DATA
- 18.2. MARKET SIZE ESTIMATION
- 18.2.1. BOTTOM-UP APPROACH
- 18.2.2. TOP-DOWN APPROACH
- 18.2.3. BASE NUMBER CALCULATION
- 18.3. MARKET FORECAST APPROACH
- 18.3.1. SUPPLY SIDE
- 18.3.2. DEMAND SIDE
- 18.4. DATA TRIANGULATION
- 18.5. FACTOR ANALYSIS
- 18.6. RESEARCH ASSUMPTIONS
- 18.7. RESEARCH LIMITATIONS AND RISK ASSESSMENT
19. APPENDIX


