|
시장보고서
상품코드
2126325
올리고뉴클레오티드 합성 시장 : 제공별(합성 제품(소모품, 장비), 합성 올리고(DNA, RNA), 올리고뉴클레오티드 기반 의약품(ASO, siRNA)), 치료 분야별(희귀질환, 신경, 암), 경쟁사별 - 세계 예측(-2031년)Oligonucleotide Synthesis Market by Offering (Synthesis Products (Consumables, Equipment), Synthesized Oligos (DNA, RNA), Oligo-based Drugs (ASO, siRNA)), Therapy Area (Rare Diseases, Neurology, Oncology), Competition - Global Forecast to 2031 |
||||||

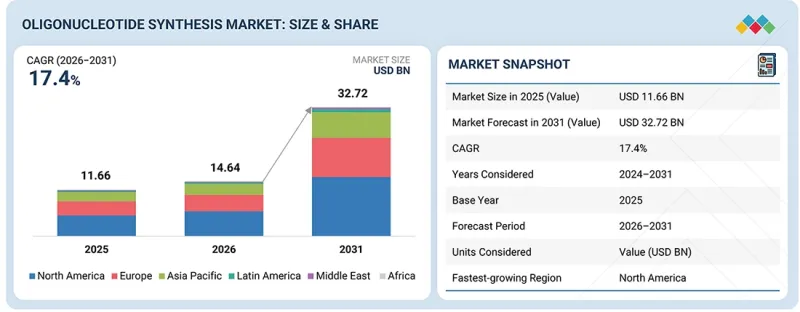
올리고뉴클레오티드 합성 시장 규모는 2026년 146억 4,000만 달러에서 예측 기간 동안 CAGR 17.4%로 확대되어, 2031년에는 327억 2,000만 달러에 달할 것으로 예측됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2026-2031년 |
| 기준 연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 단위 | 금액(달러) |
| 부문 | 제공, 올리고뉴클레오티드 기반 의약품, 합성 올리고뉴클레오티드, 올리고뉴클레오티드 합성 제품 |
| 대상 지역 | 북미, 유럽, 아시아태평양, 라틴아메리카, 중동 및 아프리카 |
해당 시장의 성장은 연구 및 진단용 프라이머나 프로브 등 합성 올리고뉴클레오티드에 대한 수요 증가를 비롯한 여러 요인에 의해 주도되고 있습니다. 올리고뉴클레오티드 합성 기술의 발전 또한 예측 기간 동안 시장 성장에 기여할 것으로 예상됩니다.
제품 유형별로는 올리고뉴클레오티드 기반 의약품 부문이 2025년에 가장 큰 시장 점유율을 차지
2025년에는 올리고뉴클레오티드 기반 의약품 부문이 시장에서 가장 큰 점유율을 차지했습니다. 이러한 높은 점유율은 특히 희귀질환 및 유전성 질환 분야에서 이러한 치료법에 대한 수용도가 높아지고 그 효과가 입증되고 있음을 반영합니다. 안티센스 올리고뉴클레오티드(ASO) 및 소분자 간섭 RNA(siRNA)와 같은 의약품은 질병의 원인이 되는 유전자를 표적으로 하여 정밀하고 개인화된 치료를 제공합니다. 이러한 수요 확대는 RNA를 표적으로 하는 치료법 및 전달 시스템의 발전, 유전성 질환 유병률 증가, 그리고 RNA 기반 치료법의 연구 개발에 대한 막대한 투자에 힘입어 이루어지고 있습니다.
2025년, 북미가 올리고뉴클레오티드 합성 시장 전체에서 가장 큰 점유율을 차지
미국은 올리고뉴클레오티드 합성의 최대 시장이며, 북미가 세계 시장 매출에서 압도적인 점유율을 차지하는 원동력이 되고 있습니다. 이러한 우위는 대형 바이오의약품 기업, 세계 최고 수준의 학술 연구 기관, 유전체 혁신에 대한 광범위한 벤처 캐피털 투자로 구성된 긴밀한 생태계에 의해 뒷받침되고 있습니다. 또한, 150종 이상의 올리고 기반 치료제를 보유한 대규모 임상 개발 파이프라인에 더해, 미국 식품의약국(FDA)의 명확하고 지원적인 규제 프레임워크가 결합되어, 다른 국가에서는 찾아볼 수 없는 수준으로 복잡하고 대규모이며 고순도의 GMP 생산에 대한 수요를 견인하고 있습니다.
본 보고서에서는 전 세계 올리고뉴클레오티드 합성 시장을 조사하여, 시장 개요, 시장 성장에 영향을 미치는 다양한 요인에 대한 분석, 기술 및 특허 동향, 법규제 환경, 사례 연구, 시장 규모 추정 및 전망, 각종 분류·지역/주요 국가별 상세 분석, 경쟁 구도, 주요 기업 개요 등을 종합적으로 다루고 있습니다.
자주 묻는 질문
목차
제1장 소개
제2장 주요 요약
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술의 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 올리고뉴클레오티드 합성 시장 : 제공별
제10장 올리고뉴클레오티드 기반 의약품 시장 : 유형별
제11장 올리고뉴클레오티드 기반 의약품 시장 : 치료 분야별
제12장 올리고뉴클레오티드 기반 의약품 시장 : 최종사용자별
제13장 합성 올리고뉴클레오티드 시장 : 올리고 유형별
제14장 합성 올리고뉴클레오티드 시장 : 유형별
제15장 합성 올리고뉴클레오티드 시장 : 용도별
제16장 합성 올리고뉴클레오티드 시장 : 최종사용자별
제17장 올리고뉴클레오티드 합성 제품 시장 : 유형별
제18장 올리고뉴클레오티드 합성 제품 시장 : 용도별
제19장 올리고뉴클레오티드 합성 제품 시장 : 최종사용자별
제20장 올리고뉴클레오티드 합성 시장 : 지역별
제21장 경쟁 구도
제22장 기업 개요
제23장 조사 방법
제24장 부록
KSM 26.09.10The oligonucleotide synthesis market is projected to reach USD 32.72 billion by 2031, up from USD 14.64 billion in 2026, at a CAGR of 17.4% over the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2026-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD billion) |
| Segments | Offerings, Oligonucleotide-based drugs, Synthesized Oligonucleotide, Oligonucleotide Synthesis Product |
| Regions covered | North America, Europe, Asia Pacific, Latin America, the Middle East, and Africa |
Market growth is driven by several factors, including increasing demand for synthesized oligonucleotides such as primers and probes for research and diagnostic applications. Rising technological advancements in oligonucleotide synthesis are also expected to contribute to market growth during the forecast period.
By offering, the oligonucleotide-based drugs segment accounted for the largest share of the market in 2025.
The market is segmented into oligonucleotide-based drugs, synthesized oligonucleotides and oligonucleotide synthesis products (consumables and equipment). In 2025, the oligonucleotide-based drugs segment accounted for the largest share of the market. This large share reflects growing acceptance of these treatments and their proven success, especially for rare and hereditary diseases. Medications such as antisense oligonucleotides (ASOs) and small interfering RNAs (siRNAs) target disease-causing genes, providing precise and personalized treatments. This growing demand is fueled by advancements in RNA-targeted therapies and delivery systems, the rising prevalence of genetic diseases, and significant investments in research and development of RNA-based treatments.
In 2025, North America accounted for the largest share of the overall oligonucleotide synthesis market.
The US is the largest market for oligonucleotide synthesis, driving North America's commanding share of global market revenue. This dominance is propelled by a dense ecosystem of major biopharmaceutical companies, world-class academic research institutes, and extensive venture capital investment in genomic innovation. Furthermore, a massive clinical drug pipeline featuring over 150 oligo-based therapeutics, coupled with clear, supportive regulatory frameworks from the US FDA, drives demand for complex, large-scale, high-purity GMP production at a level unmatched by any other nation.
The primary interviews conducted for this report can be categorized as follows:
- By Respondent: Tier 1-25%, Tier 2-35%, and Tier 3- 40%
- By Designation: C-level Executives - 30%, Directors- 45%, and Others- 25%
- By Region: North America - 35%, Europe - 25%, Asia Pacific - 15%, Latin America - 10%, Middle East- 10%, and Africa - 5%
Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), Merck KGaA (Germany), Eurofins Scientific (Luxembourg), LGC Limited (UK), Agilent Technologies, Inc. (US), Kaneka Corporation (Japan), Maravai LifeSciences (US), Azenta US Inc. (US), Twist Bioscience (US), and GenScript (US) are some of the key companies profiled in the report offering oligonucleotide synthesis products and synthesized oligonucleotides.
Biogen (US) Alnylam Pharmaceuticals, Inc. (US), Sarepta Therapeutics, Inc. (US), AstraZeneca (UK), Astellas Pharma Inc. (Japan), Jazz Pharmaceuticals Plc (Ireland), Nippon Shinyaku, Co. Ltd. (Japan), Ionis Pharmaceuticals, Inc. (US), and Novartis AG (Switzerland) are some of the key companies offering oligonucleotide-based drugs, profiled in the report.
Research Coverage:
This research report categorizes oligonucleotide synthesis market by offering (oligonucleotide-based drugs, synthesized oligonucleotides, oligonucleotide synthesis products); oligonucleotide-based drugs (by type: antisense oligonucleotide-based drugs, siRNA oligonucleotide-based drugs, other oligonucleotide-based drugs; by therapeutic area: rare diseases, cardiometabolic diseases, neurology, other therapeutic areas; by end user: hospitals, specialty clinics, home care settings, other end users); synthesized oligonucleotides (by oligo type: primers, probes, DNA oligos, RNA oligos, other oligos; by application: therapeutic applications, research applications, and diagnostic applications, by end user: biopharmaceutical & biotechnology companies, CROs & CDMOs, academic & research institutes, and diagnostic companies & laboratories); oligonucleotide synthesis products (by type: consumables, oligo synthesis equipment; by application: therapeutic applications, research applications, and diagnostic applications, by end user: biopharmaceutical & biotechnology companies, CROs & CDMOs, academic & research institutes, and diagnostic companies & laboratories), and region (North America, Europe, Asia Pacific, Latin America, Middle East, and Africa).
The report's scope covers detailed information on the primary factors, such as drivers, restraints, challenges, and opportunities, that influence the growth of the oligonucleotide synthesis market. A thorough analysis of key industry players has been conducted to provide insights into their business overviews, product offerings, key strategies, new product launches, acquisitions, and recent developments associated with the oligonucleotide synthesis market. This report also covers the competitive analysis of upcoming startups in the oligonucleotide synthesis market ecosystem.
Key Benefits of Buying the Report:
The report will help market leaders and new entrants by providing the closest approximations of revenue for the oligonucleotide synthesis market and its subsegments. It will also help stakeholders better understand the competitive landscape and gain insights to position their business and develop suitable go-to-market strategies. This report will enable stakeholders to understand the market's pulse and provide information on key market drivers, restraints, challenges, trends, and opportunities.
The report provides insights on the following:
- Analysis of key drivers (Increasing use of synthesized oligos in therapeutic and diagnostic applications, technological advancements in oligonucleotide synthesis, growing government investments in life science research & synthetic biology, and growing focus on personalized medicine), restraints (Complexities associated with oligonucleotide-based drugs), opportunities (Increasing R&D investments by key players in emerging economies), and challenges (Lack of standard regulations, challenges in targeted delivery of oligonucleotides) are influencing the growth of the oligonucleotide synthesis market.
- Product Approvals: Detailed insights on newly approved products of the oligonucleotide synthesis market
- Market Development: Comprehensive information about lucrative markets - the report analyzes the oligonucleotide synthesis market across varied regions
- Market Diversification: Exhaustive information about new products, recent developments, and investments in the oligonucleotide synthesis market
- Pipeline Analysis: Comprehensive information about oligonucleotide-based drugs under clinical trials
- Competitive Assessment: In-depth assessment of market, growth strategies, and product offerings of leading players, including Danaher Corporation (US), Thermo Fisher Scientific Inc. (US), and Merck KGaA (Germany), among others, offering oligonucleotide synthesis products and synthesized oligonucleotides. Biogen (US), Alnylam Pharmaceuticals, Inc. (US), Novartis AG (Switzerland), and Sarepta Therapeutics, Inc. (US) are key players in the oligonucleotide-based drugs segment of this market.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKET SEGMENTATION & REGIONS COVERED
- 1.3.2 REGIONS COVERED
- 1.3.3 INCLUSIONS & EXCLUSIONS
- 1.3.4 YEARS CONSIDERED
- 1.3.5 CURRENCY CONSIDERED
- 1.4 STAKEHOLDERS
- 1.5 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS & KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN OLIGONUCLEOTIDE SYNTHESIS MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 GLOBAL OLIGONUCLEOTIDE SYNTHESIS MARKET SNAPSHOT
- 3.2 NORTH AMERICA: OLIGONUCLEOTIDE SYNTHESIS MARKET, BY OFFERING AND COUNTRY, 2025
- 3.3 OLIGONUCLEOTIDE SYNTHESIS MARKET: GEOGRAPHIC GROWTH OPPORTUNITIES
- 3.4 OLIGONUCLEOTIDE SYNTHESIS MARKET SHARE, BY OFFERING, 2026 VS. 2031 (%)
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Rising commercialization and regulatory approvals of oligonucleotide therapeutics
- 4.2.1.2 Expanding RNA therapeutics pipeline and adoption of chemically modified oligos
- 4.2.1.3 Growing use of PCR, qPCR, NGS, CRISPR, synthetic biology, and molecular diagnostics
- 4.2.1.4 Increasing outsourcing of oligonucleotide synthesis and GMP manufacturing to CROs/CDMOs
- 4.2.2 RESTRAINTS
- 4.2.2.1 Complexity of large-scale oligonucleotide manufacturing and analytical control
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Increasing government and industry investments in life sciences, RNA therapeutics, and manufacturing infrastructure
- 4.2.3.2 Expansion of oligonucleotide therapeutics into cardiometabolic and common chronic diseases
- 4.2.3.3 Growth of companion diagnostics and precision medicine
- 4.2.4 CHALLENGES
- 4.2.4.1 Lack of standard regulations
- 4.2.4.2 Delivery of oligonucleotide drugs to specific targets
- 4.2.4.3 Sustainability & waste management in phosphoramidite-based synthesis
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS & WHITE SPACES
- 4.4 INTERCONNECTED MARKETS & CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS
- 4.5.1 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS IN THE OLIGONUCLEOTIDE-BASED DRUGS MARKET
- 4.5.2 STRATEGIC MOVES BY TIER-1/2/3 PLAYERS IN OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES MARKET
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 OLIGONUCLEOTIDE-BASED DRUGS
- 5.1.1.1 Threat of new entrants
- 5.1.1.2 Threat of substitutes
- 5.1.1.3 Bargaining power of buyers
- 5.1.1.4 Bargaining power of suppliers
- 5.1.1.5 Intensity of competitive rivalry
- 5.1.2 SYNTHESIZED OLIGONUCLEOTIDES & OLIGONUCLEOTIDE SYNTHESIS PRODUCTS
- 5.1.2.1 Threat of new entrants
- 5.1.2.2 Threat of substitutes
- 5.1.2.3 Bargaining power of buyers
- 5.1.2.4 Bargaining power of suppliers
- 5.1.2.5 Intensity of competitive rivalry
- 5.1.1 OLIGONUCLEOTIDE-BASED DRUGS
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS & FORECAST
- 5.2.3 TRENDS IN GLOBAL OLIGONUCLEOTIDE SYNTHESIS MARKET
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 AVERAGE SELLING PRICE TREND OF KEY PRODUCTS, BY KEY PLAYER, 2022-2025
- 5.5.2 AVERAGE SELLING PRICE OF EQUIPMENT, BY REGION, 2025
- 5.6 KEY CONFERENCES & EVENTS, 2026-2027
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMERS' BUSINESSES
- 5.8 INVESTMENT & FUNDING ACTIVITY
- 5.9 IMPACT OF 2025 US TARIFFS ON OLIGONUCLEOTIDE SYNTHESIS MARKET
- 5.9.1 INTRODUCTION
- 5.9.2 KEY TARIFF RATES
- 5.9.3 PRICE IMPACT ANALYSIS
- 5.9.4 IMPACT ON COUNTRY/REGION
- 5.9.4.1 North America
- 5.9.4.2 Europe
- 5.9.4.3 Asia Pacific
- 5.9.5 IMPACT ON END-USE INDUSTRIES
- 5.9.5.1 Hospitals
- 5.9.5.2 Specialty clinics
- 5.9.5.3 Home care settings & other end users
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 TECHNOLOGY ANALYSIS
- 6.1.1 KEY TECHNOLOGIES
- 6.1.1.1 Solid-phase phosphoramidite synthesis and scale-up
- 6.1.1.2 Liquid-phase synthesis
- 6.1.1.3 Chemical modification & backbone engineering
- 6.1.1.4 Conjugation & targeted delivery chemistry
- 6.1.1.5 Enzymatic & novel synthesis technologies
- 6.1.1.6 High-throughput automated oligonucleotide synthesis
- 6.1.1.7 Purification & analytical characterization
- 6.1.2 ADJACENT TECHNOLOGIES
- 6.1.2.1 Molecular biology & genomic technologies
- 6.1.2.2 Synthetic biology & gene synthesis
- 6.1.3 COMPLEMENTARY TECHNOLOGIES
- 6.1.3.1 Advanced oligonucleotide delivery technologies
- 6.1.3.2 AI-assisted oligonucleotide design
- 6.1.1 KEY TECHNOLOGIES
- 6.2 TECHNOLOGY/PRODUCT ROADMAP
- 6.3 FUTURE APPLICATIONS
- 6.4 IMPACT OF AI/GEN AI ON OLIGONUCLEOTIDE SYNTHESIS MARKET
- 6.4.1 TOP USE CASES & MARKET POTENTIAL
- 6.4.2 INTERCONNECTED ADJACENT ECOSYSTEMS & IMPACT ON MARKET PLAYERS
- 6.4.3 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN OLIGONUCLEOTIDE SYNTHESIS MARKET
- 6.5 PATENT ANALYSIS & INNOVATIONS
- 6.5.1 OLIGONUCLEOTIDE SYNTHESIS MARKET: PATENT ANALYSIS, 2015-2025
- 6.5.2 KEY INNOVATIONS
7 SUSTAINABILITY & REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS & COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 REGULATORY FRAMEWORK & REIMBURSEMENT
- 7.1.2.1 North America
- 7.1.2.2 Europe
- 7.1.2.3 Asia Pacific
- 7.1.2.4 Rest of the World
- 7.1.3 INDUSTRY STANDARDS
- 7.2 REIMBURSEMENT SCENARIO
- 7.3 SUSTAINABILITY IMPACT & REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, AND ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS & BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 KEY BUYING CRITERIA, BY END USER
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM END USERS
- 8.5 MARKET PROFITABILITY
9 OLIGONUCLEOTIDE SYNTHESIS MARKET, BY OFFERING
- 9.1 INTRODUCTION
- 9.2 OLIGONUCLEOTIDE-BASED DRUGS
- 9.2.1 RECURRING CONSUMABLES DEMAND, AUTOMATION UPGRADES, AND ADVANCED SCREENING PLATFORMS TO DRIVE GROWTH
- 9.3 SYNTHESIZED OLIGONUCLEOTIDES
- 9.3.1 GROWING ADOPTION OF PCR, QPCR, NGS, AND CRISPR-BASED GENOME EDITING TO GENERATE SUBSTANTIAL DEMAND FOR CUSTOM PRIMERS
- 9.4 OLIGONUCLEOTIDE SYNTHESIS PRODUCTS
- 9.4.1 INCREASING INSTALLATION OF AUTOMATED OLIGONUCLEOTIDE SYNTHESIZERS TO SUPPORT MARKET GROWTH
10 OLIGONUCLEOTIDE-BASED DRUGS MARKET, BY TYPE
- 10.1 INTRODUCTION
- 10.2 ANTISENSE OLIGONUCLEOTIDE (ASO)-BASED DRUGS
- 10.2.1 ASO-BASED DRUGS ACCOUNTED FOR LARGEST MARKET SHARE DUE TO THEIR ESTABLISHED CLINICAL SUCCESS ACROSS RARE AND NEUROLOGICAL DISEASES
- 10.3 SIRNA OLIGONUCLEOTIDE-BASED DRUGS
- 10.3.1 EXPANDING COMMERCIAL ADOPTION AND STRONG LATE-STAGE PIPELINES TO DRIVE GROWTH
- 10.4 OTHER OLIGONUCLEOTIDE-BASED DRUGS
11 OLIGONUCLEOTIDE-BASED DRUGS MARKET, BY THERAPEUTIC AREA
- 11.1 INTRODUCTION
- 11.2 RARE DISEASES
- 11.2.1 GROWING APPROVALS FOR ORPHAN DISEASES TO MAKE RARE DISEASES LARGEST THERAPEUTIC AREA FOR OLIGONUCLEOTIDE THERAPEUTICS
- 11.3 NEUROLOGICAL DISORDERS
- 11.3.1 COMMERCIAL SUCCESS OF RNA-TARGETED THERAPIES TO CONTINUE TO STRENGTHEN NEUROLOGY SEGMENT
- 11.4 CARDIOMETABOLIC DISEASES
- 11.4.1 EXPANDING RNA THERAPEUTICS FOR CARDIOVASCULAR DISEASES TO MAKE CARDIOMETABOLIC DISEASES FASTEST-GROWING THERAPEUTIC AREA
- 11.5 OTHER THERAPEUTIC AREAS
12 OLIGONUCLEOTIDE-BASED DRUGS MARKET, BY END USER
- 12.1 INTRODUCTION
- 12.2 SPECIALTY CLINICS
- 12.2.1 GROWING NETWORK OF SPECIALIZED RARE DISEASE TREATMENT CENTERS TO MAINTAIN SPECIALTY CLINICS AS LARGEST END-USER SEGMENT
- 12.3 HOSPITALS
- 12.3.1 COMPLEX PATIENT MANAGEMENT AND ADMINISTRATION OF ADVANCED OLIGONUCLEOTIDE THERAPIES TO CONTINUE TO SUPPORT HOSPITAL DEMAND
- 12.4 HOME CARE SETTINGS
- 12.4.1 SHIFT TOWARD CONVENIENT DOSING AND SELF-ADMINISTRATION TO MAKE HOME CARE SETTINGS FASTEST-GROWING END-USER SEGMENT
- 12.5 OTHER END USERS
13 SYNTHESIZED OLIGONUCLEOTIDES MARKET, BY OLIGO TYPE
- 13.1 INTRODUCTION
- 13.2 PRIMERS
- 13.2.1 WIDESPREAD USE OF PRIMERS ACROSS RESEARCH, DIAGNOSTICS, AND THERAPEUTIC DEVELOPMENT TO FUEL GROWTH
- 13.3 PROBES
- 13.3.1 EXPANDING MOLECULAR DIAGNOSTICS AND PRECISION MEDICINE TO DRIVE STRONG DEMAND FOR PROBES
- 13.4 DNA OLIGONUCLEOTIDES
- 13.4.1 BROAD APPLICABILITY ACROSS LIFE SCIENCE RESEARCH AND DIAGNOSTICS TO DRIVE SIGNIFICANT MARKET SHARE FOR DNA OLIGOS
- 13.5 RNA OLIGONUCLEOTIDES
- 13.5.1 RAPID GROWTH OF RNA THERAPEUTICS AND GENE-EDITING TECHNOLOGIES TO DRIVE MARKET MOMENTUM FOR RNA OLIGOS
- 13.6 OTHER OLIGONUCLEOTIDES
14 SYNTHESIZED OLIGONUCLEOTIDES MARKET, BY TYPE
- 14.1 INTRODUCTION
- 14.2 CUSTOM OLIGONUCLEOTIDES
- 14.2.1 RAPID CLINICAL AND COMMERCIAL EXPANSION OF CHEMICALLY MODIFIED ANTISENSE AND SIRNA THERAPEUTICS TO MAKE CUSTOM OLIGONUCLEOTIDES FASTEST-GROWING SEGMENT
- 14.3 PREDESIGNED OLIGONUCLEOTIDES
- 14.3.1 PREDESIGNED OLIGONUCLEOTIDES CONTINUE TO WITNESS STEADY DEMAND OWING TO WIDESPREAD USE IN ROUTINE RESEARCH AND MOLECULAR DIAGNOSTICS
15 SYNTHESIZED OLIGONUCLEOTIDES MARKET, BY APPLICATION
- 15.1 INTRODUCTION
- 15.2 RESEARCH APPLICATIONS
- 15.2.1 PCR
- 15.2.1.1 Widespread adoption of PCR across life science research to drive market growth
- 15.2.2 NGS
- 15.2.2.1 Sequencing to continue to expand with increasing adoption of next-generation sequencing technologies
- 15.2.3 OTHER RESEARCH APPLICATIONS
- 15.2.1 PCR
- 15.3 THERAEPUTIC DEVELOPMENT
- 15.3.1 EXPANDING OLIGONUCLEOTIDE DRUG PIPELINES TO SUPPORT GROWTH OF MARKET FOR THERAPEUTIC DEVELOPMENT APPLICATIONS
- 15.4 DIAGNOSTIC APPLICATIONS
- 15.4.1 INCREASING ADOPTION OF MOLECULAR DIAGNOSTICS AND PRECISION MEDICINE TO EXPAND MARKET FOR DIAGNOSTIC APPLICATIONS
16 SYNTHESIZED OLIGONUCLEOTIDES MARKET, BY END USER
- 16.1 INTRODUCTION
- 16.2 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 16.2.1 EXPANDING OLIGONUCLEOTIDE DRUG PIPELINES TO MAKE PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES LARGEST END-USER SEGMENT
- 16.3 CROS & CDMOS
- 16.3.1 INCREASING OUTSOURCING OF OLIGONUCLEOTIDE DRUG DEVELOPMENT TO DRIVE FASTEST GROWTH AMONG CROS & CDMOS
- 16.4 DIAGNOSTIC COMPANIES & CLINICAL LABORATORIES
- 16.4.1 GROWING ADOPTION OF MOLECULAR DIAGNOSTICS AND PRECISION MEDICINE TO DRIVE DEMAND
- 16.5 ACADEMIC & RESEARCH INSTITUTES
- 16.5.1 EXPANDING GENOMICS AND LIFE SCIENCE RESEARCH TO SUSTAIN DEMAND FROM ACADEMIC & RESEARCH INSTITUTES
17 OLIGONUCLEOTIDE SYNTHESIS PRODUCTS MARKET, BY TYPE
- 17.1 INTRODUCTION
- 17.2 OLIGONUCLEOTIDE SYNTHESIS REAGENTS & CONSUMABLES
- 17.2.1 OLIGONUCLEOTIDE SYNTHESIS REAGENTS
- 17.2.1.1 Phosphoramidite building blocks
- 17.2.1.1.1 DNA phosphoramidites
- 17.2.1.1.1.1 Steady, high-volume primer, probe, and gene-synthesis demand to anchor DNA phosphoramidites as largest phosphoramidite revenue category
- 17.2.1.1.2 RNA phosphoramidites
- 17.2.1.1.2.1 Expansion of siRNA and CRISPR guide RNA therapeutic pipeline to make RNA phosphoramidites fastest-growing phosphoramidite category
- 17.2.1.1.3 Modified phosphoramidites
- 17.2.1.1.3.1 Modified phosphoramidites to continue to gain importance as oligonucleotide complexity increases
- 17.2.1.1.1 DNA phosphoramidites
- 17.2.1.2 Activators/Coupling reagents
- 17.2.1.2.1 Migration from standard tetrazole to ETT- and BTT-based activators to raise coupling efficiency in GMP-scale RNA and modified-oligo synthesis
- 17.2.1.3 Deprotection reagents
- 17.2.1.3.1 Rising synthesis throughput and demand for milder, modification-compatible deprotection chemistries to sustain detritylation reagent consumption
- 17.2.1.4 Capping reagents
- 17.2.1.4.1 Tightening n-1 impurity specifications for therapeutic oligonucleotides to lift demand for validated, high-purity capping reagent lots
- 17.2.1.5 Other reagents
- 17.2.1.1 Phosphoramidite building blocks
- 17.2.2 SOLID SUPPORTS
- 17.2.2.1 Shift toward high-loading co-polymer CPG and single-use synthesis cassettes to support long-chain, GMP-scale oligonucleotide production
- 17.2.3 OLIGO-SPECIFIC PURIFICATION & QC CONSUMABLES
- 17.2.3.1 Tightening GMP purity specifications for therapeutic oligonucleotides to drive demand for purification and QC consumables
- 17.2.1 OLIGONUCLEOTIDE SYNTHESIS REAGENTS
- 17.3 OLIGONUCLEOTIDE SYNTHESIS EQUIPMENT
- 17.3.1 ADOPTION OF FLOW-THROUGH, GMP-COMPLIANT SYNTHESIS PLATFORMS TO SCALE OLIGONUCLEOTIDE MANUFACTURING FROM RESEARCH THROUGH COMMERCIAL PRODUCTION
18 OLIGONUCLEOTIDE SYNTHESIS PRODUCTS MARKET, BY APPLICATION
- 18.1 INTRODUCTION
- 18.2 RESEARCH APPLICATIONS
- 18.2.1 HIGH-VOLUME CONSUMPTION OF SYNTHESIS PRODUCTS ACROSS GENOMICS AND MOLECULAR BIOLOGY RESEARCH TO DRIVE GROWTH
- 18.3 THERAPEUTIC DEVELOPMENT
- 18.3.1 EXPANDING OLIGONUCLEOTIDE DRUG PIPELINES TO BOOST MARKET
- 18.4 DIAGNOSTIC APPLICATIONS
- 18.4.1 DIAGNOSTICS APPLICATIONS TO CONTINUE TO EXPAND WITH INCREASING ADOPTION OF MOLECULAR DIAGNOSTICS AND PRECISION MEDICINE
19 OLIGONUCLEOTIDE SYNTHESIS PRODUCTS MARKET, BY END USER
- 19.1 INTRODUCTION
- 19.2 PHARMACEUTICAL & BIOTECHNOLOGY COMPANIES
- 19.2.1 INCREASING INVESTMENTS IN OLIGONUCLEOTIDE DRUG DEVELOPMENT AND MANUFACTURING TO SUPPORT MARKET GROWTH
- 19.3 CROS & CDMOS
- 19.3.1 INCREASING OUTSOURCING OF OLIGONUCLEOTIDE MANUFACTURING TO DRIVE MARKET GROWTH
- 19.4 DIAGNOSTIC COMPANIES & CLINICAL LABORATORIES
- 19.4.1 EXPANDED USE OF OLIGONUCLEOTIDE SYNTHESIS PRODUCTS WITH GROWTH OF MOLECULAR DIAGNOSTICS TO BOOST DEMAND
- 19.5 ACADEMIC & RESEARCH INSTITUTES
- 19.5.1 ACADEMICS & RESEARCH INSTITUTES TO CONTINUE TO PROVIDE STABLE DEMAND DRIVEN BY EXPANDING GENOMICS AND LIFE SCIENCE RESEARCH
20 OLIGONUCLEOTIDE SYNTHESIS MARKET, BY REGION
- 20.1 INTRODUCTION
- 20.2 NORTH AMERICA
- 20.2.1 US
- 20.2.1.1 Mature ecosystem across oligo-based therapeutics, synthesized oligonucleotides, and oligonucleotide synthesis products to drive market growth
- 20.2.2 CANADA
- 20.2.2.1 Strong academic research ecosystem to support market growth
- 20.2.1 US
- 20.3 EUROPE
- 20.3.1 GERMANY
- 20.3.1.1 Established capabilities for development and manufacturing of oligo-based therapeutics to drive market growth
- 20.3.2 UK
- 20.3.2.1 Established national programs to encourage utilization of oligonucleotide synthesis products
- 20.3.3 FRANCE
- 20.3.3.1 Increase in RNA-related research by biotechnology companies and academic institutions to drive market growth
- 20.3.4 ITALY
- 20.3.4.1 High demand for molecular diagnostics to favor adoption of oligonucleotide synthesis products
- 20.3.5 SPAIN
- 20.3.5.1 Government organizations investing in oligonucleotide-related research activities to drive market growth
- 20.3.6 REST OF EUROPE
- 20.3.1 GERMANY
- 20.4 ASIA PACIFIC
- 20.4.1 JAPAN
- 20.4.1.1 Expanding collaboration between pharma companies and academic institutions for development of oligonucleotide therapeutics to drive market growth
- 20.4.2 CHINA
- 20.4.2.1 Robust network of domestic companies offering oligonucleotide products to support market growth
- 20.4.3 INDIA
- 20.4.3.1 Expanding presence of domestic service providers to offer high-quality DNA and RNA oligonucleotides for research and diagnostics
- 20.4.4 SOUTH KOREA
- 20.4.4.1 High demand for custom oligonucleotide synthesis services to support market growth
- 20.4.5 AUSTRALIA
- 20.4.5.1 Well-established biomedical research sector to favor utilization of oligonucleotide synthesis products
- 20.4.6 REST OF ASIA PACIFIC
- 20.4.1 JAPAN
- 20.5 LATIN AMERICA
- 20.5.1 BRAZIL
- 20.5.1.1 Government initiatives aimed at strengthening genomic surveillance to offer market expansion opportunities
- 20.5.2 MEXICO
- 20.5.2.1 Growing network of pharmaceutical manufacturers and diagnostic laboratories to offer market expansion opportunities
- 20.5.3 ARGENTINA
- 20.5.3.1 Increasing investment by academic institutions in oligonucleotide-based research to offer market expansion opportunities
- 20.5.4 REST OF LATIN AMERICA
- 20.5.1 BRAZIL
- 20.6 MIDDLE EAST
- 20.6.1 GCC COUNTRIES
- 20.6.1.1 Saudi Arabia
- 20.6.1.1.1 National genomics initiatives to encourage adoption of oligonucleotide synthesis products
- 20.6.1.2 UAE
- 20.6.1.2.1 Government-driven initiatives and substantial investments to improve UAE's capabilities in life science industry
- 20.6.1.3 Rest of GCC Countries
- 20.6.1.1 Saudi Arabia
- 20.6.2 REST OF MIDDLE EAST
- 20.6.1 GCC COUNTRIES
- 20.7 AFRICA
- 20.7.1 GROWING INVESTMENTS IN PUBLIC HEALTH DIAGNOSTICS AND GENOMIC SURVEILLANCE ACTIVITIES TO DRIVE MARKET GROWTH
21 COMPETITIVE LANDSCAPE
- 21.1 INTRODUCTION
- 21.2 KEY PLAYER STRATEGIES/RIGHT TO WIN
- 21.2.1 KEY PLAYER STRATEGIES IN OLIGONUCLEOTIDE-BASED DRUGS MARKET, 2023-2026
- 21.2.2 KEY PLAYER STRATEGIES IN OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES MARKET, 2023-2026
- 21.3 REVENUE ANALYSIS, 2021-2025
- 21.3.1 REVENUE ANALYSIS FOR OLIGONUCLEOTIDE-BASED DRUGS MARKET, 2021-2025
- 21.3.2 REVENUE ANALYSIS FOR OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES MARKET, 2021-2025
- 21.4 MARKET SHARE ANALYSIS, 2025
- 21.4.1 MARKET SHARE ANALYSIS FOR OLIGONUCLEOTIDE-BASED DRUGS MARKET, 2025
- 21.4.2 MARKET SHARE ANALYSIS FOR OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES MARKET, 2025
- 21.5 COMPANY EVALUATION MATRIX: KEY PLAYERS (OLIGONUCLEOTIDE-BASED DRUGS MARKET), 2025
- 21.5.1 STARS
- 21.5.2 EMERGING LEADERS
- 21.5.3 PERVASIVE PLAYERS
- 21.5.4 PARTICIPANTS
- 21.5.5 COMPANY FOOTPRINT: OLIGONUCLEOTIDE-BASED DRUGS MARKET, 2025
- 21.5.5.1 Company footprint
- 21.5.5.2 Region footprint
- 21.5.5.3 Drug type footprint
- 21.5.5.4 Therapeutic area footprint
- 21.6 COMPANY EVALUATION MATRIX: KEY PLAYERS (OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES MARKET), 2025
- 21.6.1 STARS
- 21.6.2 EMERGING LEADERS
- 21.6.3 PERVASIVE PLAYERS
- 21.6.4 PARTICIPANTS
- 21.6.5 COMPANY FOOTPRINT: OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES MARKET, 2025
- 21.6.5.1 Company footprint
- 21.6.5.2 Region footprint
- 21.6.5.3 Product type footprint
- 21.7 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2024
- 21.7.1 PROGRESSIVE COMPANIES
- 21.7.2 RESPONSIVE COMPANIES
- 21.7.3 DYNAMIC COMPANIES
- 21.7.4 STARTING BLOCKS
- 21.7.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 21.7.5.1 Detailed list of key startups/SMEs
- 21.7.5.2 Competitive benchmarking of key startups/SMEs
- 21.8 BRAND/PRODUCT COMPARATIVE ANALYSIS
- 21.9 COMPANY VALUATION & FINANCIAL METRICS
- 21.9.1 COMPANY VALUATION & FINANCIAL METRICS FOR OLIGONUCLEOTIDE SYNTHESIS PRODUCTS & SYNTHESIZED OLIGONUCLEOTIDES PLAYERS
- 21.9.2 COMPANY VALUATION & FINANCIAL METRICS FOR OLIGONUCLEOTIDE-BASE DRUGS PLAYERS
- 21.10 COMPETITIVE SCENARIO
- 21.10.1 PRODUCT APPROVALS
- 21.10.2 DEALS
- 21.10.3 EXPANSIONS
22 COMPANY PROFILES
- 22.1 OLIGONUCLEOTIDE-BASED DRUG COMPANIES
- 22.1.1 ALNYLAM PHARMACEUTICALS, INC.
- 22.1.1.1 Business overview
- 22.1.1.2 Products offered
- 22.1.1.3 Recent developments
- 22.1.1.3.1 Product approvals
- 22.1.1.3.2 Deals
- 22.1.1.3.3 Expansions
- 22.1.1.4 MnM view
- 22.1.1.4.1 Key strengths
- 22.1.1.4.2 Strategic choices
- 22.1.1.4.3 Weaknesses & competitive threats
- 22.1.2 BIOGEN INC.
- 22.1.2.1 Business overview
- 22.1.2.2 Products offered
- 22.1.2.3 Recent developments
- 22.1.2.3.1 Product approvals
- 22.1.2.3.2 Deals
- 22.1.2.3.3 Expansions
- 22.1.2.4 MnM view
- 22.1.2.4.1 Key strengths
- 22.1.2.4.2 Strategic choices
- 22.1.2.4.3 Weaknesses & competitive threats
- 22.1.3 NOVARTIS AG
- 22.1.3.1 Business overview
- 22.1.3.2 Products offered
- 22.1.3.3 Recent developments
- 22.1.3.3.1 Product approvals
- 22.1.3.3.2 Deals
- 22.1.3.4 MnM view
- 22.1.3.4.1 Key strengths
- 22.1.3.4.2 Strategic choices
- 22.1.3.4.3 Weaknesses & competitive threats
- 22.1.4 SAREPTA THERAPEUTICS, INC.
- 22.1.4.1 Business overview
- 22.1.4.2 Products offered
- 22.1.4.3 Recent developments
- 22.1.4.3.1 Product approvals
- 22.1.4.3.2 Deals
- 22.1.4.3.3 Expansions
- 22.1.4.4 MnM view
- 22.1.4.4.1 Key strengths
- 22.1.4.4.2 Strategic choices
- 22.1.4.4.3 Weaknesses & competitive threats
- 22.1.5 ASTELLAS PHARMA INC.
- 22.1.5.1 Business overview
- 22.1.5.2 Products offered
- 22.1.5.3 Recent developments
- 22.1.5.3.1 Product approvals
- 22.1.5.3.2 Deals
- 22.1.5.4 MnM view
- 22.1.5.4.1 Key strengths
- 22.1.5.4.2 Strategic choices
- 22.1.5.4.3 Weaknesses & competitive threats
- 22.1.6 ASTRAZENECA
- 22.1.6.1 Business overview
- 22.1.6.2 Products offered
- 22.1.6.3 Recent developments
- 22.1.6.3.1 Product approvals
- 22.1.6.3.2 Deals
- 22.1.7 JAZZ PHARMACEUTICALS PLC
- 22.1.7.1 Business overview
- 22.1.7.2 Products offered
- 22.1.8 GERON CORPORATION
- 22.1.8.1 Business overview
- 22.1.8.2 Products offered
- 22.1.8.3 Recent developments
- 22.1.8.3.1 Product approvals
- 22.1.8.3.2 Deals
- 22.1.9 IONIS PHARMACEUTICALS, INC.
- 22.1.9.1 Business overview
- 22.1.9.2 Products offered
- 22.1.9.3 Recent developments
- 22.1.9.3.1 Product approvals
- 22.1.9.3.2 Deals
- 22.1.9.3.3 Expansions
- 22.1.10 NIPPON SHINYAKU, CO. LTD. (NS PHARMA, INC.)
- 22.1.10.1 Business overview
- 22.1.10.2 Products offered
- 22.1.10.3 Recent developments
- 22.1.10.3.1 Deals
- 22.1.11 NOVO NORDISK A/S
- 22.1.11.1 Business overview
- 22.1.11.2 Products offered
- 22.1.11.3 Recent developments
- 22.1.11.3.1 Product approvals
- 22.1.12 ARROWHEAD PHARMACEUTICALS, INC.
- 22.1.12.1 Business overview
- 22.1.12.2 Products offered
- 22.1.12.3 Recent developments
- 22.1.12.3.1 Product launches & approvals
- 22.1.12.3.2 Deals
- 22.1.13 SANOFI
- 22.1.13.1 Business overview
- 22.1.13.2 Products offered
- 22.1.13.3 Recent developments
- 22.1.13.3.1 Product approvals
- 22.1.1 ALNYLAM PHARMACEUTICALS, INC.
- 22.2 OLIGONUCLEOTIDE SYNTHESIS & SYNTHESIZED OLIGONUCLEOTIDE COMPANIES
- 22.2.1 THERMO FISHER SCIENTIFIC INC.
- 22.2.1.1 Business overview
- 22.2.1.2 Products offered
- 22.2.1.3 Recent developments
- 22.2.1.3.1 Expansions
- 22.2.1.4 MnM view
- 22.2.1.4.1 Key strengths
- 22.2.1.4.2 Strategic choices
- 22.2.1.4.3 Weaknesses & competitive threats
- 22.2.2 MERCK KGAA
- 22.2.2.1 Business overview
- 22.2.2.2 Products offered
- 22.2.2.3 Recent developments
- 22.2.2.3.1 Expansions
- 22.2.2.4 MnM view
- 22.2.2.4.1 Key strengths
- 22.2.2.4.2 Strategic choices
- 22.2.2.4.3 Weaknesses & competitive threats
- 22.2.3 DANAHER CORPORATION
- 22.2.3.1 Business overview
- 22.2.3.2 Products offered
- 22.2.3.3 Recent developments
- 22.2.3.3.1 Service launches
- 22.2.3.3.2 Deals
- 22.2.3.3.3 Expansions
- 22.2.3.4 MnM view
- 22.2.3.4.1 Key strengths
- 22.2.3.4.2 Strategic choices
- 22.2.3.4.3 Weaknesses & competitive threats
- 22.2.4 EUROFINS SCIENTIFIC
- 22.2.4.1 Business overview
- 22.2.4.2 Products offered
- 22.2.4.3 Recent developments
- 22.2.4.3.1 Deals
- 22.2.4.3.2 Expansions
- 22.2.4.4 MnM view
- 22.2.4.4.1 Key strengths
- 22.2.4.4.2 Strategic choices
- 22.2.4.4.3 Weaknesses & competitive threats
- 22.2.5 AGILENT TECHNOLOGIES, INC.
- 22.2.5.1 Business overview
- 22.2.5.2 Products offered
- 22.2.5.3 Recent developments
- 22.2.5.3.1 Deals
- 22.2.5.3.2 Expansions
- 22.2.6 LGC LIMITED
- 22.2.6.1 Business overview
- 22.2.6.2 Products offered
- 22.2.6.3 Recent developments
- 22.2.6.3.1 Deals
- 22.2.6.4 MnM view
- 22.2.6.4.1 Key strengths
- 22.2.6.4.2 Strategic choices
- 22.2.6.4.3 Weaknesses & competitive threats
- 22.2.7 TWIST BIOSCIENCE
- 22.2.7.1 Business overview
- 22.2.7.2 Products offered
- 22.2.7.3 Recent developments
- 22.2.7.3.1 Product/Service launches
- 22.2.7.3.2 Deals
- 22.2.8 GENSCRIPT
- 22.2.8.1 Business overview
- 22.2.8.2 Products offered
- 22.2.8.3 Recent developments
- 22.2.8.3.1 Product/Service launches
- 22.2.8.3.2 Deals
- 22.2.8.3.3 Expansions
- 22.2.9 MARAVAI LIFESCIENCES
- 22.2.9.1 Business overview
- 22.2.9.2 Products offered
- 22.2.9.3 Recent developments
- 22.2.9.3.1 Product/Service launches
- 22.2.9.3.2 Deals
- 22.2.9.3.3 Expansions
- 22.2.9.4 MnM view
- 22.2.9.4.1 Key strengths
- 22.2.9.4.2 Strategic choices
- 22.2.9.4.3 Weaknesses & competitive threats
- 22.2.10 KANEKA CORPORATION
- 22.2.10.1 Business overview
- 22.2.10.2 Products offered
- 22.2.10.3 Recent developments
- 22.2.10.3.1 Expansions
- 22.2.11 AZENTA US INC.
- 22.2.11.1 Business overview
- 22.2.11.2 Products offered
- 22.2.11.3 Recent developments
- 22.2.11.3.1 Product/Service launches
- 22.2.11.3.2 Deals
- 22.2.12 OLIGOMAKER APS (PART OF TAG COPENHAGEN A/S)
- 22.2.12.1 Business overview
- 22.2.12.2 Products offered
- 22.2.13 BIOLEGIO B.V.
- 22.2.13.1 Business overview
- 22.2.13.2 Products offered
- 22.2.14 BIOLYTIC LAB PERFORMANCE, INC.
- 22.2.14.1 Business overview
- 22.2.14.2 Products offered
- 22.2.14.3 Recent developments
- 22.2.14.3.1 Product/Service launches
- 22.2.15 REVVITY (THROUGH SUBSIDIARY HORIZON DISCOVERY LTD.)
- 22.2.15.1 Business overview
- 22.2.15.2 Products offered
- 22.2.15.3 Recent developments
- 22.2.15.3.1 Product/Service launches
- 22.2.16 BIO-SYNTHESIS, INC.
- 22.2.16.1 Business overview
- 22.2.16.2 Products offered
- 22.2.17 CREATIVE BIOGENE
- 22.2.17.1 Business overview
- 22.2.17.2 Products offered
- 22.2.18 REPROCELL INC. (THROUGH SUBSIDIARY BIOSERVE)
- 22.2.18.1 Business overview
- 22.2.18.2 Products offered
- 22.2.19 BIOCOMMA LIMITED
- 22.2.19.1 Business overview
- 22.2.19.2 Products offered
- 22.2.1 THERMO FISHER SCIENTIFIC INC.
23 RESEARCH METHODOLOGY
- 23.1 RESEARCH DATA
- 23.1.1 SECONDARY DATA
- 23.1.1.1 Key secondary sources
- 23.1.1.2 Key data from secondary research
- 23.1.2 PRIMARY DATA
- 23.1.2.1 Key primary participants
- 23.1.2.2 Breakdown of primary interviews
- 23.1.2.3 Key data from primary sources
- 23.1.1 SECONDARY DATA
- 23.2 MARKET SIZE ESTIMATION
- 23.2.1 GLOBAL OLIGONUCLEOTIDE SYNTHESIS MARKET ESTIMATION, 2025
- 23.2.1.1 Approach 1: Company revenue analysis-based estimation (bottom-up)
- 23.2.1.2 Approach 2: Secondary research
- 23.2.1.3 Approach 3: Primary research
- 23.2.1.4 Key industry insights
- 23.2.1.5 Approach 3: MnM repository analysis
- 23.2.2 SEGMENTAL MARKET SIZE ESTIMATION, 2025
- 23.2.1 GLOBAL OLIGONUCLEOTIDE SYNTHESIS MARKET ESTIMATION, 2025
- 23.3 MARKET GROWTH RATE PROJECTIONS
- 23.4 DATA TRIANGULATION
- 23.5 RESEARCH ASSUMPTIONS
- 23.6 RESEARCH LIMITATIONS & RISK ASSESSMENT
24 APPENDIX
- 24.1 DISCUSSION GUIDE
- 24.2 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 24.3 CUSTOMIZATION OPTIONS
- 24.4 RELATED REPORTS
- 24.5 AUTHOR DETAILS