|
시장보고서
상품코드
2126795
철근 시장 예측(-2031년) : 유형별, 프로세스별, 코팅 유형별, 봉 사이즈별, 최종 용도 산업별, 지역별Steel Rebar Market by Type (Deformed, Mild), Process (BOS, EAF), Coating Type (Plain, Galvanized, Epoxy Coated), Bar Size (#3, #4, #5, #8), End-use Sector (Infrastructure, Housing, Industrial), and Region - Global Forecast to 2031 |
||||||

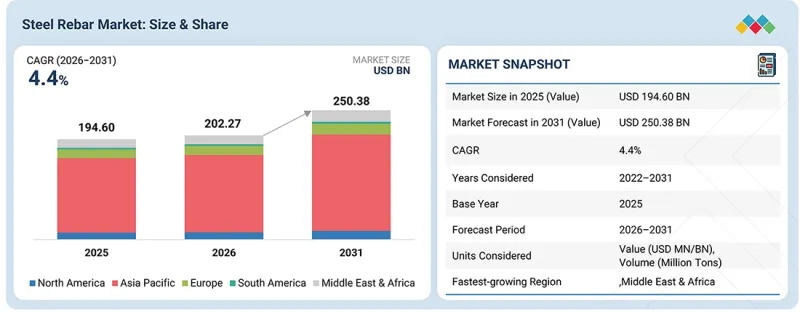
철근 시장 규모는 2026년 2,022억 7,000만 달러에서 2031년까지 2,503억 8,000만 달러로 확대하며, 예측 기간 중 CAGR은 4.4%에 달할 것으로 전망되고 있습니다.
이러한 성장은 인프라, 건축, 산업 분야의 건설 활동 증가에 힘입어 견인될 것으로 예상됩니다. 고속도로, 교량, 철도, 도시 인프라 프로젝트, 재생에너지 사업, 주택 개발에 대한 투자 확대와 같은 요인들이 이 성장에 크게 기여할 것으로 전망됩니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(100만/10억 달러) 수량(100만 톤) |
| 부문 | 유형별, 프로세스별, 코팅 유형별, 봉 사이즈별, 최종 용도 산업별, 지역별 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 중동 및 아프리카, 남미 |
또한 도시화, 인구 증가 및 산업화에 따라 철근 수요가 증가하고, 다양한 분야에서 철근 콘크리트 구조물의 개발이 진행될 것으로 예상됩니다.
"2026-2031년에 전기 아크로(EAF) 부문이 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
저탄소 및 지속가능한 철강 생산에 대한 관심이 높아짐에 따라 EAF 부문은 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. EAF 공정을 통해 철강 제조업체는 더 많은 철스크랩을 활용할 수 있게 되어, 미활용 원료에 대한 의존도가 낮아지고 철강 제조에 따른 탄소 강도가 감소합니다. 또한 정부와 철강 제조업체 모두 탈탄소화 및 친환경 철강 생산에 대한 중요성이 부각되면서 EAF 부문은 인상적인 성장을 달성하고 있습니다. 전기 아크로(EAF)를 활용한 생산 시설에 대한 투자 증가, 철스크랩의 풍부한 공급, 저탄소 철근에 대한 수요 확대와 같은 요인들이 이 부문의 성장을 촉진할 것으로 예상됩니다.
"#3 부문은 2026-2031년에 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
#3 규격 철근 카테고리는 주택 건설 및 소규모에서 중규모 건설 용도로의 사용이 증가하고 있으며, 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예상됩니다. #3 규격 철근은 취급, 굽힘 가공 및 설치가 용이하여 슬래브, 벽, 기초, 차도 및 다양한 철근 콘크리트 구조물에 적합합니다. #3 규격 카테고리의 인기가 높아지는 것은 주택 건설 증가와 소규모에서 중규모 인프라 프로젝트의 증가에 기인한 것으로 보입니다. 도시화, 주택 개발, 효율적인 철근 솔루션에 대한 수요와 같은 요인들이 예측 기간 중 #3 철근 규격 카테고리의 성장을 촉진할 것으로 전망됩니다.
"2026-2031년에 인프라 부문이 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
최종 용도 부문별로는 예측 기간 중 인프라 부문이 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예상됩니다. 이러한 성장은 교통, 도시화, 에너지, 일반 인프라 등 다양한 부문의 인프라 개발 프로젝트에 대한 투자 증가에 의해 주도되고 있습니다. 또한 이 부문의 성장은 도로, 교량,철도, 공항, 항만, 재생 가능 에너지 인프라의 건설 증가와도 관련이 있습니다. 또한 개발도상국의 현대화 및 대규모 인프라 프로젝트에 대한 정부 지출이 철근 수요 증가에 기여하고 있습니다. 또한 도시화와 인프라 개보수 수요의 증가도 철근 소비 증가로 이어지고 있습니다.
"2026-2031년에 무피복 탄소강 부문이 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
무피복 탄소강 부문은 피복 유형 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 이러한 성장은 기존 건설 프로젝트에서 무피복 탄소강 철근의 광범위한 사용과 피복 강철근에 비해 높은 비용 효율성에 기인한 것으로 보입니다. 비피복 탄소강 부문은 제품의 접근성, 견고한 제조 기반, 그리고 주택, 상업, 산업, 인프라 프로젝트에 대한 적합성으로 인해 급속히 확대될 것으로 예상됩니다. 또한 신흥 국가에서의 건설 활동 증가와 인프라 프로젝트에 대한 투자 확대가 무피복 탄소강 철근의 수요를 견인할 것으로 전망됩니다.
"2026-2031년에 이형 철근 부문은 일반 철근 부문보다 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
유형별로 보면 이형 철근 부문은 일반 철근에 비해 인장 강도가 뛰어나고, 콘크리트와의 접착력이 강하며, 하중 지지 능력이 높기 때문에 예측 기간 중 높은 연평균 성장률(CAGR)을 기록할 전망입니다. 이 부문은 주택, 상업, 산업, 인프라 건설 등 각 용도에서 그 중요성이 커지고 있습니다. 대규모 건설 프로젝트에서 내구성이 높고 강인한 철근에 대한 수요가 증가하고 있는 것이 이형 철근의 보급을 지원하는 요인 중 하나입니다. 또한 인프라 투자 확대, 도시화 및 고층 빌딩 건설이 예측 기간 중 해당 부문의 성장을 촉진할 것으로 전망됩니다.
"중동 및 아프리카는 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다."
중동 및 아프리카는 주택, 산업, 도시 건설 프로젝트에 대한 투자 증가에 힘입어 예측 기간 중 전 세계 철근 시장에서 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 예상됩니다. 이 지역에서는 특히 교통 인프라, 상업용 건물, 주택 프로젝트, 에너지 인프라 사업 분야에서 대규모 건설 활동이 진행되고 있습니다. 또한 정부의 다각화 프로젝트 및 관광 부문에 대한 투자도 이러한 건설 붐에 기여하고 있습니다. 급속한 도시화와 인구 증가로 인해 철근 콘크리트 및 철근에 대한 수요가 증가할 것으로 예상됩니다.
대상 기업: 이 보고서에서는 ArcelorMittal(룩셈부르크), Nucor Corporation(미국), NLMK Group(러시아), Nippon Steel Corporation(일본), Tata Steel(인도)을 비롯한 기업이 다루어지고 있습니다.
본 조사에서는 철근 시장의 주요 기업에 대해 기업 개요, 최근 동향 및 주요 시장 전략을 포함한 상세한 경쟁 분석을 담고 있습니다.
조사 범위
본 조사 보고서에서는 철근 시장을 유형별(연강 철근, 이형 철근), 코팅 유형별(무도장 탄소강, 에폭시 코팅, 아연 도금), 봉 사이즈별(#3, #4, #5, #8, 기타 크기), 최종 용도 산업별(인프라, 주택, 산업), 공정별(BOS, EAF) 및 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류하고 있습니다. 이 보고서의 범위에는 철근 시장의 성장에 영향을 미치는 촉진요인, 제약 요인, 과제 및 기회에 대한 상세한 정보가 포함되어 있습니다. 주요 업계 플레이어에 대해서는 사업 개요, 제공 제품 및 시장과 관련된 제휴, 인수, 사업 확장 등의 주요 전략에 대한 인사이트를 제공하기 위해 상세한 분석이 이루어졌습니다. 또한 이 보고서에서는 철근 시장 생태계내 신생 스타트업 기업의 경쟁 분석에 대해서도 다루고 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 시장 선도 기업 및 신규 진입 기업에게 철근 시장 전체 및 각 하위 부문의 매출에 관한 가장 정확한 추정치를 제공합니다. 이 보고서는 이해관계자들이 경쟁 구도를 이해하고, 자사의 사업 포지셔닝을 최적화하기 위한 추가적인 인사이트를 얻어 적절한 시장 진입 전략을 수립하는 데 도움이 됩니다. 또한 이 보고서는 이해관계자들이 시장을 이해하는 데 도움을 주며, 주요 시장 촉진요인, 제약 요인, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
주요 촉진요인 분석(신흥 국가의 도시 대중교통 시스템 확대, 재생 가능 에너지 인프라에 따른 견고한 수요, 신흥 경제국의 재공업화 및 제조업 단지 개발), 제약 요인(수입 관세 및 반덤핑 조치, 스크랩 및 코크스용 석탄 가격 변동),기회(수소 기반 DRI를 활용한 친환경 철근 및 프리캐스트·모듈식 건축과의 통합), 그리고 과제(신흥 경제국의 재활용 인프라 부족 및 농촌 지역 철근 공급에서 추적 불가능한 비공식 부문이 지배적인 점)에 대한 분석.
- 제품 개발/혁신: 철근 시장의 향후 기술, 연구개발 활동 및 제품·서비스 출시에 대한 상세 인사이트.
- 시장 개발: 수익성이 높은 시장에 대한 포괄적인 정보 - 이 보고서는 다양한 지역에 걸친 철근 시장을 분석합니다.
시장 다각화: 철근 시장의 신제품 및 서비스, 미개발 지역, 최근 동향 및 투자에 대한 포괄적인 정보.
- 경쟁 평가: ArcelorMittal(룩셈부르크), Nucor Corporation(미국), NLMK Group(러시아), 신일본제철(일본), Tata Steel(인도) 등 주요 기업의 시장 점유율, 성장 전략 및 서비스 제공에 대한 상세한 평가.
자주 묻는 질문
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술, 특허, 디지털 기술, AI 도입에 의한 전략적 파괴
제7장 지속가능성과 규제 상황
제8장 고객 상황과 구매 행동
제9장 철근 시장(유형별)
제10장 철근 시장(프로세스별)
제11장 철근 시장(코팅 유형별)
제12장 철근 시장(봉 사이즈별)
제13장 철근 시장(최종 용도 산업별)
제14장 철근 시장(지역별)
제15장 경쟁 구도
제16장 기업 개요
제17장 조사 방법
제18장 부록
KSA 26.09.14The steel rebar market is projected to grow from USD 202.27 billion in 2026 to USD 250.38 billion by 2031, at a CAGR of 4.4% during the forecast period. This growth is anticipated to be driven by an increase in construction activities across infrastructure, buildings, and industries. Factors such as higher investments in highways, bridges, railroads, urban infrastructure projects, renewable energy initiatives, and housing developments will significantly contribute to this growth.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million/Billion) Volume (Million Tons) |
| Segments | Type, Coating Type, Process, Bar Size, End-use Sector, and Region |
| Regions covered | North America, Asia Pacific, Europe, Middle East & Africa, and South America |
Additionally, the demand for steel reinforcement bars will rise due to urbanization, population growth, and industrialization, leading to the development of reinforced concrete structures across various sectors.
"Electric arc furnace (EAF) segment projected to exhibit the highest CAGR from 2026 to 2031"
The EAF segment is expected to witness the highest CAGR during the forecast period due to the growing preference for low-carbon and sustainable steel production. The EAF process allows steel producers to utilize a greater amount of scrap steel, which reduces their reliance on virgin raw materials and lowers the carbon intensity associated with steel manufacturing. Additionally, the EAF segment is experiencing significant growth due to the increasing emphasis on decarbonization and the production of green steel by both governments and steel manufacturers. Factors such as rising investments in EAF-based production facilities, a plentiful supply of scrap steel, and a growing demand for low-carbon rebar are expected to drive the growth of this segment.
"#3 segment projected to exhibit the highest CAGR from 2026 to 2031"
The #3 bar size category is expected to show the maximum CAGR during the forecast period owing to its rising use in residential and light-to-medium construction purposes. #3 rebars provide easy handling, bending, and installation, making them applicable for slabs, walls, footings, driveways, and various reinforced concrete constructions. The growing popularity of the #3 bar size category can be attributed to the increase in residential construction and smaller to medium-scale infrastructure projects. Factors such as urbanization, housing developments, and the demand for efficient reinforcement solutions are expected to drive the growth of the #3 bar size category during the forecast period.
"Infrastructure segment projected to exhibit the highest CAGR from 2026 to 2031"
By end-use sector, the infrastructure segment is expected to experience the highest CAGR during the forecast period. This growth is driven by increased investments in infrastructure development projects across various sectors, including transportation, urbanization, energy, and general infrastructure. The rise in this segment can also be linked to the growing construction of roads, bridges, railways, airports, ports, and renewable energy infrastructure. Additionally, government spending on modernization and major infrastructure projects in developing countries is contributing to the rising demand for steel rebars. Moreover, urbanization and the need for infrastructure upgrades are leading to an increased consumption of steel rebar.
"Plain carbon segment projected to exhibit the highest CAGR from 2026 to 2031"
The plain carbon segment is expected to experience the highest CAGR among coating types. This growth can be attributed to the widespread use of plain carbon rebars in traditional construction projects and their cost-effectiveness compared to coated alternatives. The plain carbon segment is anticipated to expand rapidly due to the product's availability, a strong manufacturing base, and its suitability for residential, commercial, industrial, and infrastructural projects. Additionally, increasing construction activities in emerging economies and rising investments in infrastructure projects are expected to drive demand for plain carbon rebar.
"Deformed segment projected to exhibit higher CAGR than mild segment from 2026 to 2031"
By type, the deformed segment is likely to register a higher CAGR over the forecast period on account of its better tensile strength, stronger bond with concrete, and load-carrying ability compared to mild steel bar. This segment is gaining significance in residential, commercial, industrial, and infrastructural construction applications. The growing need for durable and strong reinforcement in large-scale construction projects is one of the factors driving the acceptance of deformed rebar. Moreover, growing infrastructural spending, urbanization, and the construction of high-rise buildings are likely to boost the segment's growth over the forecast period.
"Middle East & Africa projected to witness highest CAGR during the forecast period"
The Middle East & Africa region is set to witness the highest CAGR in the global steel rebar market during the forecast period, driven by the increasing investment in housing, industry, and urban construction projects. There is a significant amount of construction activity taking place in the region, particularly in transport infrastructure, commercial buildings, residential projects, and energy infrastructure initiatives. Additionally, government diversification projects and investments in the tourism sector are contributing to this construction boom. It is anticipated that rapid urbanization and population growth will increase the demand for reinforced concrete and steel bars.
By Company Type: Tier 1 - 35%, Tier 2 - 40%, and Tier 3- 25%
By Designation: Executives - 21%, CXOs - 23%, and Managers - 56%
By Region: North America - 30%, Europe - 23%, Asia Pacific - 27%, South America - 5%, and Middle East & Africa - 15%
Companies Covered: ArcelorMittal (Luxembourg), Nucor Corporation (US), NLMK Group (Russia), Nippon Steel Corporation (Japan), and Tata Steel (India), among other companies, are covered in the report.
The study includes an in-depth competitive analysis of these key players in the steel rebar market, including their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the steel rebar market based on type (Mild, Deformed), coating type (Plain Carbon, Epoxy Coated, Galvanized), bar size (#3, #4, #5, #8, other bar sizes), end-use sector (Infrastructure, Housing, Industrial), process (BOS, EAF), and region (Asia Pacific, North America, Europe, South America, and the Middle East & Africa). The report's scope covers detailed information regarding the drivers, restraints, challenges, and opportunities influencing the growth of the steel rebar market. A detailed analysis of the key industry players has been done to provide insights into their business overview, products offered, and key strategies, such as partnerships, acquisitions, and expansions, associated with the market. This report also covers a competitive analysis of upcoming startups in the steel rebar market ecosystem.
Reasons to Buy the Report
The report will offer market leaders/new entrants with information on the closest approximations of the revenue numbers for the overall steel rebar market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will help stakeholders understand the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
Analysis of key drivers (Expansion of urban mass transit systems across developing economies, Resilient demand from renewable energy infrastructure, and Reindustrialization and manufacturing parks in emerging economies), restraints (Import tariffs and anti-dumping measures, and Volatility in scrap and coking coal prices), opportunities (Green steel rebar from hydrogen-based DRI, and Integration with precast and modular construction), and challenges (Lack of recycling infrastructure in emerging economies, and Untracked informal sector dominance in rural rebar supply).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the steel rebar market.
- Market Development: Comprehensive information about profitable markets-the report analyzes the steel rebar market across varied regions.
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the steel rebar market.
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players, such as ArcelorMittal (Luxembourg), Nucor Corporation (US), NLMK Group (Russia), Nippon Steel Corporation (Japan), Tata Steel (India), and others.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 STUDY SCOPE
- 1.3.1 MARKETS COVERED AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED FOR STUDY
- 1.4 CURRENCY
- 1.5 UNIT CONSIDERED
- 1.6 STAKEHOLDERS
- 1.7 LIMITATIONS
- 1.8 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 KEY INSIGHTS AND MARKET HIGHLIGHTS
- 2.2 KEY MARKET PARTICIPANTS: SHARE INSIGHTS AND STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS SHAPING STEEL REBAR MARKET
- 2.4 HIGH-GROWTH SEGMENTS & EMERGING FRONTIERS
- 2.5 SNAPSHOT: GLOBAL MARKET SIZE AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN STEEL REBAR MARKET
- 3.2 STEEL REBAR MARKET, BY TYPE AND REGION
- 3.3 STEEL REBAR MARKET, BY TYPE
- 3.4 STEEL REBAR MARKET, BY BAR SIZE
- 3.5 STEEL REBAR MARKET, BY PROCESS
- 3.6 STEEL REBAR MARKET, BY COATING TYPE
- 3.7 STEEL REBAR MARKET, BY END-USE SECTOR
- 3.8 STEEL REBAR MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Expansion of urban mass transit systems across developing economies
- 4.2.1.2 Resilient demand from renewable energy infrastructure
- 4.2.1.3 Reindustrialization and manufacturing parks in emerging economies
- 4.2.2 RESTRAINTS
- 4.2.2.1 Import tariffs and anti-dumping measures
- 4.2.2.2 Volatility in scrap and coking coal prices
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Green steel rebar from hydrogen-based DRI
- 4.2.3.2 Integration with precast and modular construction
- 4.2.4 CHALLENGES
- 4.2.4.1 Lack of recycling infrastructure in emerging economies
- 4.2.4.2 Untracked informal sector dominance in rural rebar supply
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN THE STEEL REBAR MARKET
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNTIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.4.2.1 Steel rebar - digital construction & building information modeling (BIM)
- 4.4.2.2 Steel rebar - renewable energy infrastructure
- 4.5 STRATEGIC MOVES BY TIER-1 PLAYERS
- 4.5.1 TIER 1 PLAYERS: GLOBAL LEADERS DRIVING CAPACITY EXPANSION, SUSTAINABILITY, AND VALUE-ADDED SOLUTIONS
- 4.5.1.1 Nucor corporation - expanding low-carbon rebar production and downstream reinforcement solutions
- 4.5.1.2 Arcelormittal - strengthening high-strength rebar portfolio and regional long products capacity
- 4.5.1 TIER 1 PLAYERS: GLOBAL LEADERS DRIVING CAPACITY EXPANSION, SUSTAINABILITY, AND VALUE-ADDED SOLUTIONS
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC ANALYSIS
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECASTS
- 5.2.3 GLOBAL STEEL PRODUCTION
- 5.2.4 INFRASTRUCTURE INVESTMENT IMPACT
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.4.1 PRICING ANALYSIS
- 5.4.1.1 Pricing analysis based on region
- 5.4.1 PRICING ANALYSIS
- 5.5 TRADE ANALYSIS
- 5.5.1 EXPORT SCENARIO (HS CODE 721420)
- 5.5.2 IMPORT SCENARIO (HS CODE 721420)
- 5.6 KEY CONFERENCES AND EVENTS, 2026
- 5.7 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.7.1 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.8 INVESTMENT AND FUNDING SCENARIO
- 5.9 IMPACT OF 2025 US TARIFF: STEEL REBAR MARKET
- 5.9.1 INTRODUCTION
- 5.9.2 KEY TARIFF RATES
- 5.9.3 PRICE IMPACT ANALYSIS
- 5.9.4 IMPACT ON COUNTRIES/REGIONS
- 5.9.4.1 US
- 5.9.4.2 China
- 5.9.4.3 Middle East
- 5.9.4.4 India
- 5.9.5 IMPACT ON END-USE SECTORS
6 STRATEGIC DISRUPTION THROUGH TECHNOLOGY, PATENTS, DIGITAL, AND AI ADOPTIONS
- 6.1 KEY TECHNOLOGIES
- 6.1.1 CORROSION-RESISTANT COATINGS
- 6.1.2 NON-DESTRUCTIVE TESTING (NDT)
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 REBAR TRACKING AND TAGGING
- 6.2.2 REBAR SCANNING AND DETECTION TOOLS
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 SELF-SENSING REBARS
- 6.3.2 3D PRINTING OF REBAR CAGES
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) |DIGITAL MANUFACTURING, HIGH-STRENGTH REBAR, AND LOW-CARBON PRODUCTION
- 6.4.2 MID-TERM (2027-2030) | GREEN STEEL EXPANSION, ADVANCED ALLOY REBARS, AND SMART MANUFACTURING
- 6.4.3 LONG-TERM (2030-2035+) | CARBON-NEUTRAL STEELMAKING, SMART REINFORCEMENT SYSTEMS, AND NEXT-GENERATION HIGH-PERFORMANCE REBARS
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 METHODOLOGY
- 6.5.3 STEEL REBAR MARKET, PATENT ANALYSIS, 2016-2025
- 6.6 FUTURE APPLICATIONS
- 6.6.1 HIGH-STRENGTH & HIGH-PERFORMANCE STEEL REBAR
- 6.6.2 LOW-CARBON & RECYCLED STEEL REBAR
- 6.6.3 CORROSION-RESISTANT & LONG-LIFE REINFORCEMENT
- 6.6.4 SEISMIC-RESISTANT & SPECIALTY REBAR
- 6.7 IMPACT OF AI/GEN AI ON STEEL REBAR MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES IN STEEL REBAR MARKET
- 6.7.3 INTERCONNECTED ADJACENT ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN THE ALUMINUM PLATE MARKET
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.8.1 HIGH-STRENGTH STEEL REBAR REDUCES MATERIAL REQUIREMENTS IN LARGE-SCALE STRUCTURES
- 6.8.2 CORROSION-RESISTANT REBAR EXTENDS SERVICE LIFE OF INFRASTRUCTURE
- 6.8.3 AUTOMATED CUT-AND-BEND REBAR IMPROVES CONSTRUCTION PRODUCTIVITY AND REDUCES WASTAGE
7 SUSTAINABILITY AND REGULATORY LANDSCAPE
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 LOW-CARBON AND SUSTAINABLE REINFORCEMENT STEEL
- 7.2.2 ENERGY EFFICIENCY AND CARBON EMISSION REDUCTION IN REBAR MANUFACTURING
- 7.2.3 SCRAP RECYCLING, WASTE REDUCTION, AND CIRCULAR RESOURCE UTILIZATION
- 7.3 IMPACT OF REGULATORY POLICY ON SUSTAINABILITY INITIATIVES
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 BUYER STAKEHOLDERS AND BUYING EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN THE BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS FROM VARIOUS SECTORS
- 8.5 MARKET PROFITABILITY
- 8.5.1 REVENUE POTENTIAL
- 8.5.2 COST DYNAMICS
- 8.5.3 MARGIN OPPORTUNITIES BY END-USE SECTORS
9 STEEL REBAR MARKET, BY TYPE
- 9.1 INTRODUCTION
- 9.2 DEFORMED
- 9.2.1 WIDE APPLICATIONS FOR STRUCTURAL STABILITY IN HIGH-STRENGTH CONCRETE TO DRIVE MARKET
- 9.3 MILD
- 9.3.1 DEMAND IN SPECIALIZED AND COST-EFFICIENT APPLICATIONS TO DRIVE MARKET
10 STEEL REBAR MARKET, BY PROCESS
- 10.1 INTRODUCTION
- 10.2 BASIC OXYGEN STEELMAKING
- 10.2.1 BASIC OXYGEN STEELMAKING EMPOWERS REBAR PRODUCTION AMIDST RECORD INFRASTRUCTURE INVESTMENT
- 10.3 ELECTRIC ARC FURNACE
- 10.3.1 FLEXIBLE, SUSTAINABLE, AND STRATEGICALLY ALIGNED FOR MODERN REBAR PRODUCTION
11 STEEL REBAR MARKET, BY COATING TYPE
- 11.1 INTRODUCTION
- 11.2 PLAIN CARBON STEEL REBAR
- 11.2.1 COST-EFFECTIVE AND STRUCTURALLY RELIABLE FOR STANDARD CONSTRUCTION ENVIRONMENTS TO DRIVE MARKET
- 11.3 GALVANIZED STEEL REBAR
- 11.3.1 RISING DEMAND FOR CORROSION-RESISTANT INFRASTRUCTURE SOLUTIONS TO DRIVE MARKET
- 11.4 EPOXY-COATED STEEL REBAR
- 11.4.1 STEADY DEMAND IN HIGHWAY AND MARINE INFRASTRUCTURE APPLICATIONS TO INFLUENCE MARKET
12 STEEL REBAR MARKET, BY BAR SIZE
- 12.1 INTRODUCTION
- 12.2 #3 BAR SIZE
- 12.2.1 IDEAL USE IN SWIMMING POOL FRAMES AND ROAD & HIGHWAY PAVING TO DRIVE DEMAND
- 12.3 #4 BAR SIZE
- 12.3.1 COMMON USE IN SLAB-ON-GRADE FOUNDATIONS AND WALL REINFORCEMENT TO DRIVE DEMAND
- 12.4 #5 BAR SIZE
- 12.4.1 WIDE APPLICATIONS IN BRIDGE DECKS, TRANSPORT STRUCTURES, AND MEDIUM TO HEAVY FOUNDATIONS TO DRIVE DEMAND
- 12.5 #8 BAR SIZE
- 12.5.1 SUBSTANTIAL CROSS-SECTIONAL AREA AND HIGH TENSILE STRENGTH TO DRIVE DEMAND IN HEAVY CIVIL CONSTRUCTION AND HIGH-STRENGTH CONCRETE STRUCTURES
- 12.6 OTHER BAR SIZES
13 STEEL REBAR MARKET, BY END-USE SECTOR
- 13.1 INTRODUCTION
- 13.2 INFRASTRUCTURE
- 13.2.1 RISING GLOBAL INVESTMENTS IN INFRASTRUCTURE SIGNIFICANTLY ACCELERATE STEEL REBAR DEMAND ACROSS URBAN AND TRANSPORT PROJECTS
- 13.3 HOUSING
- 13.3.1 GOVERNMENT-BACKED HOUSING INITIATIVES AND URBAN EXPANSION DRIVE CONSISTENT GROWTH IN STEEL REBAR DEMAND GLOBALLY
- 13.4 INDUSTRIAL
- 13.4.1 SURGING INVESTMENTS IN MANUFACTURING AND CLEAN ENERGY DRIVE STRONG STEEL REBAR DEMAND IN INDUSTRIAL CONSTRUCTION
14 STEEL REBAR MARKET, BY REGION
- 14.1 INTRODUCTION
- 14.2 NORTH AMERICA
- 14.2.1 US
- 14.2.1.1 Government initiatives to drive market
- 14.2.2 CANADA
- 14.2.2.1 Rise in residential and non-residential construction activities to trigger market
- 14.2.3 MEXICO
- 14.2.3.1 Government investments to drive market
- 14.2.1 US
- 14.3 ASIA PACIFIC
- 14.3.1 ASIA PACIFIC STEEL REBAR MARKET, BY COUNTRY
- 14.3.2 CHINA
- 14.3.2.1 Urban expansion and BRI infrastructure projects to drive demand
- 14.3.3 INDIA
- 14.3.3.1 Steady rise in steel rebar demand amid infrastructure expansion to drive market
- 14.3.4 JAPAN
- 14.3.4.1 Infrastructure resilience and global investments to drive demand
- 14.3.5 SOUTH KOREA
- 14.3.5.1 Industrial expansion and rapid housing and redevelopment projects to drive market
- 14.3.6 AUSTRALIA
- 14.3.6.1 Large-scale infrastructure, housing, and energy projects to drive demand
- 14.3.7 REST OF ASIA PACIFIC
- 14.4 EUROPE
- 14.4.1 EUROPE STEEL REBAR MARKET, BY COUNTRY
- 14.4.2 GERMANY
- 14.4.2.1 Infrastructure investments and government initiatives to drive market
- 14.4.3 UK
- 14.4.3.1 Rising government commitments to investments in infrastructure and improving housing sector to drive market
- 14.4.4 FRANCE
- 14.4.4.1 Surging infrastructure and housing recovery to drive market
- 14.4.5 ITALY
- 14.4.5.1 Extensive infrastructure and energy investments to drive market
- 14.4.6 SPAIN
- 14.4.6.1 Rising infrastructure and energy investments to drive demand
- 14.4.7 RUSSIA
- 14.4.7.1 Rising construction and infrastructure investments to drive market
- 14.4.8 UKRAINE
- 14.4.8.1 Reconstruction and infrastructure revitalization efforts to drive demand
- 14.4.9 TURKEY
- 14.4.9.1 Rising construction, infrastructure, and housing investments to drive demand
- 14.4.10 REST OF EUROPE
- 14.5 MIDDLE EAST & AFRICA
- 14.5.1 MIDDLE EAST & AFRICA STEEL REBAR MARKET, BY COUNTRY
- 14.5.2 GCC COUNTRIES
- 14.5.2.1 Saudi Arabia
- 14.5.2.1.1 Robust infrastructure and housing investments to drive market
- 14.5.2.2 UAE
- 14.5.2.2.1 Strong infrastructure and real estate expansion to drive demand
- 14.5.2.3 Rest of GCC countries
- 14.5.2.1 Saudi Arabia
- 14.5.3 SOUTH AFRICA
- 14.5.3.1 Robust infrastructure and real estate developments to drive demand
- 14.5.4 REST OF MIDDLE EAST & AFRICA
- 14.6 SOUTH AMERICA
- 14.6.1 BRAZIL
- 14.6.1.1 Robust infrastructure and housing initiatives to demand
- 14.6.2 ARGENTINA
- 14.6.2.1 Rising infrastructure investments and urban resilience projects to drive market
- 14.6.3 REST OF SOUTH AMERICA
- 14.6.1 BRAZIL
15 COMPETITIVE LANDSCAPE
- 15.1 OVERVIEW
- 15.2 KEY PLAYER STRATEGIES
- 15.3 MARKET SHARE ANALYSIS
- 15.4 REVENUE ANALYSIS
- 15.5 COMPANY VALUATION AND FINANCIAL METRICS
- 15.6 PRODUCT/BRAND COMPARISON
- 15.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 15.7.1 STARS
- 15.7.2 EMERGING LEADERS
- 15.7.3 PERVASIVE PLAYERS
- 15.7.4 PARTICIPANTS
- 15.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 15.7.5.1 Company footprint
- 15.7.5.2 Region footprint
- 15.7.5.3 Type footprint
- 15.7.5.4 Process footprint
- 15.7.5.5 Coating type footprint
- 15.7.5.6 Bar size footprint
- 15.7.5.7 End-use industry footprint
- 15.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 15.8.1 PROGRESSIVE COMPANIES
- 15.8.2 RESPONSIVE COMPANIES
- 15.8.3 DYNAMIC COMPANIES
- 15.8.4 STARTING BLOCKS
- 15.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 15.8.5.1 Detailed list of key startups/SMEs
- 15.8.6 COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- 15.9 COMPETITIVE SCENARIO
- 15.9.1 PRODUCT LAUNCHES
- 15.9.2 DEALS
- 15.9.3 EXPANSIONS
16 COMPANY PROFILES
- 16.1 KEY PLAYERS
- 16.1.1 NIPPON STEEL CORPORATION
- 16.1.1.1 Business overview
- 16.1.1.2 Products/Solutions/Services offered
- 16.1.1.3 Recent developments
- 16.1.1.3.1 Deals
- 16.1.1.3.2 Expansions
- 16.1.1.4 MnM view
- 16.1.1.4.1 Right to win
- 16.1.1.4.2 Strategic choices
- 16.1.1.4.3 Weaknesses and competitive threats
- 16.1.2 ARCELORMITTAL
- 16.1.2.1 Business overview
- 16.1.2.2 Products/Solutions/Services offered
- 16.1.2.3 Recent developments
- 16.1.2.3.1 Deals
- 16.1.2.3.2 Expansions
- 16.1.2.4 MnM view
- 16.1.2.4.1 Right to win
- 16.1.2.4.2 Strategic choices
- 16.1.2.4.3 Weaknesses and competitive threats
- 16.1.3 GERDAU S/A
- 16.1.3.1 Business overview
- 16.1.3.2 Products/Solutions/Services offered
- 16.1.3.3 Recent developments
- 16.1.3.3.1 Deals
- 16.1.3.4 MnM view
- 16.1.3.4.1 Right to win
- 16.1.3.4.2 Strategic choices
- 16.1.3.4.3 Weaknesses and competitive threats
- 16.1.4 NUCOR CORPORATION
- 16.1.4.1 Business overview
- 16.1.4.2 Products/Solutions/Services offered
- 16.1.4.3 Recent developments
- 16.1.4.3.1 Deals
- 16.1.4.3.2 Expansions
- 16.1.4.4 MnM view
- 16.1.4.4.1 Right to win
- 16.1.4.4.2 Strategic choices
- 16.1.4.4.3 Weaknesses and competitive threats
- 16.1.5 COMMERCIAL METALS COMPANY
- 16.1.5.1 Business overview
- 16.1.5.2 Products/Solutions/Services offered
- 16.1.5.3 Recent developments
- 16.1.5.3.1 Deals
- 16.1.5.3.2 Expansions
- 16.1.5.4 MnM view
- 16.1.5.4.1 Right to win
- 16.1.5.4.2 Strategic choices
- 16.1.5.4.3 Weaknesses and competitive threats
- 16.1.6 TATA STEEL
- 16.1.6.1 Business overview
- 16.1.6.2 Products/Solutions/Services offered
- 16.1.6.3 Recent developments
- 16.1.6.3.1 Deals
- 16.1.6.4 MnM view
- 16.1.7 STEEL AUTHORITY OF INDIA LIMITED
- 16.1.7.1 Business overview
- 16.1.7.2 Products/Solutions/Services offered
- 16.1.7.2.1 Deals
- 16.1.7.2.2 Expansions
- 16.1.7.3 MnM view
- 16.1.8 MECHEL PAO
- 16.1.8.1 Business overview
- 16.1.8.2 Products/Solutions/Services offered
- 16.1.8.3 Recent developments
- 16.1.8.3.1 Expansions
- 16.1.8.4 MnM view
- 16.1.9 STEEL DYNAMICS INC.
- 16.1.9.1 Business overview
- 16.1.9.2 Products/Solutions/Services offered
- 16.1.9.3 Recent developments
- 16.1.9.3.1 Deals
- 16.1.9.4 MnM view
- 16.1.10 NLMK GROUP
- 16.1.10.1 Business overview
- 16.1.10.2 Products/Solutions/Services offered
- 16.1.10.3 Recent developments
- 16.1.10.3.1 Deals
- 16.1.10.3.2 Expansions
- 16.1.10.4 MnM view
- 16.1.11 JSW
- 16.1.11.1 Business overview
- 16.1.11.2 Products/Solutions/Services offered
- 16.1.11.3 Recent developments
- 16.1.11.3.1 Deals
- 16.1.11.3.2 Expansions
- 16.1.11.4 MnM view
- 16.1.12 BAOSTEEL GROUP CO., LTD
- 16.1.12.1 Business overview
- 16.1.12.2 Products/Solutions/Services offered
- 16.1.12.3 Recent developments
- 16.1.12.3.1 Deals
- 16.1.12.3.2 Expansions
- 16.1.12.4 MnM view
- 16.1.1 NIPPON STEEL CORPORATION
- 16.2 OTHER PLAYERS
- 16.2.1 METINVEST
- 16.2.2 PAO SEVERSTAL
- 16.2.3 BYER STEEL CORPORATION
- 16.2.4 DAIDO STEEL CO. LTD.
- 16.2.5 ACERINOX
- 16.2.6 HYUNDAI STEEL
- 16.2.7 JIANGSU SHAGANG GROUP CO., LTD
- 16.2.8 HBIS GROUP CO., LTD
- 16.2.9 EVRAZ PLC
- 16.2.10 SWISS STEEL GROUP
- 16.2.11 SUNFLAG IRON AND STEEL CO. LTD
- 16.2.12 OUTOKUMPU
- 16.2.13 7 STEEL UK
17 RESEARCH METHODOLOGY
- 17.1 RESEARCH DATA
- 17.1.1 SECONDARY DATA
- 17.1.1.1 Key data from secondary sources
- 17.1.2 PRIMARY DATA
- 17.1.2.1 Key data from primary sources
- 17.1.2.2 Key industry insights
- 17.1.1 SECONDARY DATA
- 17.2 MARKET SIZE ESTIMATION
- 17.3 BASE NUMBER CALCULATION
- 17.3.1 SUPPLY-SIDE APPROACH
- 17.4 MARKET FORECAST APPROACH
- 17.4.1 SUPPLY SIDE
- 17.4.2 DEMAND SIDE
- 17.5 DATA TRIANGULATION
- 17.6 FACTOR ANALYSIS
- 17.7 RESEARCH ASSUMPTIONS
- 17.8 RESEARCH LIMITATIONS AND RISK ASSESSMENT
18 APPENDIX
- 18.1 DISCUSSION GUIDE
- 18.2 KNOWLEDGE STORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 18.3 CUSTOMIZATION OPTIONS
- 18.4 RELATED REPORTS
- 18.5 AUTHOR DETAILS