
|
시장보고서
상품코드
2131876
성형 펄프 포장 시장 예측(-2031년) : 제품별, 성형 유형별, 원료별, 최종 용도 산업별, 지역별Molded Pulp Packaging Market by Molded Type (Transfer Molded, Thickwall, Thermoformed Fiber and Processed Pulp), Source (Wood Pulp and Non-Wood Pulp), Product (Trays, Clamshells), End-use Industry (Food), and by Region - Global Forecast To 2031 |
||||||

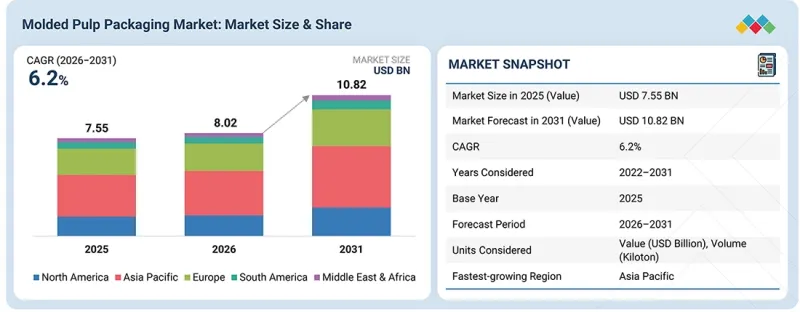
성형 펄프 포장 시장 규모는 2026년 80억 2,000만 달러에서 2031년까지 108억 2,000만 달러로 성장하며, 예측 기간 중 CAGR은 6.2%에 달할 것으로 전망되고 있습니다.
| 조사 범위 | |
|---|---|
| 조사 대상 기간 | 2022-2031년 |
| 기준연도 | 2025년 |
| 예측 기간 | 2026-2031년 |
| 산정 단위 | 금액(100만 달러) 킬로톤 |
| 부문 | 제품별, 성형 유형별, 원료별, 최종 용도 산업별, 지역별 |
| 대상 지역 | 북미, 아시아태평양, 유럽, 중동 및 아프리카, 남미 |
지속가능한 포장재 및 재활용 소재에 대한 수요가 증가함에 따라 성형 펄프 포장 시장은 확대될 전망입니다. 플라스틱 폐기물 감축에 대한 관심이 높아지고, 보다 지속가능한 환경에 대한 요구가 증가함에 따라 기업은 성형 펄프 제품을 도입하고 있습니다. 식품, 외식 산업, E-Commerce, 전자기기, 소비재 분야의 수요 확대에 따라 그 용도는 계속해서 넓어지고 있습니다.
"2026-2031년에 비목재 펄프 부문이 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
비목재 펄프 부문은 대체 및 재생 가능한 섬유 원료에 대한 수요가 증가함에 따라 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 기타 원료로는 사탕수수 찌꺼기, 대나무, 밀짚, 기타 농업 잔여물 등이 있습니다. 농업 폐기물 활용에 관한 개발이 진전되면서 목재계 섬유에 대한 의존도가 낮아지고 있는 점이 이 기술의 도입을 지원하고 있습니다. 또한 가공 기술의 발전으로 비목재 섬유를 더욱 다양한 성형 펄프 제품에 활용할 수 있게 되었습니다.
"2031년에는 트랜스퍼 성형 부문이 가장 큰 시장 점유율을 차지할 것으로 예측됩니다."
트랜스퍼 성형 부문은 균일하고 정밀하며 마감 처리가 뛰어난 포장 제품을 제조할 수 있으므로 2031년에는 최대 시장 점유율을 차지할 것으로 예상됩니다. 이 공정에서는 맞춤형 형상이나 디자인을 제작할 수 있을 뿐만 아니라, 강도와 구조적 완전성도 확보됩니다. 트레이, 보호용 인서트, 용기 및 기타 성형 섬유 제품 등 폭넓은 제품에 널리 활용될 수 있습니다.
"보울 부문은 2026-2031년에 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
그릇 부문은 플라스틱이나 스티로폼으로 만든 식품 서비스 제품을 대체할 지속가능한 대안에 대한 수요가 증가하고 있으며, 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 성형 펄프로 만든 그릇은 테이크아웃, 외식 산업, 인스턴트 식품 등의 용도로 사용할 수 있습니다. 편의 식품에 대한 수요와 재활용 가능한 포장재에 대한 수요가 증가함에 따라 추가적인 수요가 창출되고 있습니다. 현재 성형 펄프 그릇의 내습성 및 내유성이 향상됨에 따라 그 사용이 확대되고 있습니다.
"식품 포장 부문은 2026-2031년에 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다."
식품 제조업체, 소매업체, 외식 사업자 사이에서 지속가능한 식품 포장에 대한 수요가 높아짐에 따라 식품 포장 부문은 2026-2031년까지 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측됩니다. 성형 펄프는 트레이, 용기, 그릇,접시, 식품 보호용 포장 등 점점 더 많은 제품에 사용되고 있습니다. 이는 테이크아웃 및 배달, 포장 식품에 대한 수요 증가와 맞물려 진행되고 있습니다. 기존 플라스틱 포장을 대체하는 섬유계 포장의 사용 증가가 앞으로도 이 부문의 성장을 계속 견인할 것입니다.
"아시아태평양의 성형 펄프 포장 시장은 예측 기간 중 가장 높은 CAGR로 성장할 것으로 전망됩니다."
아시아태평양의 성형 펄프 포장 시장은 해당 지역의 산업화 진전, 도시화 가속화 및 주요 최종 용도 산업의 성장에 힘입어 예측 기간 중 가장 높은 연평균 성장률(CAGR)을 기록할 것으로 전망됩니다. 성형 펄프 포장은 식품 및 음료, 전자제품, E-Commerce, 외식 산업 및 소비재 시장의 성장에 따라 새로운 용도를 찾아가고 있습니다. 환경에 대한 관심 증가와 플라스틱 감축 노력이 기업의 섬유 기반 대체재 채택을 촉진하고 있습니다.
대상 기업 - 이 보고서에서는 Huhtamaki Oyj(핀란드), Hartmann Packaging A/S(덴마크), CKF Inc.(캐나다), Novolex(미국), Sabert Corporation(미국)을 비롯한 기업이 다루어지고 있습니다.
본 조사에서는 성형 펄프 포장 시장의 주요 기업에 대해 기업 개요, 최근 동향 및 주요 시장 전략을 포함한 상세한 경쟁 분석을 수록하고 있습니다.
조사 범위
본 조사 보고서에서는 성형 펄프 포장 시장을 원료(목재 펄프 및 비목재 펄프), 성형 유형(두꺼운 성형, 트랜스퍼 성형, 열성형 섬유, 가공 펄프), 제품(트레이, 클램쉘, 컵, 접시,그릇, 기타 제품), 최종 용도 분야(외식 산업용 포장, 식품 포장, 헬스케어, 전자제품, 기타 최종 용도 산업) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)에 따라 분류하고 있습니다. 이 보고서의 범위에는 성형 펄프 포장 시장의 성장에 영향을 미치는 촉진요인, 제약, 과제 및 기회에 대한 상세한 정보가 포함되어 있습니다. 주요 업계 참여 기업에 대한 심층 분석을 통해 사업 개요, 제공 제품, 그리고 성형 펄프 포장 시장과 관련된 제휴, 인수, 사업 확장 등 주요 전략에 대한 인사이트를 제공합니다. 또한 이 보고서는 성형 펄프 포장 시장 생태계에서 두각을 보이고 있는 스타트업 기업의 경쟁 동향에 대한 분석도 포괄하고 있습니다.
이 보고서를 구매해야 하는 이유
이 보고서는 시장 선도 기업 및 신규 진입 기업에게 성형 펄프 포장 시장 전체 및 각 하위 부문의 매출에 관한 가장 정확한 추정치를 제공합니다. 이 보고서는 이해관계자가 경쟁 구도를 이해하고, 자사의 사업 포지셔닝을 최적화하기 위한 추가적인 인사이트를 얻어 적절한 시장 진입 전략을 수립하는 데 도움이 됩니다. 또한 이 보고서는 이해관계자가 시장을 이해하는 데 도움을 주며, 주요 시장 촉진요인, 억제요인, 과제 및 기회에 대한 정보를 제공합니다.
이 보고서는 다음 사항에 대한 인사이트를 제공합니다. :
주요 촉진요인(일회용 플라스틱에 대한 규제 강화), 제약 요인(특정 용도에서의 높은 비용), 기회(고성능·스마트·맞춤형 성형 펄프 포장로의 확대) 및 과제(플라스틱과 동등한 성능 구현)에 대한 분석.
- 제품 개발/혁신: 성형 펄프 포장 시장의 향후 기술, 연구개발 활동, 제품 및 서비스 출시에 대한 상세 인사이트
- 시장 개발: 수익성이 높은 시장에 대한 포괄적인 정보-이 보고서는 다양한 지역에 걸친 성형 펄프 포장 시장을 분석합니다
시장 다각화: 성형 펄프 포장 시장의 신제품·서비스, 미개발 지역, 최근 동향 및 투자에 관한 포괄적인 정보
- 경쟁 분석: Huhtamaki Oyj(핀란드), Hartmann Packaging A/S(덴마크), CKF Inc.(캐나다), Novolex(미국), Sabert Corporation(미국) 등 주요 기업의 시장 점유율, 성장 전략 및 서비스 제공에 대한 상세한 평가.
목차
제1장 서론
제2장 개요
제3장 주요 인사이트
제4장 시장 개요
제5장 업계 동향
제6장 기술 진보, AI에 의한 영향, 특허, 혁신, 향후 응용
제7장 규제 상황과 지속가능성 구상
제8장 고객 상황과 구매 행동
제9장 성형 펄프 포장 시장(제품별)
제10장 성형 펄프 포장 시장(성형 유형별)
제11장 성형 펄프 포장 시장(원료별)
제12장 성형 펄프 포장 시장(최종 용도 산업별)
제13장 성형 펄프 포장 시장(지역별)
제14장 경쟁 구도
제15장 기업 개요
제16장 조사 방법
제17장 부록
KSAThe molded pulp packaging market is projected to grow from USD 8.02 billion in 2026 to USD 10.82 billion by 2031, at a CAGR of 6.2% during the forecast period.
| Scope of the Report | |
|---|---|
| Years Considered for the Study | 2022-2031 |
| Base Year | 2025 |
| Forecast Period | 2026-2031 |
| Units Considered | Value (USD Million) Volume (Kiloton) |
| Segments | Source, Molded Type, Product, End-use Industry, and Region |
| Regions covered | North America, Asia Pacific, Europe, the Middle East & Africa, and South America |
The molded pulp packaging market will expand as the demand for sustainable packaging and recycling materials is rising. The growing focus on reducing plastic waste and the need for a more sustainable environment are driving businesses to choose molded pulp options. Applications continue to expand with growing demand in food, foodservice, e-commerce, electronics, and consumer goods.
"The non-wood pulp segment is projected to exhibit the highest CAGR from 2026 to 2031."
The non-wood pulp segment is projected to exhibit the highest CAGR during the forecast period due to rising demand for alternative and renewable fiber sources. Other raw material options include materials like bagasse, bamboo, wheat straw, and other agricultural residues. The increasing development of agricultural waste utilization and decreasing reliance on wood-based fibers is an aid to adoption. Advances in processing technology are also allowing the use of non-wood fibers for a wider variety of molded pulp products.
"The transfer molded segment is projected to capture the largest market share in 2031."
The transfer molded segment is expected to get the highest market share in 2031 because of its ability to manufacture uniform, accurate, and well-finished packaging products. The process can be used to create a custom shape or design, and also ensures that the strength and structural integrity are preserved. It can be widely used in a variety of products like trays, protective inserts, containers, and other molded fiber formats.
"The bowls segment is projected to exhibit the highest CAGR from 2026 to 2031"
The bowls segment is projected to exhibit the highest CAGR during the forecast period due to the rising demand for sustainable alternatives to plastic and foam foodservice products. Molded pulp bowls can be used in takeout, food service, ready-to-eat meal applications, and more. The demand for convenience foods and the increased demand for recyclable packaging are generating additional demand. Now, the use of molded pulp bowls is growing by improving their moisture and grease resistance.
"The food packaging segment is projected to exhibit the highest CAGR from 2026 to 2031."
The food packaging segment is projected to exhibit the highest CAGR from 2026 to 2031, as demand for sustainable food packaging rises among food manufacturers, retailers, and foodservice operators. Molded pulp is being used in more and more trays, containers, bowls, plates, and food protection packaging. This is alongside rising demand for takeout and delivery, and packaged food. The increase in the use of fiber-based packaging as an alternative to conventional plastic packaging will continue to drive growth in the segment.
"The molded pulp packaging market in Asia Pacific is projected to grow at the highest CAGR during the forecast period."
Asia Pacific molded pulp packaging market is expected to have the highest CAGR growth over the forecast period, driven by the growing rate of industrialization, rate of urbanization, and growth of key end-use industries in the region. Molded pulp packaging is finding new applications due to the growth of the food & beverage, electronics, e-commerce, foodservice, and consumer goods markets. Growing concern for the environment and plastics reduction efforts have spurred companies to use fiber-based alternatives.
By Company Type: Tier 1 - 40%, Tier 2 - 30%, and Tier 3- 30%
By Designation: Directors - 30%, Managers - 20%, and Others - 50%
By Region: North America - 20%, Europe - 10%, Asia Pacific - 40%, South America - 10%, and Middle East & Africa - 20%
Companies Covered: Huhtamaki Oyj (Finland), Hartmann Packaging A/S (Denmark), CKF Inc. (Canada), Novolex (US), Sabert Corporation (US), among other companies, are covered in the report.
The study includes an in-depth competitive analysis of these key players in the molded pulp packaging market, with their company profiles, recent developments, and key market strategies.
Research Coverage
This research report categorizes the molded pulp packaging market based on source (wood pulp, and non-wood pulp), molded type (thick wall, transfer molded, thermoformed fiber, and processed pulp), product (trays, clamshells, cups, plates, bowls, and other products), end-use sector (foodservice packaging, food packaging, healthcare, electronics, and other end-use industries), and region (Asia Pacific, North America, Europe, South America, and the Middle East & Africa). The report's scope covers detailed information regarding the drivers, restraints, challenges, and opportunities influencing the growth of the molded pulp packaging market. A detailed analysis of the key industry players has been done to provide insights into their business overview, products offered, and key strategies, such as partnerships, acquisitions, and expansions, associated with the molded pulp packaging market. This report covers a competitive analysis of upcoming startups in the molded pulp packaging market ecosystem.
Reasons to Buy the Report
The report will offer market leaders/new entrants with information on the closest approximations of the revenue numbers for the overall molded pulp packaging market and the subsegments. This report will help stakeholders understand the competitive landscape, gain more insights into positioning their businesses better, and plan suitable go-to-market strategies. The report will help stakeholders understand the market and provide them with information on key market drivers, restraints, challenges, and opportunities.
The report provides insights into the following points:
Analysis of key drivers (Increasing restrictions on single-use plastics), restraints ( Higher cost in certain applications), opportunities ( Expansion into high-performance, smart, and customized molded fiber packaging ), and challenges ( Achieving performance comparable to plastic).
- Product Development/Innovation: Detailed insights into upcoming technologies, research & development activities, and product & service launches in the molded pulp packaging market
- Market Development: Comprehensive information about profitable markets-the report analyzes the molded pulp packaging market across varied regions
Market Diversification: Exhaustive information about new products & services, untapped geographies, recent developments, and investments in the molded pulp packaging market
- Competitive Assessment: In-depth assessment of market shares, growth strategies, and service offerings of leading players, such as Huhtamaki Oyj (Finland), Hartmann Packaging A/S (Denmark), CKF Inc. (Canada), Novolex (US), Sabert Corporation (US), and others.
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 STUDY OBJECTIVES
- 1.2 MARKET DEFINITION
- 1.3 MARKET SCOPE
- 1.3.1 MARKET SEGMENTATION AND REGIONAL SCOPE
- 1.3.2 INCLUSIONS AND EXCLUSIONS
- 1.3.3 YEARS CONSIDERED
- 1.3.4 CURRENCY CONSIDERED
- 1.3.5 UNIT CONSIDERED
- 1.3.6 STAKEHOLDERS
- 1.4 SUMMARY OF CHANGES
2 EXECUTIVE SUMMARY
- 2.1 MARKET HIGHLIGHTS AND KEY INSIGHTS
- 2.2 KEY MARKET PARTICIPANTS: MAPPING OF STRATEGIC DEVELOPMENTS
- 2.3 DISRUPTIVE TRENDS IN MOLDED PULP PACKAGING MARKET
- 2.4 HIGH-GROWTH SEGMENTS
- 2.5 REGIONAL SNAPSHOT: MARKET SIZE, GROWTH RATE, AND FORECAST
3 PREMIUM INSIGHTS
- 3.1 ATTRACTIVE OPPORTUNITIES FOR PLAYERS IN MOLDED PULP PACKAGING MARKET
- 3.2 MOLDED PULP PACKAGING MARKET, BY SOURCE AND REGION
- 3.3 MOLDED PULP PACKAGING MARKET SHARE, BY MOLDED TYPE
- 3.4 MOLDED PULP PACKAGING MARKET, BY PRODUCT
- 3.5 MOLDED PULP PACKAGING MARKET SHARE, BY END-USE INDUSTRY
- 3.6 MOLDED PULP PACKAGING MARKET, BY COUNTRY
4 MARKET OVERVIEW
- 4.1 INTRODUCTION
- 4.2 MARKET DYNAMICS
- 4.2.1 DRIVERS
- 4.2.1.1 Expansion of egg production
- 4.2.1.2 Growing e-commerce industry
- 4.2.1.3 Increasing restrictions on single-use plastics
- 4.2.1.4 Expansion of foodservice and food delivery
- 4.2.2 RESTRAINTS
- 4.2.2.1 Higher cost in certain applications
- 4.2.2.2 Raw-material availability and quality variations
- 4.2.3 OPPORTUNITIES
- 4.2.3.1 Growing wine and beer consumption
- 4.2.3.2 Growth in emerging markets
- 4.2.3.3 Expansion into high-performance, smart, and customized molded fiber packaging
- 4.2.3.4 Growing demand for sustainable and PFAS-free molded fiber packaging
- 4.2.4 CHALLENGES
- 4.2.4.1 Achieving performance comparable to plastic
- 4.2.4.2 Scaling production to meet large customer requirements
- 4.2.1 DRIVERS
- 4.3 UNMET NEEDS AND WHITE SPACES
- 4.3.1 UNMET NEEDS IN MOLDED PULP PACKAGING MARKET
- 4.3.1.1 Growing need for high-performance molded pulp packaging
- 4.3.1.2 Need for cost-effective sustainable materials and scalable manufacturing
- 4.3.1.3 Increasing need for advanced customization and premium aesthetics
- 4.3.1.4 Need for compatibility with existing packaging infrastructure
- 4.3.2 WHITE SPACE OPPORTUNITIES
- 4.3.2.1 Expansion into high-growth emerging economies
- 4.3.2.2 Growth opportunities in sustainable and plastic-replacement packaging
- 4.3.2.3 Rising demand for premium and customized molded fiber packaging
- 4.3.2.4 Development of agricultural-fiber-based molded pulp packaging
- 4.3.1 UNMET NEEDS IN MOLDED PULP PACKAGING MARKET
- 4.4 INTERCONNECTED MARKETS AND CROSS-SECTOR OPPORTUNITIES
- 4.4.1 INTERCONNECTED MARKETS
- 4.4.2 CROSS-SECTOR OPPORTUNITIES
- 4.5 STRATEGIC MOVES BY TIER 1/2/3 PLAYERS
- 4.5.1 TIER 1 PLAYERS: GLOBAL LEADERS DRIVING EXPANSION AND MOLDED PULP INNOVATION
- 4.5.1.1 Novolex completes combination with pactiv evergreen to strengthen packaging portfolio
- 4.5.1.2 Huhtamaki acquires zellwin farms to expand molded fiber packaging capacity
- 4.5.1.3 Hartmann expands north american molded fiber production capacity
- 4.5.1 TIER 1 PLAYERS: GLOBAL LEADERS DRIVING EXPANSION AND MOLDED PULP INNOVATION
5 INDUSTRY TRENDS
- 5.1 PORTER'S FIVE FORCES ANALYSIS
- 5.1.1 THREAT OF NEW ENTRANTS
- 5.1.2 THREAT OF SUBSTITUTES
- 5.1.3 BARGAINING POWER OF SUPPLIERS
- 5.1.4 BARGAINING POWER OF BUYERS
- 5.1.5 INTENSITY OF COMPETITIVE RIVALRY
- 5.2 MACROECONOMIC OUTLOOK
- 5.2.1 INTRODUCTION
- 5.2.2 GDP TRENDS AND FORECASTS
- 5.3 VALUE CHAIN ANALYSIS
- 5.4 ECOSYSTEM ANALYSIS
- 5.5 PRICING ANALYSIS
- 5.5.1 PRICING ANALYSIS, BY PRODUCT
- 5.5.2 PRICING ANALYSIS, BY REGION
- 5.6 TRADE ANALYSIS
- 5.6.1 EXPORT SCENARIO (HS CODE 482370)
- 5.6.2 IMPORT SCENARIO (HS CODE 482370)
- 5.7 KEY CONFERENCES AND EVENTS, 2026-2027
- 5.8 TRENDS/DISRUPTIONS IMPACTING CUSTOMER BUSINESS
- 5.9 INVESTMENT AND FUNDING SCENARIO
- 5.10 CASE STUDY ANALYSIS
- 5.10.1 KOHLER: IMPROVING SUPPLY CHAIN RELIABILITY THROUGH MOLDED FIBER PACKAGING
- 5.10.2 CRAFT ALLEY: DEVELOPING PLASTIC-FREE MOLDED FIBER PACKAGING FOR BEER SHIPPING
- 5.10.3 BOCA SYSTEMS: REPLACING FOAM WITH CUSTOM MOLDED FIBER PACKAGING
- 5.11 IMPACT OF US TARIFFS - MOLDED PULP PACKAGING MARKET
- 5.11.1 INTRODUCTION
- 5.11.2 KEY TARIFF RATES
- 5.11.3 PRICE IMPACT ANALYSIS
- 5.11.4 IMPACT ON COUNTRY/REGION
- 5.11.4.1 US
- 5.11.4.2 Asia Pacific
- 5.11.4.3 Europe
- 5.11.5 IMPACT ON END USE
- 5.11.5.1 Food Packaging
- 5.11.5.2 Foodservice Disposables
- 5.11.5.3 Healthcare
6 TECHNOLOGICAL ADVANCEMENTS, AI-DRIVEN IMPACT, PATENTS, INNOVATIONS, AND FUTURE APPLICATIONS
- 6.1 KEY EMERGING TECHNOLOGIES
- 6.1.1 DRY MOLDED FIBER TECHNOLOGY
- 6.1.2 ADVANCED 3D MOLDED FIBER TECHNOLOGY
- 6.1.3 HOLLOW MOLDED FIBER TECHNOLOGY
- 6.2 COMPLEMENTARY TECHNOLOGIES
- 6.2.1 AUTOMATION, ROBOTICS, AND MACHINE VISION
- 6.2.2 PRECISION MOLDING AND TOOLING TECHNOLOGY
- 6.2.3 ADVANCED DEWATERING AND DRYING TECHNOLOGY
- 6.3 ADJACENT TECHNOLOGIES
- 6.3.1 PAPER-BASED THERMOFORMING
- 6.3.2 BIOPOLYMER AND COMPOSTABLE PACKAGING
- 6.4 TECHNOLOGY/PRODUCT ROADMAP
- 6.4.1 SHORT-TERM (2025-2027) | FOUNDATION & EARLY COMMERCIALIZATION
- 6.4.2 MID-TERM (2027-2030) | EXPANSION & INTEGRATION
- 6.4.3 LONG-TERM (2030-2035+) | MATURITY, CIRCULARITY & ADVANCED MOLDED PULP PACKAGING
- 6.5 PATENT ANALYSIS
- 6.5.1 INTRODUCTION
- 6.5.2 METHODOLOGY
- 6.5.3 PATENT ANALYSIS, 2016-2025
- 6.6 FUTURE APPLICATIONS
- 6.6.1 INTEGRATION OF MOLDED PULP PACKAGING IN ADVANCED AND HIGH-PERFORMANCE APPLICATIONS
- 6.7 IMPACT OF AI/GEN AI ON MOLDED PULP PACKAGING MARKET
- 6.7.1 TOP USE CASES AND MARKET POTENTIAL
- 6.7.2 BEST PRACTICES IN MOLDED PULP PACKAGING
- 6.7.3 INTERCONNECTED ECOSYSTEM AND IMPACT ON MARKET PLAYERS
- 6.7.4 CLIENTS' READINESS TO ADOPT GENERATIVE AI IN THE MOLDED PULP PACKAGING MARKET
- 6.8 SUCCESS STORIES AND REAL-WORLD APPLICATIONS
- 6.8.1 FIBERCEL MOLDED PULP PACKAGING PROVIDES PROTECTIVE SOLUTIONS FOR INDUSTRIAL AND ELECTRONIC PRODUCTS
- 6.8.2 ENVIROPAK MOLDED FIBER PACKAGING PROVIDES CUSTOMIZED PROTECTION FOR THERMAL PRINTERS
- 6.8.3 JAMES CROPPER DEVELOPS SUSTAINABLE MOULDED FIBRE PACKAGING FOR LUXURY CHAMPAGNE
7 REGULATORY LANDSCAPE AND SUSTAINABILITY INITIATIVES
- 7.1 REGIONAL REGULATIONS AND COMPLIANCE
- 7.1.1 REGULATORY BODIES, GOVERNMENT AGENCIES, AND OTHER ORGANIZATIONS
- 7.1.2 INDUSTRY STANDARDS
- 7.2 SUSTAINABILITY INITIATIVES
- 7.2.1 CARBON IMPACT AND ECO-APPLICATIONS OF MOLDED PULP PACKAGING
- 7.2.1.1 Carbon impact reduction
- 7.2.1.2 Food applications
- 7.2.1.3 Eco-applications
- 7.2.1 CARBON IMPACT AND ECO-APPLICATIONS OF MOLDED PULP PACKAGING
- 7.3 SUSTAINABILITY IMPACT AND REGULATORY POLICY INITIATIVES
- 7.4 CERTIFICATIONS, LABELING, & ECO-STANDARDS
8 CUSTOMER LANDSCAPE & BUYER BEHAVIOR
- 8.1 DECISION-MAKING PROCESS
- 8.2 KEY STAKEHOLDERS INVOLVED IN BUYING PROCESS AND THEIR EVALUATION CRITERIA
- 8.2.1 KEY STAKEHOLDERS IN BUYING PROCESS
- 8.2.2 BUYING CRITERIA
- 8.3 ADOPTION BARRIERS & INTERNAL CHALLENGES
- 8.4 UNMET NEEDS OF VARIOUS END-USE INDUSTRIES
- 8.5 MARKET PROFITABILITY
- 8.6 MARGIN OPPORTUNITIES, BY END-USE INDUSTRY
9 MOLDED PULP PACKAGING MARKET, BY PRODUCT
- 9.1 INTRODUCTION
- 9.2 TRAYS
- 9.2.1 RISING DEMAND FOR EGG, FOOD, AND FRESH PRODUCE PACKAGING TO DRIVE MARKET
- 9.3 CLAMSHELLS
- 9.3.1 EXPANSION OF TAKEAWAY FOOD AND FOODSERVICE TO PROPEL MARKET
- 9.4 CUPS
- 9.4.1 GROWTH OF QUICK-SERVICE RESTAURANTS, CAFES, AND READY-TO-EAT PRODUCTS TO FUEL GROWTH
- 9.5 PLATES
- 9.5.1 GROWING INSTITUTIONAL FOODSERVICE AND READY-TO-EAT MEALS TO BOOST MARKET
- 9.6 BOWLS
- 9.6.1 GROWING CONSUMPTION OF LIQUID AND SEMI-LIQUID READY-TO-EAT FOODS TO BOOST MARKET
- 9.7 OTHER PRODUCTS
10 MOLDED PULP PACKAGING MARKET, BY MOLDED TYPE
- 10.1 INTRODUCTION
- 10.2 TRANSFER MOLDED
- 10.2.1 INCREASING ADOPTION IN ELECTRONICS AND HEALTHCARE APPLICATIONS TO DRIVE MARKET
- 10.3 THERMOFORMED FIBER
- 10.3.1 EXPANSION INTO ELECTRONICS, COSMETICS, FOODSERVICE, AND PREMIUM APPLICATIONS TO DRIVE MARKET
- 10.4 THICK WALL
- 10.4.1 INCREASING DEMAND FOR SUSTAINABLE AND COST-EFFECTIVE INDUSTRIAL PROTECTION TO DRIVE MARKET
- 10.5 PROCESSED PULP
- 10.5.1 GROWING DEMAND FOR CUSTOMIZED AND VALUE-ADDED PACKAGING TO DRIVE MARKET
11 MOLDED PULP PACKAGING MARKET, BY SOURCE
- 11.1 INTRODUCTION
- 11.2 WOOD PULP
- 11.2.1 BROAD APPLICATIONS ACROSS END-USE INDUSTRIES TO DRIVE MARKET
- 11.3 NON-WOOD PULP
- 11.3.1 GROWING AVAILABILITY OF AGRICULTURAL AND RENEWABLE FIBER SOURCES TO DRIVE MARKET
12 MOLDED PULP PACKAGING MARKET, BY END-USE INDUSTRY
- 12.1 INTRODUCTION
- 12.2 FOOD PACKAGING
- 12.2.1 EXPANSION OF FRESH PRODUCE AND POULTRY SUPPLY CHAINS TO DRIVE MARKET
- 12.3 FOODSERVICE PACKAGING
- 12.3.1 RISING CONSUMER SPENDING AND CHANGING CONSUMER LIFESTYLES TO PROPEL MARKET
- 12.4 HEALTHCARE
- 12.4.1 GROWING BURDEN OF CHRONIC DISEASES AND AGING POPULATION TO FUEL GROWTH
- 12.5 ELECTRONICS
- 12.5.1 GROWING ELECTRONICS PRODUCTION TO BOOST MARKET
- 12.6 OTHER END-USE INDUSTRIES
13 MOLDED PULP PACKAGING MARKET, BY REGION
- 13.1 INTRODUCTION
- 13.2 ASIA PACIFIC
- 13.2.1 CHINA
- 13.2.1.1 Rapid growth of e-commerce and consumer goods to propel market
- 13.2.2 JAPAN
- 13.2.2.1 Growth of e-commerce and consumer goods distribution to drive market
- 13.2.3 INDIA
- 13.2.3.1 Strong egg production and poultry industry to boost market
- 13.2.4 AUSTRALIA
- 13.2.4.1 Expansion of healthcare and increasing medical device demand to drive market
- 13.2.5 REST OF ASIA PACIFIC
- 13.2.1 CHINA
- 13.3 EUROPE
- 13.3.1 GERMANY
- 13.3.1.1 Expansion of foodservice and food retail to propel market
- 13.3.2 FRANCE
- 13.3.2.1 Rapid growth of e-commerce to drive demand
- 13.3.3 UK
- 13.3.3.1 Expansion of automotive and electric vehicles to fuel market growth
- 13.3.4 ITALY
- 13.3.4.1 Expansion of food retail, foodservice, and tourism to augment market growth
- 13.3.5 SPAIN
- 13.3.5.1 Strong automotive manufacturing and electrification to augment demand
- 13.3.6 REST OF EUROPE
- 13.3.1 GERMANY
- 13.4 NORTH AMERICA
- 13.4.1 US
- 13.4.1.1 Growth of e-commerce and consumer goods distribution to propel market
- 13.4.2 CANADA
- 13.4.2.1 Growth of egg production and consumption to drive market
- 13.4.3 MEXICO
- 13.4.3.1 Expansion of food retail and foodservice to support market growth
- 13.4.1 US
- 13.5 SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.5.1.1 Growth of healthcare and medical products to propel market
- 13.5.2 ARGENTINA
- 13.5.2.1 Expansion of e-commerce and logistics to drive market
- 13.5.3 REST OF SOUTH AMERICA
- 13.5.1 BRAZIL
- 13.6 MIDDLE EAST & AFRICA
- 13.6.1 GCC COUNTRIES
- 13.6.1.1 Saudi Arabia
- 13.6.1.1.1 Expansion of food retail and food service to fuel market growth
- 13.6.1.2 UAE
- 13.6.1.2.1 Rapid growth of food, e-commerce, and grocery delivery to drive market growth
- 13.6.1.3 Rest of GCC countries
- 13.6.1.1 Saudi Arabia
- 13.6.2 SOUTH AFRICA
- 13.6.2.1 Strong and consolidated retail distribution to boost market growth
- 13.6.3 REST OF MIDDLE EAST & AFRICA
- 13.6.1 GCC COUNTRIES
14 COMPETITIVE LANDSCAPE
- 14.1 OVERVIEW
- 14.2 KEY PLAYERS' STRATEGIES/RIGHT TO WIN, JANUARY 2021-JULY 2026
- 14.3 REVENUE ANALYSIS, 2021-2025
- 14.4 MARKET SHARE ANALYSIS, 2025
- 14.5 COMPANY VALUATION AND FINANCIAL METRICS
- 14.6 BRAND/PRODUCT COMPARISON
- 14.7 COMPANY EVALUATION MATRIX: KEY PLAYERS, 2025
- 14.7.1 STARS
- 14.7.2 EMERGING LEADERS
- 14.7.3 PERVASIVE PLAYERS
- 14.7.4 PARTICIPANTS
- 14.7.5 COMPANY FOOTPRINT: KEY PLAYERS, 2025
- 14.7.5.1 Company footprint
- 14.7.5.2 Region footprint
- 14.7.5.3 Molded type footprint
- 14.7.5.4 Source footprint
- 14.7.5.5 Product footprint
- 14.7.5.6 End-use industry footprint
- 14.8 COMPANY EVALUATION MATRIX: STARTUPS/SMES, 2025
- 14.8.1 PROGRESSIVE COMPANIES
- 14.8.2 RESPONSIVE COMPANIES
- 14.8.3 DYNAMIC COMPANIES
- 14.8.4 STARTING BLOCKS
- 14.8.5 COMPETITIVE BENCHMARKING: STARTUPS/SMES, 2025
- 14.8.5.1 Detailed list of key startups/SMEs
- 14.8.6 COMPETITIVE BENCHMARKING OF KEY STARTUPS/SMES
- 14.9 COMPETITIVE SCENARIO
- 14.9.1 PRODUCT LAUNCHES
- 14.9.2 DEALS
- 14.9.3 EXPANSIONS
- 14.9.4 OTHER DEVELOPMENTS
15 COMPANY PROFILES
- 15.1 KEY PLAYERS
- 15.1.1 HUHTAMAKI OYJ
- 15.1.1.1 Business overview
- 15.1.1.2 Products/Solutions/Services offered
- 15.1.1.3 Recent developments
- 15.1.1.3.1 Product launches
- 15.1.1.3.2 Deals
- 15.1.1.3.3 Expansions
- 15.1.1.4 MnM view
- 15.1.1.4.1 Key strengths
- 15.1.1.4.2 Strategic choices
- 15.1.1.4.3 Weaknesses and competitive threats
- 15.1.2 HARTMANN PACKAGING A/S
- 15.1.2.1 Business overview
- 15.1.2.2 Products/Solutions/Services offered
- 15.1.2.3 Recent developments
- 15.1.2.3.1 Product launches
- 15.1.2.3.2 Deals
- 15.1.2.3.3 Expansions
- 15.1.2.3.4 Other developments
- 15.1.2.4 MnM view
- 15.1.2.4.1 Key strengths
- 15.1.2.4.2 Strategic choices
- 15.1.2.4.3 Weaknesses and competitive threats
- 15.1.3 CKF INC.
- 15.1.3.1 Business overview
- 15.1.3.2 Products/Solutions/Services offered
- 15.1.3.3 Recent developments
- 15.1.3.3.1 Deals
- 15.1.3.3.2 Expansions
- 15.1.3.4 MnM view
- 15.1.3.4.1 Key strengths
- 15.1.3.4.2 Strategic choices
- 15.1.3.4.3 Weaknesses and competitive threats
- 15.1.4 NOVOLEX
- 15.1.4.1 Business overview
- 15.1.4.2 Products/Solutions/Services offered
- 15.1.4.3 Recent developments
- 15.1.4.3.1 Product launches
- 15.1.4.3.2 Deals
- 15.1.4.4 MnM view
- 15.1.4.4.1 Key strengths
- 15.1.4.4.2 Strategic choices
- 15.1.4.4.3 Weaknesses and competitive threats
- 15.1.5 SABERT CORPORATION
- 15.1.5.1 Business overview
- 15.1.5.2 Products/Solutions/Services offered
- 15.1.5.3 Recent developments
- 15.1.5.3.1 Product launches
- 15.1.5.3.2 Expansions
- 15.1.5.3.3 Other developments
- 15.1.5.4 MnM view
- 15.1.5.4.1 Key strengths
- 15.1.5.4.2 Strategic choices
- 15.1.5.4.3 Weaknesses and competitive threats
- 15.1.6 OMNI-PAC GROUP
- 15.1.6.1 Business overview
- 15.1.6.2 Products/Solutions/Services offered
- 15.1.6.3 MnM view
- 15.1.6.3.1 Key strengths
- 15.1.7 CULLEN SUSTAINABLE PACKAGING
- 15.1.7.1 Business overview
- 15.1.7.2 Products/Solutions/Services offered
- 15.1.7.3 Recent developments
- 15.1.7.3.1 Product launches
- 15.1.7.3.2 Expansions
- 15.1.7.4 MnM view
- 15.1.8 JAMES CROPPER PLC
- 15.1.8.1 Business overview
- 15.1.8.2 Products/Solutions/Services offered
- 15.1.8.3 Recent developments
- 15.1.8.3.1 Product launches
- 15.1.8.3.2 Deals
- 15.1.8.4 MnM view
- 15.1.9 GENPAK
- 15.1.9.1 Business overview
- 15.1.9.2 Products/Solutions/Services offered
- 15.1.9.3 MnM view
- 15.1.10 PAPACKS SALES GMBH
- 15.1.10.1 Business overview
- 15.1.10.2 Products/Solutions/Services offered
- 15.1.10.3 Recent developments
- 15.1.10.4 MnM view
- 15.1.1 HUHTAMAKI OYJ
- 15.2 OTHER PLAYERS
- 15.2.1 KEIDING, INC.
- 15.2.2 HENRY MOLDED PRODUCTS INC.
- 15.2.3 ENVIROPAK
- 15.2.4 SPECIALIZED PACKAGING GROUP
- 15.2.5 UNIFIED2 GLOBAL PACKAGING GROUP
- 15.2.6 TEKNI-PLEX, INC.
- 15.2.7 ORCON INDUSTRIES CORP.
- 15.2.8 RYPAX
- 15.2.9 GREENINDIA BIODEGRADABLE PACKAGING
- 15.2.10 BONITOPAK
- 15.2.11 GREEN VALLEY PACKAGING
- 15.2.12 DART CONTAINER CORPORATION
- 15.2.13 PULP MOLDED PRODUCTS
- 15.2.14 MASPACK LIMITED
- 15.2.15 PRIMAPACK
16 RESEARCH METHODOLOGY
- 16.1 RESEARCH DATA
- 16.1.1 SECONDARY DATA
- 16.1.1.1 Key data from secondary sources
- 16.1.2 PRIMARY DATA
- 16.1.2.1 Key data from primary sources
- 16.1.2.2 Key industry insights
- 16.1.1 SECONDARY DATA
- 16.2 MARKET SIZE ESTIMATION
- 16.3 BASE NUMBER CALCULATION
- 16.3.1 APPROACH
- 16.4 MARKET FORECAST APPROACH
- 16.4.1 SUPPLY SIDE
- 16.4.2 DEMAND SIDE
- 16.5 DATA TRIANGULATION
- 16.6 FACTOR ANALYSIS
- 16.7 RESEARCH ASSUMPTIONS
- 16.8 RESEARCH LIMITATIONS AND RISK ASSESSMENT
17 APPENDIX
- 17.1 DISCUSSION GUIDE
- 17.2 CUSTOMIZATION OPTIONS
- 17.3 RELATED REPORTS
- 17.4 KNOWLEDGESTORE: MARKETSANDMARKETS' SUBSCRIPTION PORTAL
- 17.5 AUTHOR DETAILS


