|
시장보고서
상품코드
2061667
배합 첨가제 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Formulation Additive - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
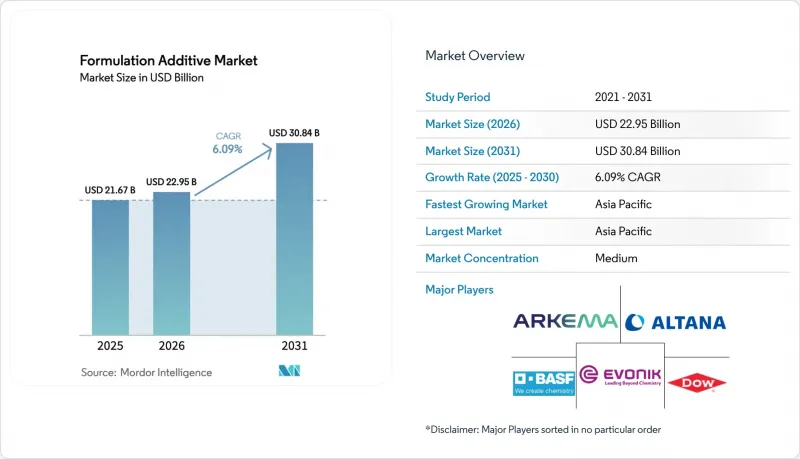
에 의하면, 배합 첨가제 시장 규모는 2025년 216억 7,000만 달러로 평가되었습니다. 2026년 229억 5,000만 달러에서 2031년까지 308억 4,000만 달러로 확대되어 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 6.09%를 나타낼 것으로 예측됩니다.
본 보고서는 첨가제의 유형(소포제, 유변학 조절제 등), 최종 이용 산업(건설, 운송, 자동차, 석유 및 가스 등), 배합 기술(수성 시스템, 용제성 시스템 등), 그리고 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계의 배합 첨가제 시장 동향과 인사이트
지속가능성을 배경으로 한 저VOC 수성 도료로의 전환
2020년 이후 수성 도료는 급증하여 전 세계 건축용 도료 시장에서 큰 비중을 차지하게 되었습니다. 이러한 변화는 유럽연합(EU) 및 캘리포니아주 당국이 시행한 VOC(휘발성 유기 화합물) 규제 강화와 일치합니다. 이러한 변화에 따라 주요 제조업체들은 기존의 글리콜 에테르에서 바이오 무코어 향료로 전환을 추진하고 있으며, 연관 증점제의 사용도 증가하고 있습니다. 유기 용매를 사용하지 않고 점도를 유지하는 이러한 증점제 덕분에, 용제계 도료에 비해 제조 단계까지의 배출량이 현저히 감소했습니다. BASF는 알키드 수지의 흘러내림 방지 특성을 재현하는 유변학 조절제를 도입하여, 이를 통해 설계자는 높은 시공 품질을 유지하면서 LEED v4.1 크레딧을 획득할 수 있게 되었습니다. 한편, 벤자민 무어의 ‘Gennex’와 같이 VOC가 전혀 없는 착색제를 채택한 플랫폼은 안료 수요를 줄이고 있으며, 그 결과 원자재 비용을 현저히 절감하고 있습니다. 또한, 미국과 유럽 모두에서 제3자의 환경 인증을 받은 제품을 우선적으로 선정하는 공공 부문의 조달 추세가 뚜렷하게 나타나고 있으며, 이는 인프라 프로젝트의 변화를 가속화하고 있습니다.
신흥국에서의 인프라 지출 확대
인도는 ‘국가 화학물질 정책’에 따라 2030년까지 국내 화학제품 생산을 대폭 확대하는 것을 목표로 하고 있습니다. 이 정책은 선정된 12개 투자 구역에서 외국인 투자자에게 10년에 걸친 매력적인 면세 혜택을 제공합니다. 한편, 인도네시아에서는 ‘누산타라’ 수도 프로젝트가 새로운 기준을 제시하고 있습니다. 이 프로젝트에서는 모든 정부 청사에 저VOC 도료의 사용이 의무화되어 있어, 이에 따라 수성 분산제 및 소포제 수요가 증가하고 있습니다. 사우디아라비아 공공투자기금(PIF)은 하류 첨가제 제조 공장에 대응하는 에틸렌 크래커를 갖춘 NEOM 산업 단지에 대규모 투자를 진행하고 있습니다. 이러한 전략적 조치로 인해 현지 배합 제조업체의 물류 비용이 절감될 것으로 기대됩니다. 베트남에서는 최근 건설법 개정으로 초고층 빌딩 프로젝트에 대한 VOC 검사가 의무화됨에 따라, 2028년까지 규정을 준수하는 첨가제 시장의 수익성이 높아질 것으로 전망됩니다. 2024년, 주요 다자간 금융기관들은 동남아시아의 인프라 확충을 위해 막대한 자금을 지원했으나, 특히 그린 빌딩 협정에 중점을 두고 있어 수성 및 UV 경화형 솔루션이 선호되는 경향이 두드러지고 있습니다.
엄격한 REACH 및 TSCA 재등록 비용
2025년, 유럽화학물질청(ECHA)은 후보 목록에 8가지 물질을 추가했습니다. 제조업체는 필수 유전독성 시험을 제외하고, 대량 생산되는 물질의 등록 서류 작성에 막대한 비용을 부담하고 있습니다. 미국에서는 환경보호청(EPA)이 제조업체에 수천 가지 화학 물질에 대한 노출 데이터를 4년마다 보고하도록 의무화하고 있으며, 이를 위반할 경우 막대한 벌금이 부과됩니다. 에보닉은 향후 라이선스 비용을 반영한 내부 모델에 따른 시뮬레이션 결과 순현재가치가 마이너스가 될 것으로 예측됨에 따라, 일부 계면활성제 SKU의 판매를 중단했습니다. 중견 기업, 특히 제품 라인 포트폴리오가 일정 기준에 미치지 못하는 기업은 이러한 규정 준수 비용의 부담을 지나치게 많이 지고 있습니다.
부문별 분석
2025년에는 분산제가 매출의 33.71%를 차지하며, 수성, 용제계, UV계를 포함한 다양한 시스템에서 안료와 충전제를 안정화하는 데 있어 매우 중요한 역할을 하고 있음이 부각되었습니다. BASF의 DISPERBYK-2150은 폴리우레탄 골격을 활용함으로써 TiO2의 사용량을 줄여, 도료 배합의 비용 효율성을 높이는 데 기여했습니다.
유변학 조절제는 전단 희석 특성을 지닌 3D 프린팅용 모르타르와 흘러내림 방지 기능을 갖춘 수직면용 도료에 대한 수요에 힘입어, 2026년부터 2031년까지의 예측 기간 동안 연평균 성장률(CAGR) 6.61%를 나타낼 것으로 전망됩니다. 현재는 열대 지역에서도 점도 드리프트에 견딜 수 있는 능력을 갖춘 복합형 증점제를 통해, 배합 첨가제 시장의 적용 범위가 온대 지역을 넘어 확대되고 있습니다. 소포제는 상당한 시장 점유율을 차지하고 있습니다. 에보닉이 출시한 실리콘 프리 제품은 EU 에코라벨 기준을 충족할 뿐만 아니라, 그동안 새틴 마감의 과제로 지적되던 크레이터 형성 문제도 해결했습니다. 계면활성제 기반의 습윤제는 전자 분야의 엄격한 이온 오염 기준을 충족하는 한편, 커플링제, 접착 촉진제 및 UV 안정제의 조합은 특수한 틈새 시장에서 뚜렷한 기여를 했습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 42.23%를 차지했으며, 2026년부터 2031년까지의 예측 기간 동안 연평균 성장률(CAGR) 6.99%를 나타낼 것으로 전망됩니다. 인도의 야심 찬 화학 산업 로드맵과 중국의 장쑤성 및 산둥성 특수 화학 산업 단지의 전략적 투자가 이러한 성장의 주요 원동력이 되고 있습니다. SABIC의 푸젠성 복합단지 투자(현재는 접착제용 첨가제 생산을 위해 EVA 원료를 활용 중)에 힘입어, 지역 생산자들은 배합 첨가제 시장에서의 점유율 확대를 목표로 하고 있습니다. 또한, 일본의 보조금 제도 덕분에 반도체 등급 분산제의 국내 생산이 강화되고 있습니다.
2025년에 큰 시장 점유율을 차지한 북미는 IRA(인플레이션 억제법)에 힘입은 전동화와 텍사스주에서 다우(Dow)사의 바이오에틸렌 생산 확대의 혜택을 받고 있습니다. 이 확장 프로젝트는 유변학 조절제에 필수적인 저탄소 아크릴레이트 단량체공급에 있어 매우 중요한 역할을 하고 있습니다. 멕시코에서 일고 있는 니어쇼어링 열풍은 수많은 공장 일자리를 창출하고 있으며, 컨포멀 코팅 및 열전도성 소재에 대한 수요를 급증시키고 있습니다. 이러한 재료는 계면활성제나 커플링제의 포뮬레이션에 크게 좌우됩니다. 이 지역의 특수 첨가제 생산은 풍부한 셰일가스의 지원을 받고 있지만, 수입 의존도와 원자재 가격 변동으로 어려움을 겪고 있는 유럽에는 이러한 혜택이 미치지 못하고 있습니다.
유럽에서는 EU 그린딜의 ‘Fit for 55’ 목표에 따라 시장 역학이 형성되고 있습니다. 이러한 목표에 따라, 배합 제조업체들은 수성 시스템이나 UV 경화 시스템과 같은 지속 가능한 대안을 모색하고 있습니다. 독일은 탈탄소화 보조금을 활용하여 전기식 크래커 및 바이오 시범 프로젝트를 지원함으로써, 친환경 라벨 첨가제 시장의 길을 열어가고 있습니다. 남미에서는 브라질 건설업의 회복과 아르헨티나 리튬 산업의 부상으로 시장이 활기를 띠고 있으며, 양국 모두 내식성 저수지용 코팅재에 관심을 보이고 있습니다. 한편, 중동 및 아프리카에서는 저비용 에탄 원료를 활용하고 있지만, 규제가 분산되어 있어 특수 등급의 도입이 지연되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.06.19According to Mordor Intelligence, the formulation additive market size is projected to expand from USD 21.67 billion in 2025 and USD 22.95 billion in 2026 to USD 30.84 billion by 2031, registering a CAGR of 6.09% between 2026 to 2031.
This report is Segmented by Additive Type (Defoamers, Rheology Modifiers, and More), End-Use Industry (Construction, Transportation, Automotive, Oil and Gas, and More), Formulation Technology (Water-Borne Systems, Solvent-Borne Systems, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Formulation Additive Market Trends and Insights
Sustainability-Driven Switch to Low-VOC Water-Borne Coatings
Since 2020, water-borne coatings have surged to dominate a significant share of the global architectural paint volume. This evolution aligns with the heightened VOC limit regulations imposed by authorities in the European Union and California. In light of these changes, major manufacturers are transitioning from the use of traditional glycol ethers to bio-based coalescents and are increasingly adopting associative thickeners. These thickeners, which uphold viscosity without organic solvents, have led to a notable decrease in cradle-to-gate emissions when compared with solvent-borne alternatives. BASF has introduced rheology modifiers that replicate the anti-sag characteristics of alkyds, allowing specifiers to secure LEED v4.1 credits while maintaining high application quality. Meanwhile, platforms such as Benjamin Moore's Gennex, which feature zero-VOC colorants, are reducing pigment demand, resulting in tangible raw-material cost reductions. Furthermore, in both the United States and Europe, there is a discernible trend in public-sector procurement favoring products backed by third-party environmental declarations, accelerating changes in infrastructure projects.
Expansion of Infrastructure Spending in Emerging Economies
India, under its National Chemicals Policy, is targeting a substantial boost in domestic chemical production by 2030. The policy offers foreign investors an enticing decade-long tax holiday across 12 chosen investment zones. Meanwhile, in Indonesia, the Nusantara capital project is setting a benchmark. It requires all government buildings to use low-VOC coatings, thereby increasing the demand for water-borne dispersing agents and defoamers. Saudi Arabia's Public Investment Fund is making a major investment in the NEOM industrial zone, featuring an ethylene cracker that will cater to downstream additive units. This strategic move is expected to cut logistics costs for local formulators. In Vietnam, a recent amendment to the Construction Law mandates VOC testing for skyscraper projects, paving the way for a profitable market for compliant additives by 2028. In 2024, major multilateral lenders committed significant funds to enhance Southeast Asian infrastructure, with a notable emphasis on green-building agreements, highlighting a preference for water-borne and UV-curable solutions.
Stringent REACH and TSCA Re-Registration Costs
In 2025, the European Chemicals Agency added eight substances to its Candidate List. Manufacturers face high costs for high-volume substance dossiers, excluding the essential genotoxicity testing. In the United States, the EPA requires manufacturers to report exposure data for thousands of chemicals every four years, imposing substantial fines for non-compliance. Evonik discontinued several surfactant SKUs after internal models projected a negative net present value, taking future authorization fees into account. Mid-sized firms, particularly those with product line portfolios below a certain threshold, are disproportionately burdened by these compliance costs.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Growth of High-Performance Lightweight Composites
- E-Mobility Demand for Thermal-Management Fluids and Additives
- Rising PFAS-Free Specification Bans
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, dispersing agents accounted for 33.71% of the revenue, highlighting their pivotal role in stabilizing pigments and fillers across various systems, including water-borne, solvent-borne, and UV. BASF's DISPERBYK-2150, leveraging a polyurethane backbone, curtailed the demand for TiO2, leading to cost efficiencies in paint batches.
Rheology modifiers are projected to grow at a 6.61% CAGR during the forecast period of 2026-2031, driven by the demand for shear-thinning 3D-print mortars and anti-sag vertical coatings. Associative thickeners, now adept at resisting viscosity drift even in tropical conditions, have broadened the formulation additive market's reach beyond temperate zones. Defoamers have secured a significant market share; Evonik's silicone-free introduction not only meets EU Ecolabel standards but also addresses crater-formation issues that previously challenged satin finishes. Surfactant-based wetting agents met the stringent ionic contamination standards of electronics, while a combination of coupling agents, adhesion promoters, and UV stabilizers made notable contributions to specialized niches.
Geography Analysis
In 2025, the Asia-Pacific region accounted for 42.23% of the global revenue and is projected to grow at a 6.99% CAGR during the forecast period of 2026-2031. India's ambitious chemical roadmap and China's strategic investments in specialty parks in Jiangsu and Shandong are the primary drivers of this growth. Regional producers are poised to increase their stake in the formulation additive market, bolstered by SABIC's investment in a Fujian complex, now utilizing EVA feedstock for adhesive additives. Furthermore, Japan's subsidy initiative is enhancing domestic production of semiconductor-grade dispersants.
North America, with a significant market share in 2025, is reaping benefits from IRA-driven electrification and Dow's bio-ethylene expansion in Texas. This expansion plays a crucial role in supplying low-carbon acrylate monomers, vital for rheology modifiers. The nearshoring boom in Mexico has spurred the creation of numerous factory jobs, escalating the demand for conformal coatings and thermal interface materials. These materials heavily depend on surfactant and coupling-agent packages. The region's specialty additives production enjoys a cushion from abundant shale gas, a privilege not extended to Europe, which grapples with import reliance and feedstock volatility.
Europe is steering its market dynamics in line with the EU Green Deal's Fit for 55 targets. These targets are steering formulators towards sustainable choices like water-borne and UV systems. Germany is advancing with decarbonization grants, backing electrified crackers and bio-based pilots, paving the way for a market for green-label additives. South America is buoyed by Brazil's construction resurgence and Argentina's rising lithium sector, both showing interest in corrosion-resistant pond coatings. Meanwhile, the Middle-East and Africa are leveraging low-cost ethane feedstock, though they grapple with fragmented regulations that slow the adoption of specialty grades.
- Altana (BYK)
- Arkema
- Arxada
- BASF
- Cabot Corporation
- Clariant
- Dow
- Eastman Chemical Company
- Evonik Industries AG
- Honeywell International Inc.
- Huntsman International LLC
- LANXESS
- Lubrizol
- Momentive
- Munzing Chemie GmbH
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Sustainability-driven switch to low-VOC water-borne coatings
- 4.2.2 Expansion of infrastructure spending in emerging economies
- 4.2.3 Rapid growth of high-performance lightweight composites
- 4.2.4 E-mobility demand for thermal-management fluids and additives
- 4.2.5 OEM push for sensor-friendly ultra-low-dielectric additives
- 4.3 Market Restraints
- 4.3.1 Volatile petrochemical feedstock pricing
- 4.3.2 Stringent REACH and TSCA re-registration costs
- 4.3.3 Rising PFAS-free specification bans
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Additive Type
- 5.1.1 Defoamers
- 5.1.2 Rheology Modifiers
- 5.1.3 Dispersing Agents
- 5.2 By End-use Industry
- 5.2.1 Construction
- 5.2.2 Transportation
- 5.2.3 Automotive
- 5.2.4 Oil and Gas
- 5.2.5 Food and Beverage
- 5.2.6 Electronics
- 5.2.7 Other End-user Industries
- 5.3 By Formulation Technology
- 5.3.1 Water-borne Systems
- 5.3.2 Solvent-borne Systems
- 5.3.3 Powder Coatings
- 5.3.4 UV/EB-curable Systems
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Altana (BYK)
- 6.4.2 Arkema
- 6.4.3 Arxada
- 6.4.4 BASF
- 6.4.5 Cabot Corporation
- 6.4.6 Clariant
- 6.4.7 Dow
- 6.4.8 Eastman Chemical Company
- 6.4.9 Evonik Industries AG
- 6.4.10 Honeywell International Inc.
- 6.4.11 Huntsman International LLC
- 6.4.12 LANXESS
- 6.4.13 Lubrizol
- 6.4.14 Momentive
- 6.4.15 Munzing Chemie GmbH
- 6.4.16 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Advanced Computational Modeling and In-silico Simulations