|
시장보고서
상품코드
2113308
아시아태평양의 가변 주파수 드라이브 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Asia-Pacific Variable Frequency Drives - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
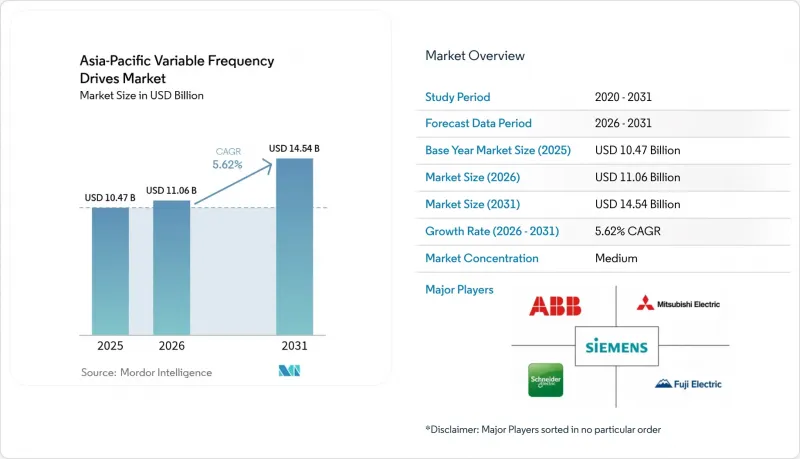
에 따르면 2026년 아시아태평양의 가변 주파수 드라이브(VFD) 시장 규모는 110억 6,000만 달러로 추정되고 있으며, 2025년 104억 7,000만 달러에서 확대하며, 2031년에는 145억 4,000만 달러에 달할 것으로 예측됩니다.
2026-2031년 동안 연평균 성장률(CAGR) 5.62%로 성장할 것으로 전망됩니다.
이 보고서는 유형별(AC, DC, 서보 드라이브), 전압 등급별(저전압, 중전압), 정격 출력별(마이크로, 저출력, 중출력, 고출력), 용도별(펌프, 팬, 압축기, 컨베이어,HVAC, 기타), 최종사용자 산업별(석유 및 가스, 에너지·발전, 기타), 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
아시아태평양 가변 주파수 드라이브 시장의 동향 및 인사이트
중국과 인도의 정부 주도 산업용 에너지 효율 규제
현재 각국의 규제에 따라 산업 설비의 교체는 정량화된 에너지 성능 목표와 연계되어 있습니다. 중국에서는 2024년에 규격 적용 대상이 23개 제품 범주로 확대되고, 공장에 고효율 모터 및 이에 대응하는 드라이브의 채택이 의무화됨에 따라 개조 건수가 급격히 증가할 것으로 예상됩니다. 뉴델리 예산에는 350만 대의 관개용 펌프를 태양광발전 방식으로 전환하기 위해 650억 인도 루피(7억 8,000만 달러)가 배정되어 있으며, 이를 통해 VFD가 분산형 재생에너지 시스템에 직접 통합될 것입니다. 중국의 2060년 탄소 중립 목표와 인도의 재생 가능 에너지 추진 정책에 부합하는 이러한 조치들은 공급망 전체에 파급 효과를 미치고 있으며, 현지 OEM 기업에게 IEC 규격을 준수하고 다양한 센서가 탑재된 드라이브에 대한 대규모 인증 획득을 촉진하고 있습니다. 20-40%의 전력 절감 효과를 입증할 수 있는 공급업체는 현재 정부 조달 과정에서 우선적으로 선정되고 있습니다.
정밀한 HVAC 드라이브가 필요한 데이터센터의 급속한 확대
아시아태평양의 데이터센터에 대한 설비 투자액은 2025년까지 750억 달러를 넘어 북미를 추월할 것으로 예측됩니다. 서버의 고밀도화로 인해 열 부하가 증가함에 따라 사업자들은 정속 칠러에서 VFD 기반 냉각 루프로 전환하고 있습니다. 베이징과 싱가포르의 PUE(전력 사용 효율) 규제는 동적 기류 제어를 촉진하고 있으며, 실리콘 카바이드(SiC) 파워 스테이지의 채택으로 HVAC의 에너지 소비량이 연간 최대 17%까지 절감되고 있습니다. 필드버스가 내장되고 사이버 보안 대책이 적용된 펌웨어를 갖춘 드라이브는 빌딩 관리 시스템에 대한 실시간 피드백을 가능하게 하여, 냉각을 단순한 비용 센터에서 성능의 변수로 전환하고 있습니다.
저비용 중국 공급업체와의 경쟁
Inovance와 Hiconics를 비롯한 중국 공급업체들의 공격적인 가격 책정은 특히 40kW 이하 부문에서 프리미엄 브랜드의 이익률을 압박하고 있습니다. 베이징시의 친환경 산업 정책 지원을 바탕으로, 이들 기업은 세계 평균보다 15-25% 낮은 가격을 책정하고 있습니다. 고객은 설비 투자 비용 절감이라는 혜택을 누리는 한편, 가격 경쟁의 격화는 첨단 토폴로지 및 사이버 보안 기능을 위한 장기적인 연구개발 자금을 위협하고 있습니다. Tier 1 주요 기업은 드라이브에 디지털 서비스 계약이나 연장 보증을 묶어 제공하는 방식에 대응하고 있으며, 초기 비용이 아닌 수명주기 가치를 중시하는 사업 모델로 전환을 모색하고 있습니다.
부문 분석
AC 드라이브는 펌프, 팬, 컨베이어 등 폭넓은 용도에 대응할 수 있는 범용성을 강점으로 삼아, 2025년 매출의 73.40%를 계속 차지했습니다. 아시아태평양의 서보 유닛용 가변 주파수 드라이브 시장 규모는 로봇 공학,CNC 가공, 협업형 코봇의 보급에 힘입어 연평균 성장률(CAGR) 8.02%로 급속히 확대될 것으로 예측됩니다. 수명 주기 경제성 측면에서는 정토크 용도에서 AC 유닛이 유리하지만, 서보 유닛은 ±0.01° 이내의 위치 결정 정밀도를 실현하므로 그 높은 가격 프리미엄은 정당화됩니다. 현재 사이클에서 서보 채택이 가장 활발한 곳은 한국과 일본의 전자기기 조립 라인입니다. 실리콘 카바이드(SiC) 파워 스테이지와 내장형 인코더를 통해 마이크로초 수준의 피드백이 가능해져, 오버슈트 및 불량률 감소로 이어지고 있습니다. 각 OEM 업체들이 기계의 소형화를 추진하는 가운데, 기판 실장형 드라이브와 PCB 고정자 모터를 통해 캐비닛의 설치 면적이 축소되어, 공간이 제한된 공장 현장에 사후 설치가 가능해졌습니다.
서비스 모델도 다양해지고 있습니다. AC 드라이브에는 일반적으로 5년 보증과 기본적인 모니터링 기능이 포함되어 있지만, 서보 패키지에는 토크 리플이나 진동을 추적하는 클라우드 대시보드가 내장되어 있습니다. 각 공급업체는 알고리즘을 활용하여 수주 전부터 베어링 마모를 예측하는 ‘MaaS(Maintenance-as-a-Service)’ 계약의 업셀링을 추진하고 있습니다. 이러한 일회성 판매에서 지속적 수익으로의 전환은 아시아태평양의 가변 주파수 드라이브 시장 전반에 걸쳐 유통 채널의 인센티브 구조를 재편하고 있습니다.
690V 이하의 저전압 시스템은 2025년 출하 대수의 86.90%를 차지하고 있으며, 이는 해당 지역의 중소형 모터 집중 현상을 반영하고 있습니다. 그러나 석유화학 단지, 해수 담수화 플랜트, 지하철 프로젝트에서 펌프 가동 규모가 확대됨에 따라 중전압 부문은 연평균 성장률(CAGR) 6.85%로 성장할 것으로 예측됩니다. IEC에 의한 고전압 모터에 대한 최초의 효율 등급 제도가 도입됨에 따라 EPC 계약업체들은 THD(전체 고조파 왜곡) 제한치를 준수하기 위해 액티브 프론트 엔드 구성을 도입하고 있습니다. 기온이 40°C를 넘는 시장에서는 아시아태평양 가변 주파수 드라이브 시장에서 공랭식 중전압 패키지의 점유율이 확대되고 있으며, 각 벤더들은 정격 저하에도 강한 방열 합금 개발에 주력하고 있습니다.
제품 전략은 모듈식 구성 요소로 수렴하고 있습니다. 인출식 파워 셀은 현장에서의 교체를 간소화하고, 디지털 트윈은 취약한 전력망과의 증가파 상호 작용을 시뮬레이션하여 시운전 시간을 20% 단축합니다. 저전압 플랫폼은 회생 제동 및 STO(안전 토크 차단) 기능을 통해 지속적인 혁신을 이루며, 무인운반차(AGV)를 도입하는 내부 물류 및 창고업 고객의 요구를 충족시키고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.08.25According to Mordor Intelligence, Asia-Pacific variable frequency drives market size in 2026 is estimated at USD 11.06 billion, growing from 2025 value of USD 10.47 billion with 2031 projections showing USD 14.54 billion, growing at 5.62% CAGR over 2026-2031.
This report is Segmented by Type (AC, DC, and Servo Drives), Voltage Class (Low-Voltage and Medium-Voltage), Power Rating (Micro, Low, Medium, and High), Application (Pumps, Fans, Compressors, Conveyors, HVAC, and Others), End-User Industry (Oil and Gas, Energy and Power, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Asia-Pacific Variable Frequency Drives Market Trends and Insights
Government-Led Industrial Energy-Efficiency Mandates in China and India
National regulations now tie industrial upgrades to quantified energy-performance targets. China's 2024 specification expansion to 23 product categories obliges factories to adopt premium-efficiency motors and matching drives, prompting a step-change in retrofit volumes. New Delhi's budget sets aside INR 6,500 crore (USD 780 million) to solarize 3.5 million irrigation pumps, directly embedding VFDs into distributed renewable systems. These measures, aligned with China's 2060 carbon-neutrality goal and India's renewable energy push, are cascading through supply chains, prompting local OEMs to certify IEC-compliant, sensor-rich drives at scale. Vendors able to prove 20-40% electricity savings now enjoy priority listing in government procurement.
Rapid Build-Out of Data Centers Requiring Precision HVAC Drives
Asia Pacific data-center capex is projected to surpass USD 75 billion by 2025, overtaking North America. Server-densification elevates thermal loads, so operators are shifting from fixed-speed chillers to VFD-based cooling loops. PUE mandates in Beijing and Singapore encourage dynamic airflow control, and silicon-carbide power stages are cutting HVAC energy draw by up to 17% annually. Drives with embedded fieldbus and cyber-secure firmware enable real-time feedback to building-management systems, turning cooling from a cost center into a performance variable.
Price Competition from Low-Cost Chinese Vendors
Aggressive pricing from Inovance, Hiconics, and other Chinese suppliers erodes margins for premium brands, particularly in the <40 kW bracket. With support from Beijing's green-industrial policy, these firms price 15-25% below global averages. While customers enjoy lower capex, a race-to-the-bottom threatens long-term R&D funding for advanced topologies and cybersecurity features. Tier-one players are countering by bundling drives with digital service contracts and extended warranties, repositioning themselves on lifecycle value rather than upfront cost.
Other drivers and restraints analyzed in the detailed report include:
- Manufacturing-Sector Automation Wave Post-2023
- Rising Electricity Tariffs Prompting Energy-Saving Retrofits
- Skilled Workforce Shortage for VFD Commissioning in ASEAN
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
AC drives retained a 73.40% command of 2025 revenues, anchored by their versatility across pumps, fans, and conveyors. The Asia-Pacific variable frequency drives market size for servo units is forecast to jump at an 8.02% CAGR as robotics, CNC machining, and collaborative cobots proliferate. Lifecycle economics favour AC units in constant-torque uses, but the servo's higher price premium is justified by positional accuracy within +-0.01°. In the current cycle, servo adoption is strongest in electronics assembly lines of South Korea and Japan. Silicon-carbide power stages and embedded encoders now enable microsecond-level feedback, reducing overshoot and scrap rates. As OEMs miniaturize machinery, board-mount drives and PCB stator motors are shrinking cabinet footprints, enabling retrofit into crowded factory floors.
Service models are also diverging. AC drives typically ship with five-year warranties and basic monitoring, while servo packages bundle cloud dashboards that track torque ripple and vibration. Suppliers are upselling maintenance-as-a-service contracts that utilize algorithms to predict bearing wear weeks in advance. This shift from transactional sales to recurring revenue is reshaping channel incentives across the Asia-Pacific variable frequency drives market.
Low-voltage systems <690 V command 86.90% of 2025 shipments, a reflection of the region's concentration of small to mid-sized motors. Yet, the medium-voltage segment is expanding at a forecasted 6.85% CAGR as petrochemical complexes, desalination plants, and metro-rail projects scale up pump duties. IEC's first-ever efficiency grading for high-voltage motors has prompted EPC contractors to integrate active-front-end configurations to comply with THD limits. The Asia-Pacific variable frequency drives market share for air-cooled medium-voltage packages is growing in markets where ambient temperatures exceed 40°C, prompting vendors to develop derating-resistant heat-sink alloys.
Product strategy is converging on modular building blocks. Drawer-style power cells simplify field replacement; digital twins simulate harmonic interaction with weak grids, reducing commissioning time by 20%. Low-voltage platforms continue to innovate with regenerative braking and STO (Safe Torque Off) functions, catering to intralogistics and warehousing clients adopting automated guided vehicles.
Complete Report Scope:
- By Type
- AC Drives
- DC Drives
- Servo Drives
- By Voltage Class
- Low-Voltage (More than 690 V)
- Medium-Voltage (1 - 35 kV)
- By Power Rating (kW)
- Micro (Less than 5 kW)
- Low (6 - 40 kW)
- Medium (41 - 200 kW)
- High (More than 200 kW)
- By Application
- Pumps
- Fans
- Compressors
- Conveyors
- HVAC
- Extruders
- Others
- By End-User Industry
- Oil and Gas
- Energy and Power
- Water and Waste-water Management
- Food and Beverage Processing
- Pulp and Paper
- Metals and Mining
- Chemicals and Petrochemicals
- Marine and Shipbuilding
- Other Industries
- By Country
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
List of Companies Covered in this Report:
- ABB Ltd
- Siemens AG
- Mitsubishi Electric Corporation
- Schneider Electric SE
- Fuji Electric Co. Ltd
- Hitachi Ltd
- Toshiba Corporation
- Yaskawa Electric Corp.
- Delta Electronics Inc.
- Danfoss A/S
- Rockwell Automation Inc.
- Eaton Corporation plc
- Emerson Electric Co.
- Johnson Controls International plc
- Parker Hannifin Corp.
- WEG SA
- LS Electric Co. Ltd
- Inovance Technology Co. Ltd
- Nidec (Control Techniques)
- CHINT Group (Hiconics Drive)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Government-led Industrial Energy-Efficiency Mandates in China and India
- 4.2.2 Manufacturing-Sector Automation Wave Post-2023
- 4.2.3 Rising Electricity Tariffs Prompting Energy-Saving Retrofits
- 4.2.4 Rapid Build-out of Data Centres Requiring Precision HVAC Drives
- 4.2.5 Infrastructure Boom in Southeast Asia Boosting Pumps and Fans Demand
- 4.2.6 Shift to Electric Propulsion in Mining and Marine Equipment
- 4.3 Market Restraints
- 4.3.1 Price Competition from Low-Cost Chinese Vendors
- 4.3.2 Harmonic and EMI Compliance Challenges in Medium-Voltage Drives
- 4.3.3 Subsidy Withdrawal for Industrial Efficiency Projects in Australia
- 4.3.4 Skilled Workforce Shortage for VFD Commissioning in ASEAN
- 4.4 Value-Chain Analysis
- 4.5 Regulatory and Technological Outlook
- 4.6 Technology Snapshot
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 AC Drives
- 5.1.2 DC Drives
- 5.1.3 Servo Drives
- 5.2 By Voltage Class
- 5.2.1 Low-Voltage (More than 690 V)
- 5.2.2 Medium-Voltage (1 - 35 kV)
- 5.3 By Power Rating (kW)
- 5.3.1 Micro (Less than 5 kW)
- 5.3.2 Low (6 - 40 kW)
- 5.3.3 Medium (41 - 200 kW)
- 5.3.4 High (More than 200 kW)
- 5.4 By Application
- 5.4.1 Pumps
- 5.4.2 Fans
- 5.4.3 Compressors
- 5.4.4 Conveyors
- 5.4.5 HVAC
- 5.4.6 Extruders
- 5.4.7 Others
- 5.5 By End-User Industry
- 5.5.1 Oil and Gas
- 5.5.2 Energy and Power
- 5.5.3 Water and Waste-water Management
- 5.5.4 Food and Beverage Processing
- 5.5.5 Pulp and Paper
- 5.5.6 Metals and Mining
- 5.5.7 Chemicals and Petrochemicals
- 5.5.8 Marine and Shipbuilding
- 5.5.9 Other Industries
- 5.6 By Country
- 5.6.1 China
- 5.6.2 Japan
- 5.6.3 India
- 5.6.4 South Korea
- 5.6.5 Rest of Asia-Pacific
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Mitsubishi Electric Corporation
- 6.4.4 Schneider Electric SE
- 6.4.5 Fuji Electric Co. Ltd
- 6.4.6 Hitachi Ltd
- 6.4.7 Toshiba Corporation
- 6.4.8 Yaskawa Electric Corp.
- 6.4.9 Delta Electronics Inc.
- 6.4.10 Danfoss A/S
- 6.4.11 Rockwell Automation Inc.
- 6.4.12 Eaton Corporation plc
- 6.4.13 Emerson Electric Co.
- 6.4.14 Johnson Controls International plc
- 6.4.15 Parker Hannifin Corp.
- 6.4.16 WEG SA
- 6.4.17 LS Electric Co. Ltd
- 6.4.18 Inovance Technology Co. Ltd
- 6.4.19 Nidec (Control Techniques)
- 6.4.20 CHINT Group (Hiconics Drive)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment