|
시장보고서
상품코드
2114365
산화칼슘 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Calcium Oxide - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
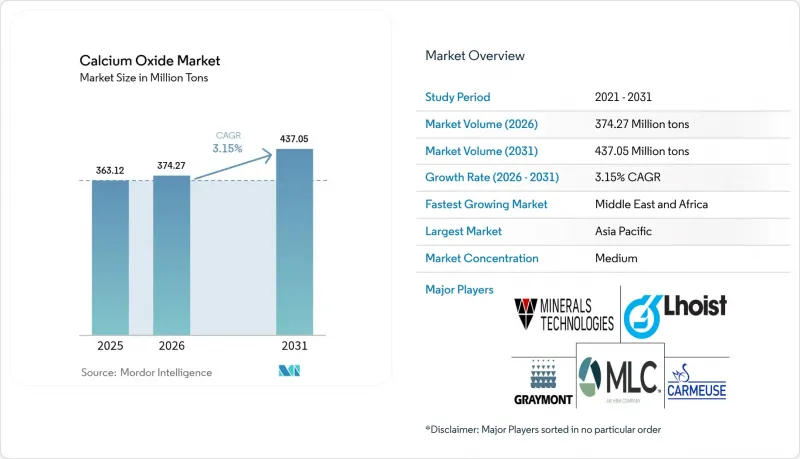
에 따르면 산화칼슘 시장 규모는 2025년에 3억 6,312만 톤으로 평가되며, 2026년 3억 7,427만 톤에서 2031년까지 4억 3,705만 톤에 달할 것으로 추정되고 있으며, 예측 기간(2026-2031년)에 CAGR은 3.15%에 달할 전망입니다.
이 보고서는 최종사용자 산업별(야금, 건설, 비료·화학제품, 펄프·제지, 내화물, 기타 최종사용자 산업) 및 지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 구분되어 있습니다. 시장 예측은 톤 기준으로 제시되어 있습니다.
세계 산화칼슘 시장의 동향 및 인사이트
전 세계 조강 생산량의 급증
철강 산업은 여전히 산화칼슘의 최대 단일 소비 산업이며, 고로 기술에 따라 조강 1톤당 15-50kg의 생석회를 사용하고 있습니다. 중국은 2024년에 10억 톤을 약간 상회하는 조강을 생산했는데, 이는 소폭 감소한 수치이긴 하지만 여전히 다른 어떤 시장보다 큰 규모입니다. OECD의 예측에 따르면 2030년까지의 신규 제철 생산 능력 중 40.5%는 계속해서 고로·전로(BF-BOF) 방식을 채택할 것이며, 전기로(EAF)의 보급률이 서서히 높아지는 가운데서도 생석회 사용량은 현재 수준을 유지할 것으로 전망됩니다. 인도의 ‘국가 철강 정책’은 2030년까지 3억 톤의 생산 능력을 목표로 하고 있으며, 그 대부분이 고로·전로 방식이므로 생석회 수요가 지속적으로 확보될 것입니다. 국제에너지기구(IEA)의 추산에 따르면 제강 공정에서 발생하는 플럭스는 연간 0.3기가톤의 공정 CO₂를 배출하고 있으며, 이는 CCS(탄소 포집 및 저장) 설비를 갖춘 키른의 도입이 기후변화 대책으로서 중요함을 지원하고 있습니다. 이러한 요인들이 종합적으로 작용함으로써, 철강 수요 증가가 보수적인 시나리오라 하더라도 산화칼슘 시장의 수요 하한선이 지탱되고 있습니다.
아시아태평양 및 아프리카 지역의 인프라·시멘트 수요 급증
인도의 경우, 클링커 대 시멘트 비율이 0.75에 가까운 것을 배경으로, 2025 회계연도의 시멘트 생산량은 4억 5,300만 톤에 달했습니다. 아세안(ASEAN)의 주요 경제국들은 철도, 고속도로, 저렴한 주택에 공공 예산을 투자하고 있으며, 2030년까지 매년 4-5%의 속도로 지역 시멘트 생산량을 끌어올리고 있습니다. 사우디아라비아의 ‘비전 2030’ 메가 프로젝트에서는 막대한 양의 저탄소 콘크리트가 필요합니다. 얀부에 위치한 일일 5,000톤 규모의 클링커 프리 생산 라인은 고순도 CaO가 포틀랜드 클링커를 대체할 수 있으며, 동시에 매립 탄소를 최대 80%까지 감축할 수 있음을 입증하고 있습니다. 사하라 사막 이남의 아프리카에서는 3,270만 헥타르에 달하는 산성 토양이 농작물 수확량을 저하시키고 있으며, 건설 산업의 성장과 시너지 효과를 가져올 농업용 석회 프로그램이 추진되고 있습니다. 이러한 인프라 및 농업 관련 노력들이 맞물려 산화칼슘 시장의 견고한 수요 확대 추세를 지원하고 있습니다.
높은 에너지 비용·CO₂ 비용, 가마 배출 규제의 강화
생석회 1톤을 생산하는 데는 3.2-4.5GJ의 열에너지가 소비되며, 가스 연소 가마의 경우 천연가스비가 현금 비용의 60%를 차지하는 경우도 있습니다. 톤당 80유로에 가까운 EU의 탄소 가격은, 제품 1톤당 약 0.8톤의 CO₂를 배출하는 기존 가마의 경우, 생석회 1톤당 60-70유로의 추가 비용에 해당합니다. ETS 4단계에서 무료 할당량의 감축으로 인해 이러한 부담은 해마다 증가하고 있습니다. 미국에서는 각 주에서 도입이 진행되고 있는 새로운 제도와 더욱 엄격해진 신규 배출원 성능 기준(NSPS)에 따라 선택적 촉매 환원(SCR) 및 천 필터의 도입이 의무화되어 있으며, 이는 생산 능력을 확대하지 않고도 설비 투자(CAPEX)를 증가시키고 있습니다. 소규모 독립 생산자들에게는 이러한 설비 갱신을 위한 자금 조달이 점점 더 어려워지고 있으며, 이는 산화칼슘 시장의 산업 재편 추세를 부추기고 있습니다.
부문 분석
2025년, 야금 부문은 산화칼슘 시장 점유율의 42.57%를 차지할 것으로 예상되며, 이는 고로·전로(BF-BOF) 제강에서 플럭스로서의 중요한 역할을 반영한 것입니다. 전 세계에서 전기로(EAF) 기술로 전환됨에 따라 석회 사용량은 철강 1톤당 5-15kg까지 감소하고 있지만, 인도의 고로 중심 확장과 중국의 일체형 제철 능력 유지로 인해 절대적인 수요량은 유지되고 있습니다. 용해로 내벽용 내화물 등급의 CaO는 신규 진입을 제한하는 품질 인증에 힘입어 높은 가격에 거래되고 있습니다.
건설 부문은 인도의 시멘트 생산량 4억 5,300만 톤과 아세안(ASEAN)의 인프라 붐으로 인해 호황을 누리고 있습니다. 비료·화학 제품 부문은 가장 빠르게 성장하는 최종사용자 산업으로, 2031년까지 연평균 성장률(CAGR) 4.16%로 성장하고 있습니다. 펄프·제지 공장에서는 크라프트 공법에 의한 가성 처리 공정에서 펄프 1톤당 80-120kg의 소석회가 안정적으로 사용되고 있습니다. 전반적으로 비야금 산업은 다각화를 가져오고 있으며, 철강 사이클의 변동으로부터 산화칼슘 시장을 보호하는 역할을 하고 있습니다.
지역별 분석
아시아태평양은 중국의 대규모 철강 및 시멘트 부문과 인도의 가속화되는 인프라 구축 계획에 힘입어 2025년 물량의 49.32%를 차지하며 산화칼슘 시장을 주도했습니다. 중국의 시멘트 가마에 대한 초저배출 규제로 인해 건설 수요 증가세가 둔화되고 있음에도 불구하고 FGD용 석회에 대한 새로운 수요가 발생하고 있습니다. 인도 정부는 ‘국가 인프라 계획’에 따라 1조 4,000억 달러를 배정하여 시멘트 생산 능력 확충과 1,000만 헥타르에 달하는 산성 토양에 대한 농업용 석회 공급을 지속하고 있습니다.
북미에서는 ‘인프라 투자 및 고용법’의 혜택을 받고 있습니다. 이 법은 고속도로 포장 재포장, 교량 보수, 상수도 시스템 개보수에 자금을 지원하고 있으며, 이 모든 분야에서 아스팔트 개질 및 수질 연화 처리에 CaO가 사용되고 있습니다. 미국의 철강 산업에서는 전기로(EAF) 미니밀로의 전환으로 인해 석회 사용량은 감소하고 있지만, 자동차 및 가전제품 생산으로 인해 전반적인 수요는 견고한 추세를 보이고 있습니다. 멕시코에서는 니어쇼어링에 힘입은 건설업의 성장을 바탕으로, Grupo Calidra가 바히오 지역의 생산 능력을 확대하여 지역 산화칼슘 시장을 강화했습니다.
유럽에서는 높은 에너지 비용과 엄격한 탄소 배출 목표 하에서 사업이 전개되고 있습니다. 규정 2024/2620에서는 광물 탄산염이 영구적인 탄소 흡수원으로 분류되어 있으며, CCS(탄소 포집 및 저장) 대응 소성로 및 알칼리 활성화 결합재용 고순도 CaO의 이용이 촉진되고 있습니다. 독일과 프랑스는 저탄소 시멘트의 실증 실험을 주도하고 있는 반면, 폴란드와 루마니아는 철강용 비용 경쟁력 있는 등급에 중점을 두고 있습니다. 연평균 성장률(CAGR) 3.98%가 예상되는 중동 및 아프리카에서는 ‘사우디 비전 2030’의 메가 프로젝트와 사하라 이남 아프리카의 토양 석회화 프로그램이 수요를 견인하고 있습니다. 남미의 수요는 브라질 세라두 지역의 농업과 아르헨티나의 리튬 염수 처리에 좌우되고 있으며, 두 분야 모두 pH 조절 및 불순물 제거를 위해 생석회에 의존하고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.08.26According to Mordor Intelligence, the calcium oxide market size was valued at 363.12 Million tons in 2025 and is estimated to grow from 374.27 Million tons in 2026 to reach 437.05 Million tons by 2031, at a CAGR of 3.15% during the forecast period (2026-2031).
This report is Segmented by End-User Industry (Metallurgical, Construction, Fertilizer and Chemicals, Pulp and Paper, Refractory, and Other End-User Industries) and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Calcium Oxide Market Trends and Insights
Surging Global Crude-Steel Output
Steel remains the single-largest consumer of calcium oxide, using 15-50 kilograms of quicklime per ton of crude steel, depending on furnace technology. China produced just over 1.0 billion tons of crude steel in 2024, a marginal decline yet still outsizing every other market. The OECD projects that 40.5% of new steel capacity through 2030 will continue to use the BF-BOF route, preserving lime intensity even as EAF penetration inches higher. India's National Steel Policy targets 300 million tons of capacity by 2030, largely BF-BOF, effectively locking in sustained quicklime offtake. The International Energy Agency calculates that fluxes in steelmaking account for 0.3 gigatons of process CO2 annually, underscoring the climate case for CCS-equipped kilns. Collectively, these factors underpin a demand floor for the calcium oxide market even under conservative steel-growth scenarios.
Rapid Infrastructure and Cement Demand in Asia-Pacific and Africa
Cement output reached 453 million tons in India during fiscal 2025, supported by a clinker-to-cement ratio near 0.75. Major ASEAN economies are plowing public budgets into rail, highways, and affordable housing, lifting regional cement production by 4-5% each year through 2030. Saudi Arabia's Vision 2030 megaprojects require huge volumes of low-carbon concrete; a 5,000-ton-per-day clinker-free line at Yanbu showcases how high-purity CaO can substitute Portland clinker while cutting embodied carbon by up to 80%. In Sub-Saharan Africa, 32.7 million hectares of acid soils are depressing crop yields, spurring agricultural-lime programs that dovetail with construction growth. These converging infrastructure and agricultural initiatives reinforce a robust volume trajectory for the calcium oxide market.
High Energy and CO2 Costs, Tightening Kiln-Emission Limits
Producing one ton of quicklime consumes 3.2-4.5 GJ of thermal energy, and natural gas can represent 60% of cash costs for gas-fired kilns. EU carbon prices near EUR 80 per ton of CO2 translate into an additional EUR 60-70 per ton of quicklime for legacy kilns emitting roughly 0.8 tons CO2 per ton product. Free-allowance reductions under ETS Phase IV intensify this burden each year. In the United States, emerging state-level programs and stricter New Source Performance Standards compel selective catalytic reduction and fabric-filter retrofits that raise capex without expanding capacity. Small, standalone producers find it increasingly difficult to finance such upgrades, feeding a consolidation trend in the calcium oxide market.
Other drivers and restraints analyzed in the detailed report include:
- Stricter Emissions Rules Boosting CaO Use in FGD and Water Treatment
- Low-Carbon Cement and Carbon-Looping Technologies Requiring High-Purity CaO
- Limestone and Natural-Gas Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Metallurgical segment accounted for 42.57% of calcium oxide market share in 2025, reflecting its critical function as a flux in BF-BOF steelmaking. Although the global shift toward EAF technology lowers lime intensity to 5-15 kg per ton of steel, India's BF-centric expansion and persistent integrated capacity in China sustain absolute volume demand. Refractory-grade CaO for ladle linings commands price premiums, underpinned by quality certifications that limit new entrants.
Construction is energized by India's 453-million-ton cement output and ASEAN's infrastructure boom. Fertilizer and Chemicals is the fastest-expanding end-user industry, advancing at a 4.16% CAGR through 2031. Pulp and Paper mills retain stable quicklime usage of 80-120 kg per ton of pulp in kraft causticizing loops. Collectively, non-metallurgical industries provide diversification that cushions the calcium oxide market against steel-cycle volatility.
Complete Report Scope:
- By End-user Industry
- Metallurgical
- Construction
- Fertilizer and Chemicals
- Pulp and Paper
- Refractory
- Other End-user Industries (Rubber, Food and Beverages)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Russia
- Spain
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific led the calcium oxide market with 49.32% of 2025 volume, anchored by China's massive steel and cement sectors and India's accelerating infrastructure pipeline. Ultra-low-emission mandates for Chinese cement kilns are generating fresh demand for FGD-grade lime even as construction growth moderates. India's government has allocated USD 1.4 trillion under its National Infrastructure Pipeline, sustaining cement capacity additions and farm-lime distribution across 10 million hectares of acid soils.
North America benefits from the Infrastructure Investment and Jobs Act, which funds highway resurfacing, bridge rehabilitation, and water-system upgrades, all of which employ CaO in asphalt modification and water-softening treatments. While the U.S. steel sector's pivot toward EAF mini-mills reduces lime intensity, overall demand remains resilient due to automotive and appliance output. Mexico's nearshoring-boosted construction growth prompted Grupo Calidra to expand Bajio capacity, reinforcing the regional calcium oxide market.
Europe operates under high energy costs and stringent carbon targets. Regulation 2024/2620 classifies mineral carbonates as permanent sinks, encouraging CCS-ready kilns and high-purity CaO for alkali-activated binders. Germany and France lead low-carbon cement trials, whereas Poland and Romania emphasize cost-competitive grades for steel. The Middle-East and Africa region, projected to grow at 3.98% CAGR, leverages Saudi Vision 2030 megaprojects and sub-Saharan soil-liming programs. South America's demand hinges on Brazil's Cerrado agriculture and Argentina's lithium brine processing, both reliant on quicklime for pH moderation and impurity removal.
- AKJ Minchem Private Limited
- American Elements
- Astrra Chemicals
- CAO Industries Sdn Bhd
- Carmeuse
- GRAYMONT
- GREER LIME COMPANY
- Grupo Calidra
- Imerys
- Kemipex
- Lhoist
- Linwood Mining & Minerals Corporation
- Minerals Technologies Inc.
- Mississippi Lime Company d/b/a MLC.
- Nordkalk
- Pacific Lime and Cement Limited
- Pete Lien & Sons, Inc.
- Sibelco
- Sigma Minerals Ltd
- United States Lime & Minerals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging global crude-steel output
- 4.2.2 Rapid infrastructure and cement demand in Asia-Pacific and Africa
- 4.2.3 Stricter emissions rules boosting CaO use in Flue Gas Desulfurization (FGD) and water treatment
- 4.2.4 Agricultural soil-health programs in emerging economies
- 4.2.5 Low-carbon cement and carbon-looping technologies requiring high-purity CaO
- 4.3 Market Restraints
- 4.3.1 High energy and CO2 costs, tightening kiln-emission limits
- 4.3.2 Limestone and natural-gas price volatility
- 4.3.3 Alternative sorbents/fluxes gaining share in steel
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By End-user Industry
- 5.1.1 Metallurgical
- 5.1.2 Construction
- 5.1.3 Fertilizer and Chemicals
- 5.1.4 Pulp and Paper
- 5.1.5 Refractory
- 5.1.6 Other End-user Industries (Rubber, Food and Beverages)
- 5.2 By Geography
- 5.2.1 Asia-Pacific
- 5.2.1.1 China
- 5.2.1.2 India
- 5.2.1.3 Japan
- 5.2.1.4 South Korea
- 5.2.1.5 ASEAN Countries
- 5.2.1.6 Rest of Asia-Pacific
- 5.2.2 North America
- 5.2.2.1 United States
- 5.2.2.2 Canada
- 5.2.2.3 Mexico
- 5.2.3 Europe
- 5.2.3.1 Germany
- 5.2.3.2 United Kingdom
- 5.2.3.3 Italy
- 5.2.3.4 France
- 5.2.3.5 Russia
- 5.2.3.6 Spain
- 5.2.3.7 Rest of Europe
- 5.2.4 South America
- 5.2.4.1 Brazil
- 5.2.4.2 Argentina
- 5.2.4.3 Rest of South America
- 5.2.5 Middle-East and Africa
- 5.2.5.1 Saudi Arabia
- 5.2.5.2 South Africa
- 5.2.5.3 Rest of Middle-East and Africa
- 5.2.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 AKJ Minchem Private Limited
- 6.4.2 American Elements
- 6.4.3 Astrra Chemicals
- 6.4.4 CAO Industries Sdn Bhd
- 6.4.5 Carmeuse
- 6.4.6 GRAYMONT
- 6.4.7 GREER LIME COMPANY
- 6.4.8 Grupo Calidra
- 6.4.9 Imerys
- 6.4.10 Kemipex
- 6.4.11 Lhoist
- 6.4.12 Linwood Mining & Minerals Corporation
- 6.4.13 Minerals Technologies Inc.
- 6.4.14 Mississippi Lime Company d/b/a MLC.
- 6.4.15 Nordkalk
- 6.4.16 Pacific Lime and Cement Limited
- 6.4.17 Pete Lien & Sons, Inc.
- 6.4.18 Sibelco
- 6.4.19 Sigma Minerals Ltd
- 6.4.20 United States Lime & Minerals
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment