|
시장보고서
상품코드
2114435
카프노그래피 기기 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Capnography Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
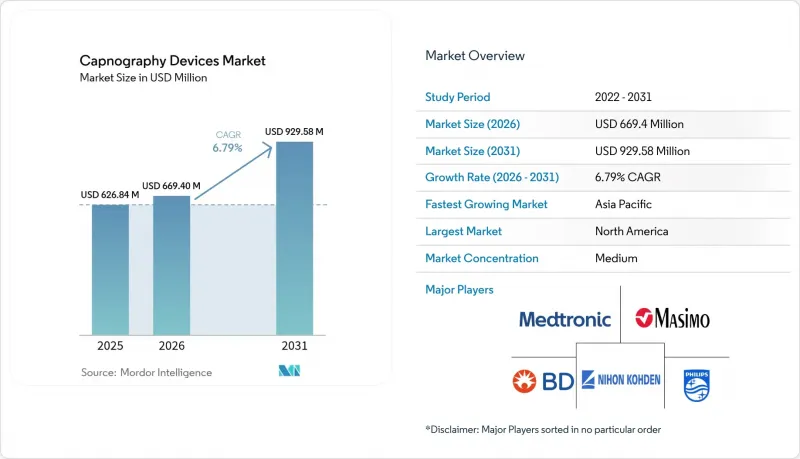
에 의하면, 카프노그래피 기기 시장 규모는 2025년 6억 2,684만 달러에서 2026년에는 6억 6,940만 달러로 확대되고, 2026-2031년 CAGR 6.79%로 성장을 지속하여 2031년에는 9억 2,958만 달러에 달할 것으로 예측됩니다.
본 보고서에서는 해당 시장을 제품별(휴대용, 독립형), 기술별(사이드스트림, 메인스트림, 마이크로스트림), 용도별(중환자 치료, 수면 검사, 기타), 최종 사용자별(병원, 외래수술센터(ASC), 기타 최종 사용자), 지역별로 분류하고 있습니다. 시장 규모 및 전망은 금액(달러)으로 표시되어 있습니다.
세계 카프노그래피 기기 시장 동향 및 인사이트
전 세계 수술 건수 증가
2024년에는 외래수술센터(ASC)에서 330만 명의 메디케어 수혜자가 치료를 받았으며, 신뢰할 수 있는 호흡 모니터링이 필수적인 외래 진료로의 체계적인 전환이 두드러지게 나타났습니다. 회복 촉진 프로토콜의 강화와 점점 더 복잡해지는 최소 침습 수술 기술로 인해, 산소 포화도가 떨어지기 전에 저환기를 감지하기 위한 실시간 CO2 측정이 요구되고 있습니다. 수술실 밖에서 중등도 진정 요법을 채택하는 진료과가 늘어남에 따라, 카프노그래피 기기 도입은 소화기내과, 심장내과, 통증 관리 팀 사이에서 확산되고 있습니다. 현재 구매 결정 시에는 휴대성이 뛰어나고, 배터리로 구동되며 Wi-Fi를 지원하는 모니터가 우선시되고 있으며, 수술 전부터 퇴원 구역에 이르기까지 원활하게 사용할 수 있는 것이 요구되고 있습니다. 가치 기반 계약 하에 일회용 제품을 세트로 판매하는 공급업체는 가격에 민감한 외래 진료 현장에서 1회당 시술 비용을 절감함으로써 지지를 넓혀가고 있습니다.
호흡기 질환 유병률 증가
만성폐쇄성폐질환(COPD)나 바이러스 감염 후 합병증과 같은 만성 호흡기 질환은 증가 일로를 걷고 있으며, 의료진은 상태의 조기 악화를 감지하기 위해 지속적인 CO2 모니터링 도입을 요구받고 있습니다. 카프노그래피는 저환기를 특정하는 데 있어 맥박 산소 측정기 단독 사용보다 높은 민감도를 보여주고 있으며, 이는 호흡기 병동에서 두 기법을 결합한 프로토콜 도입을 뒷받침하고 있습니다. 수면 검사실에서는 재택 검사를 위한 휴대용 카프노그래프의 도입이 확대되고 있으며, 이는 폐쇄성 수면 무호흡 증후군의 진단 및 치료 개시 속도를 높이는 데 기여하고 있습니다. 공중보건 기관들은 미검출된 야간 저환기와 관련된 재입원율 상승에 대해 경고하고 있으며, 이에 따라 보험사들은 만성 질환 관리 포괄 계약에서 카프노그래피 사용에 대한 보상을 실시했습니다. 이러한 동향은 입원 환경과 재택 환경을 불문하고 카프노그래피 기기 시장의 지속적인 확장을 뒷받침하고 있습니다.
숙련된 호흡치료사 및 마취기술자 부족
2024년, 호흡치료사와 마취기술자의 결원율은 12%를 넘어 사상 최고치를 기록했습니다. 이로 인해 신규 장비 도입이 둔화되고 있습니다. 충분한 전문 지식을 갖추지 못한 시설에서는 복잡한 파형의 이상을 해석하는 데 어려움을 겪고 있어, 첨단 기능이 충분히 활용되지 못하고 임상적 가치 제공이 약화되고 있습니다. 각 벤더사는 학습 곡선을 단축하기 위해 자동 해석 소프트웨어나 대화형 튜토리얼을 제공하며 대응하고 있지만, 도입 교육에는 여전히 시간이 소요되어 조달 주기를 장기화시키고 있습니다. 학술 프로그램에서는 학생 모집을 확대하고 있지만, 교원 부족에 직면해 있어 중기적으로는 인력 부족이 지속될 전망입니다. 그 결과, 일부 병원에서는 인력 배치가 안정될 때까지 카프노그래피 장비 업그레이드를 미루고 있어, 단기적인 카프노그래피 장비 시장의 성장세를 둔화시키고 있습니다.
부문 분석
2025년 카프노그래피 기기 시장에서 독립형 시스템 시장 규모는 3억 4,551만 달러를 차지하여 총 매출의 55.12%에 해당했습니다. 병원에서는 중환자 치료 워크플로우를 지원하는 풀스크린 디스플레이, 파형 저장 기능, 고급 경보 옵션이 중요하게 여겨지고 있습니다. 그러나 경량 배터리 구동 장비가 필요한 응급 의료 서비스, 이송 팀, 치과 클리닉 덕분에 휴대용 기기는 연평균 성장률(CAGR) 7.66%라는 빠른 성장을 이루고 있습니다. 많은 지역에서 응급 의료 서비스 프로토콜에 따라 카프노그래피가 삽관 환자의 표준 생체 신호로 취급되면서, 구급차 대열의 일괄 구매가 촉진되고 있습니다.
기동성에 대한 수요는 고해상도 분석이 필요할 때 핸드헬드 모듈을 도킹할 수 있는 하이브리드형 카트 장착형 솔루션에 대한 수요도 촉진하고 있습니다. 각 제조업체는 구급대원이 도착 전 트리아지를 위해 파형 데이터를 응급실로 스트리밍할 수 있도록 블루투스 및 셀룰러 모뎀을 탑재하고 있습니다. 연결성이 확대됨에 따라 소프트웨어 구독이 제품 수익에서 차지하는 비중이 높아지고 있으며, 공급업체의 인센티브가 기기의 가동 시간과 연동되도록 되어 있습니다. 이러한 생태계 접근 방식 덕분에 중환자 치료 환경에서는 독립형 콘솔이 여전히 필수적이지만, 휴대용 플랫폼은 카프노그래피 기기 시장에서 점유율을 서서히 확대해 나가고 있습니다.
2025년 현재, 사이드스트림 방식 분석기는 61.78%라는 카프노그래피 기기 시장 최대 점유율을 유지하고 있으며, 그 범용성과 기존 모니터와의 호환성 덕분에 지지를 받고 있습니다. 그러나 마이크로스트림 방식 장치는 연평균 성장률(CAGR) 7.92%로 성장하고 있어, 2031년까지 그 격차를 좁힐 것으로 예측됩니다. 이 장치들은 샘플링 유량이 극히 낮기 때문에 데드 스페이스의 영향을 최소화하고, 신생아, 비만 환자, 1회 환기량이 적은 환자에서 정확도를 향상시킵니다. 임상 연구를 통해 다양한 호흡 패턴에서 호기 말 이산화탄소 농도와 동맥혈 PaCO₂ 사이에 뛰어난 상관관계가 확인되어 의료진의 신뢰를 높이고 있습니다.
운영 효율성도 또 다른 장점입니다. 밀폐형 워터 트랩을 통해 필터 교체 빈도를 대폭 줄이고, 막힘으로 인한 경보 피로를 경감시킵니다. 일회용 제품 사용량을 줄임으로써 폐기물 발생도 억제되며, 이는 병원의 지속가능성 요건 하에서 점점 더 중요해지고 있는 조달 기준입니다. 마이크로스트림 센서가 독자 규격 커넥터에서 준표준 커넥터로 전환됨에 따라 가격 차이는 줄어들 것으로 예상되며, 도입이 가속화될 전망입니다. 샘플링 지연을 피하기 위해 기도에 장착하는 큐벳을 선호하는 수술실에서는 메인스트림 기술의 중요성이 앞으로도 지속되겠지만, 그 시장 점유율은 예측 기간 동안 정점을 찍을 것으로 보입니다.
지역별 분석
북미는 의료 종사자들의 조기 채택, 광범위한 보험 환급, 강력한 공급업체의 거점 네트워크에 힘입어 2025년 매출의 42.32%를 차지하며 여전히 최대의 지역 시장으로 남아 있습니다. 연방 정부의 ISO 13485 준수 및 신속한 510(k) 승인 절차 덕분에 제품 개선 시장 출시 기간이 단축되어 국내 제품 포트폴리오가 항상 최신 상태로 유지되고 있습니다. 2024년 마시모와 Philips의 통합과 같이, NomoLine 기술을 다중 매개변수 모니터에 통합한 전략적 상호 운용성 제휴는 의료 서비스 제공업체에게 간소화된 업그레이드 로드맵을 제공합니다.
유럽에서는 엄격한 안전 프로토콜에 기반한 장비 교체 수요로 인해 꾸준한 성장이 예상됩니다. 유럽연합 집행위원회가 2025년에 도입할 공급망 투명성 관련 규정에 따라, 제조업체는 카프노그래피용 일회용 제품의 지속적인 공급을 보장해야 할 의무가 있으며, 이는 견고한 조달 체계 구축을 촉진할 것입니다. 각국의 의료 제도에서는 병상 주변의 복잡성을 최소화하기 위해 카프노그래피, 산소 포화도 측정, 혈역학 측정 기능을 통합한 모니터가 선호되고 있습니다. 한편, 디지털 헬스 관련 시범 사업에 대한 지역적 자금 지원으로 인해 지방 클리닉에서의 클라우드 연결형 카프노그래프 도입이 가속화되고 있습니다.
아시아태평양은 수술 건수 증가, 도시 지역의 병원 건설, 만성 호흡기 질환 유병률 상승에 힘입어 2031년 연평균 성장률(CAGR)이 9.08%로 가장 빠르게 성장하는 지역입니다. 중국과 인도에서 중환자실(ICU) 병상 확충을 지원하는 정부의 이니셔티브는 간접적으로 카프노그래피 기기 시장 수요를 활성화시키고 있습니다. 국가별 규제 일정은 다르지만, 현지 제조 파트너십을 추진함으로써 수입 관세가 인하되어 도입이 가속화되고 있습니다. 호주, 일본, 한국은 여전히 최첨단 기술 시장이며, AI를 활용한 파형 분석이 초기부터 주목을 받고 있습니다. 중동 및 아프리카와 남미는 도입이 늦어지고 있지만, 민관 파트너십을 통해 3차 의료 기관에 최신 중환자 치료 인프라가 구축되는 지역에서는 도입이 점차 증가하고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.08.26According to Mordor Intelligence, the capnography devices market size is expected to grow from USD 626.84 million in 2025 to USD 669.4 million in 2026 and is forecast to reach USD 929.58 million by 2031 at 6.79% CAGR over 2026-2031.
This report Segments the Industry Into by Product (Hand-Held, Stand-Alone), by Technology (Side Stream, Main Stream, Micro Stream), by Application (Critical Care, Sleep Studies, and More), by End-User (Hospitals, Ambulatory Surgical Centers, Other End-Users), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global Capnography Devices Market Trends and Insights
Rising Number of Surgeries Worldwide
Ambulatory surgical centers treated 3.3 million Medicare beneficiaries in 2024, underscoring a systemic shift toward outpatient care where reliable respiratory monitoring is indispensable . Enhanced recovery protocols and increasingly complex minimally invasive techniques demand real-time CO2 measurement to catch hypoventilation before oxygen saturation drops. As more specialties adopt moderate sedation outside the operating room, Capnography devices market adoption widens among gastroenterologists, cardiologists and pain-management teams. Purchasing decisions now prioritize monitors that are portable, battery-powered and Wi-Fi-enabled, allowing seamless use from pre-op to discharge bays. Vendors that bundle disposables under value contracts are gaining traction by lowering per-procedure costs in price-sensitive ambulatory settings.
Growing Prevalence of Respiratory Diseases
Chronic respiratory illnesses such as COPD and post-viral complications continue to rise, pushing healthcare providers to adopt continuous CO2 monitoring for early deterioration detection. Capnography has demonstrated higher sensitivity than pulse oximetry alone in identifying hypoventilation, which is driving protocols that combine both modalities in respiratory wards. Sleep labs increasingly deploy portable capnographs for home-based studies, supporting faster diagnosis and treatment initiation for obstructive sleep apnea. Public-health agencies warn of elevated readmission rates tied to undetected nocturnal hypoventilation, prompting insurers to reimburse capnography use in chronic-care bundles. These dynamics nurture sustained Capnography devices market expansion across in-patient and at-home environments.
Shortage of Skilled Respiratory & Anesthesia Technologists
Vacancy rates for respiratory therapists and anesthesia technologists surpassed 12% in 2024, a record high that slows new-device rollouts. Facilities without sufficient expertise struggle to interpret complex waveform anomalies, under-utilizing advanced functions and weakening the clinical value proposition. Vendors respond with auto-interpretation software and interactive tutorials to shorten learning curves, but onboarding still extends procurement cycles. Academic programs expand enrollment yet face faculty shortages, signalling that labor tightness will persist into the medium term. Consequently, some hospitals defer capnography upgrades until staffing stabilizes, tempering near-term Capnography devices market momentum.
Other drivers and restraints analyzed in the detailed report include:
- Technological Advancements in Capnography
- Strong Professional-Society Recommendations
- High Capital & Disposable Costs of Capnography Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The Capnography devices market size for stand-alone systems accounted for USD 345.51 million in 2025, equivalent to 55.12% of total revenue. Hospitals value their full-screen displays, waveform storage and advanced alarm options that support critical-care workflows. However, hand-held devices are carving out a rapid 7.66% CAGR thanks to emergency medical services, transport teams and dental practices that require light, battery-powered units. In many regions, EMS protocols now treat capnography as a standard vital sign for intubated patients, propelling bulk purchases by ambulance fleets.
Demand for mobility also spurs hybrid cart-mounted solutions that dock hand-held modules when high-resolution analysis is needed. Manufacturers integrate Bluetooth and cellular modems so paramedics can stream waveforms to emergency departments for pre-arrival triage. As connectivity expands, software subscriptions become a rising share of product revenue, aligning vendor incentives with device uptime. This ecosystem approach positions portable platforms to capture incremental Capnography devices market share even while stand-alone consoles remain indispensable for intensive-care environments.
Side-stream analyzers retained the largest Capnography devices market share at 61.78% in 2025, favored for versatility and compatibility with existing monitors. Yet micro-stream units are growing at an 7.92% CAGR and are expected to narrow the gap by 2031. Their ultra-low sampling flow minimizes dead-space impact and improves accuracy in neonates, obese patients and those with low tidal volumes. Clinical studies reveal superior correlation between end-tidal CO2 and arterial PaCO2 across variable breathing patterns, reinforcing clinician confidence.
Operational efficiency is another selling point: closed water traps slash filter changes and reduce alarm fatigue from clogging. Lower disposables usage limits waste generation, an increasingly important procurement criterion under hospital sustainability mandates. As micro-stream sensors transition from proprietary to semi-standard connectors, price premiums are expected to compress, accelerating conversions. Main-stream technology will remain important in operating rooms that prefer airway-attached cuvettes to avoid sampling delays, but its share is likely to plateau over the forecast horizon.
Complete Report Scope:
- By Product
- Hand-held
- Stand-alone
- By Technology
- Side-stream
- Main-stream
- Micro-stream
- By Application
- Critical Care
- Sleep Studies
- Pain Management
- Procedural Sedation
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Other End-Users
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America remained the largest regional contributor with 42.32% of 2025 revenue, buoyed by early clinician adoption, broad reimbursement and a strong supplier footprint. Federal alignment with ISO 13485 and swift 510(k) pathways shorten time-to-market for product enhancements, keeping domestic portfolios current. Strategic interoperability alliances, such as the 2024 Masimo-Philips integration that embedded NomoLine technology into multi-parameter monitors, give providers a simpler upgrade roadmap.
Europe delivers steady, replacement-driven growth anchored in stringent safety protocols. The European Commission's 2025 supply-chain transparency rules compel manufacturers to confirm continuity of capnography disposables, fostering resilient procurement frameworks. National health systems favor integrated monitors that consolidate capnography, oximetry and hemodynamics to minimize bedside clutter. Meanwhile, regional funding for digital health pilots accelerates adoption of cloud-connected capnographs in rural clinics.
Asia-Pacific represents the fastest-growing region with a 9.08% CAGR to 2031, propelled by rising surgical volumes, urban hospital construction and increasing chronic respiratory disease incidence. Government initiatives that subsidize ICU bed expansion in China and India indirectly galvanize Capnography devices market demand. Although country-specific regulatory timelines vary, the push for local manufacturing partnerships is reducing import tariffs and speeding deployments. Australia, Japan and South Korea continue as premium-technology markets where AI-enhanced waveform analysis commands early attention. Middle East & Africa and South America trail in adoption but show upticks where public-private partnerships bring modern critical-care infrastructure to tertiary centers.
- Medtronic
- Koninklijke Philips
- Masimo
- Dragerwerk
- Nihon Kohden
- Beckton Dickinson
- Smiths Medical (Smiths Group)
- Nonin Medical
- SunMed
- Infinium Medical
- Welch Allyn (Hillrom / Baxter)
- DiMedica
- GE Healthcare
- Zoll Medical
- Hamilton Medical
- Mindray
- Teleflex
- Capnomed
- Qinhuangdao Kapunuomaite Medical
- CapnoMedical (CapnoAcademy)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Number Of Surgeries Worldwide
- 4.2.2 Growing Prevalence Of Respiratory Diseases
- 4.2.3 Technological Advancements In Capnography Devices
- 4.2.4 Strong Professional-Society Recommendations
- 4.2.5 Ai-Enabled Waveform Analytics For Early Sepsis Detection
- 4.2.6 Integration Of Capnography Into Remote-Patient-Monitoring Wearables
- 4.3 Market Restraints
- 4.3.1 Shortage Of Skilled Respiratory & Anesthesia Technologists
- 4.3.2 High Capital & Disposable Costs Of Capnography Systems
- 4.3.3 Slow Iso Revision On Microstream Disposables Delays Tenders
- 4.3.4 Limited Neonatal Data On Ultra-Low-Flow Microstream Accuracy
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Hand-held
- 5.1.2 Stand-alone
- 5.2 By Technology
- 5.2.1 Side-stream
- 5.2.2 Main-stream
- 5.2.3 Micro-stream
- 5.3 By Application
- 5.3.1 Critical Care
- 5.3.2 Sleep Studies
- 5.3.3 Pain Management
- 5.3.4 Procedural Sedation
- 5.3.5 Other Applications
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Other End-Users
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Medtronic Plc
- 6.3.2 Koninklijke Philips N.V.
- 6.3.3 Masimo Corporation
- 6.3.4 Dragerwerk AG & Co. KGaA
- 6.3.5 Nihon Kohden Corporation
- 6.3.6 Becton, Dickinson and Company
- 6.3.7 Smiths Medical (Smiths Group)
- 6.3.8 Nonin Medical, Inc.
- 6.3.9 SunMed
- 6.3.10 Infinium Medical, Inc.
- 6.3.11 Welch Allyn (Hillrom / Baxter)
- 6.3.12 DiMedica
- 6.3.13 GE Healthcare
- 6.3.14 Zoll Medical Corporation
- 6.3.15 Hamilton Medical AG
- 6.3.16 Shenzhen Mindray Bio-Medical Electronics
- 6.3.17 Teleflex Inc.
- 6.3.18 Capnomed
- 6.3.19 Qinhuangdao Kapunuomaite Medical
- 6.3.20 CapnoMedical (CapnoAcademy)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment