

|
시장보고서
상품코드
2114557
카테터 유도형 혈전용해 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Catheter-Directed Thrombolysis - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
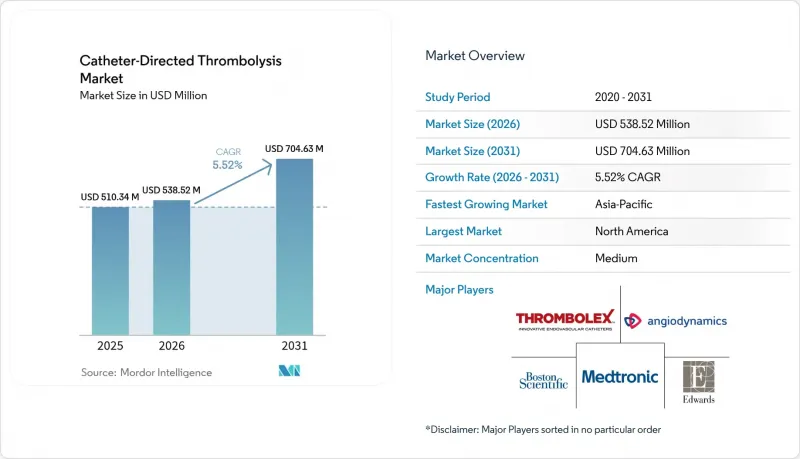
에 의하면, 2026년 카테터 유도형 혈전용해 시장 규모는 5억 3,852만 달러로 추정되고 2025년 5억 1,034만 달러에서 확대해, 2031년에는 7억 463만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 5.52%를 나타낼 것으로 전망됩니다.
본 보고서에서는 업계를 용도(심부정맥혈전증, 폐색전증, 허혈성 뇌졸중, 기타), 최종 사용자(병원, 외래수술센터(ASC)), 지역(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)으로 분류하고 있습니다. 지난 5년간의 데이터와 더불어 향후 5년간 시장 전망도 수록되어 있습니다.
세계의 카테터 유도형 혈전용해 시장 동향 및 인사이트
전 세계 VTE 및 PAD 유병률 증가
VTE 유병률이 상승함에 따라(현재 전 세계 3위의 혈관성 사망 원인이 되고 있음), 전신 출혈의 위험 없이 혈전을 제거할 수 있는 카테터 치료에 대한 수요가 증가하고 있습니다. 선진국 시장의 고령화와 COVID-19로 인한 혈전 형성을 촉진하는 후유증의 장기화가 환자 수를 더욱 증가시키고 있습니다. 병원 감사 결과에 따르면, 급성 뇌졸중 입원 환자 중 VTE 발생률은 0.53%에서 19.8% 사이로 나타나, 이 치료법에는 여전히 큰 성장 여지가 있음을 보여주고 있습니다. PAD는 VTE와 동반되는 경우가 많기 때문에 적응증을 넘나드는 사용이 시술 건수 증가를 뒷받침하며, 카테터 유도형 혈전용해 시장의 지속적인 수익 기반을 공고히 하고 있습니다.
약리-기계적 CDT 시스템의 급속한 보급
약리-기계적 플랫폼은 기계적 파쇄와 국소 약물 전달을 결합하여 용해제 투여량을 줄이고 출혈 위험을 감소시킴으로써, 2024년 카테터 유도 혈전용해 시장에서 55.71%의 점유율을 차지했습니다. 초음파 보조 카테터는 혈전 용해제의 침투를 촉진하고, 흡입 채널이 한 번의 시술로 잔해를 제거함으로써 시술 시간을 단축합니다. 이 기술은 순수 기계적 혈전 제거 장치가 주요 임상시험을 완료할 때까지의 가교 역할을 수행하며, 카테터 유도형 혈전 용해 시장의 중기적인 성장세를 유지하고 있습니다.
Tier 1 센터 이외의 중재적 방사선학(IR) 수용 능력의 한계
2024년 미국의 독립형 중재적 방사선학(IR) 수련 정원 충족률은 58.5%에 그쳐, 시술 건수를 직접적으로 제한하는 인재 파이프라인의 격차가 두드러지게 나타났습니다. 프랑스에서도 유사한 부족 현상이 관찰되었으며, 기계적 혈전 제거술 시행 건수는 이론상 수용 능력인 2만 500건에 비해 7,500건에 그치고 있어, 이는 카테터 유도 혈전용해(CDT)의 병목 현상을 나타내는 지표가 되고 있습니다. 지방 병원이나 신흥 시장에서는 전문의 부족으로 인해 타 병원으로의 의뢰나 치료 지연이 발생하고 있으며, 이는 카테터 유도 혈전용해 시장 전체의 보급을 저해하고 있습니다.
부문별 분석
2025년 카테터 유도형 혈전용해 시장 규모 중 폐색전증이 41.02%를 차지했습니다. 이는 폐색전증이 생명을 위협하는 질환이라는 점과, 전신 요법이 금기인 경우 표적을 좁혀 혈전을 용해하는 방식이 선호된다는 점을 반영한 것입니다. 유럽 34개 의료기관을 대상으로 한 조사에 따르면, 카테터 요법으로 치료받은 고위험 환자의 사망률은 43%였던 반면, 정맥-동맥 ECMO 단독 치료의 경우 57%였습니다. 기계식 시스템 간 시장 점유율 경쟁이 치열한 가운데, 임상 현장에서의 지지가 높아지고 있어 이 시술에 대한 수요는 견조한 추세를 보이고 있습니다.
심부정맥혈전증(DVT)은 가장 빠르게 성장하고 있는 적응증 분야이며, 외래 치료 프로토콜과 정교해진 위험도 계층화를 통해 조기 개입이 촉진됨에 따라 2031년까지 연평균 성장률(CAGR) 6.05%로 확대될 것으로 전망됩니다. 하지 DVT 치료에 대한 보험 적용 범위 확대에 더해, 비만 및 암 유병률의 상승이 맞물리면서 환자 기반이 확대되고 있습니다. 증상의 중증도가 낮기 때문에 외래 진료 환경에서도 치료 건수를 늘릴 수 있게 되어, 카테터 유도형 혈전용해 시장의 지리적 확산을 뒷받침하고 있습니다.
지역별 분석
북미는 광범위한 보험 적용 범위, 성숙한 중재시술(IR) 네트워크, 그리고 끊임없는 임상시험 활동에 힘입어 2025년 카테터 유도형 혈전용해 시장 규모의 41.95%를 차지했습니다. CMS(미국 의료보험서비스센터)는 심혈관 CT에 대한 지급액을 두 배로 늘리고, ASC(외래수술센터(ASC))에서 심장 질환에 대한 보험 환급액을 인상함으로써 구조적으로 이 요법의 도입을 장려하고 있습니다. 그러나 인력 부족으로 인해 교외 및 지방 의료시설로의 확산이 제한되고 있으며, 설치된 설비 용량을 최대한 활용하기 위해 원격 지도 이니셔티브와 허브 앤 스포크(hub-and-spoke)형 의뢰 모델이 추진되고 있습니다.
유럽은 성숙한 시장이지만, 비용 측면의 압박에 직면해 있습니다. 프랑스의 기계적 혈전 제거술이 정체 상태에 있는 상황은 CDT의 보급을 방해하는 시스템의 병목 현상을 여실히 보여주고 있습니다. 의료기기 규정(MDR)에 따른 규제 강화는 규정 준수 비용을 증가시키지만, 궁극적으로는 자금력이 있는 제조업체에 유리하게 작용합니다. Penumbra의 CAVT 플랫폼과 같은 의료기기에 대한 CE 마크 승인은 안정적인 파이프라인 흐름을 뒷받침하고 있지만, 예산 심사로 인해 카테터 유도형 혈전용해 시장 전체에서 프리미엄 가격 책정에 상한선이 설정될 가능성이 있습니다.
아시아태평양은 중국, 일본, 인도의 인프라 확충과 정맥혈전색전증(VTE)에 대한 인식 제고에 힘입어 연평균 성장률(CAGR) 7.1%로 가장 빠르게 성장하고 있는 지역입니다. Inari Medical과의 판매 제휴와 Penumbra가 지정학적 역풍을 인식하고 있다는 점은 기회와 복잡성을 모두 시사합니다. 병원들이 혁신성과 합리적인 가격의 균형을 모색함에 따라, 비용 효율성을 고려한 시스템과 모듈식 가격 체계가 주목받고 있습니다. 인도의 민간 보험 적용 범위 확대와 중국의 국민건강보험 개혁에 힘입어, 이 지역은 카테터 유도형 혈전용해 시장에서 매우 중요한 수요 견인자로서의 입지를 확고히 하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.08.28According to Mordor Intelligence, catheter-directed thrombolysis market size in 2026 is estimated at USD 538.52 million, growing from 2025 value of USD 510.34 million with 2031 projections showing USD 704.63 million, growing at 5.52% CAGR over 2026-2031.

This report Segments the Industry Into Application (Deep Vein Thrombosis, Pulmonary Embolism, Stroke, Other Applications), End-User (Hospitals, Ambulatory Surgical Centers), and Geography (North America, Europe, Asia Pacific, Middle East and Africa, South America). Get Five Years of Historical Data Alongside Five-Year Market Forecasts.
Global Catheter-Directed Thrombolysis Market Trends and Insights
Rising Global Incidence of VTE & PAD
Escalating VTE prevalence-now the third-leading vascular killer worldwide-intensifies demand for catheter interventions that can remove clot burden without systemic bleeding risks. The aging demographic in developed markets and the lingering pro-thrombotic sequelae of COVID-19 amplify case volumes. Hospital audits place VTE incidence between 0.53% and 19.8% among acute stroke admissions, underscoring sizable procedural headroom. Because PAD often coexists with VTE, cross-indication use bolsters procedure growth, anchoring a recurring revenue base for the catheter-directed thrombolysis market.
Rapid Adoption of Pharmacomechanical CDT Systems
Pharmacomechanical platforms held 55.71% of 2024 catheter-directed thrombolysis market share by combining mechanical fragmentation with localized drug delivery, thereby lowering lytic dose and bleeding risk. Ultrasound-assisted catheters enhance penetration of thrombolytics, while aspiration channels evacuate debris in one pass, trimming procedure times. The technology serves as a bridge while purely mechanical thrombectomy devices finalize pivotal trials, sustaining mid-term momentum for the catheter-directed thrombolysis market.
Limited Interventional Radiology Capacity Outside Tier-1 Centers
Only 58.5% of independent IR residency seats were filled in 2024 in the United States, revealing a pipeline gap that directly constrains procedure volume. Comparable shortages in France kept mechanical thrombectomy output at 7,500 cases against theoretical capacity of 20,500, a proxy for CDT bottlenecks. In rural hospitals and emerging markets, lack of specialists forces referrals or delayed therapy, dampening uptake across the catheter-directed thrombolysis market.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Hospital Demand for Day-Case Minimally Invasive PE Care
- AI-Guided Vascular Imaging Improving Procedural Success
- Growing Competition From Mechanical Thrombectomy-Only Devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Pulmonary embolism accounted for 41.02% of 2025 catheter-directed thrombolysis market size, reflecting its life-threatening nature and the preference for targeted clot lysis when systemic options are contraindicated. High-risk cases treated with catheter regimes showed 43% mortality versus 57% with veno-arterial ECMO alone across 34 European centers. Growing clinical endorsement keeps procedure demand steady even as mechanical systems vie for share.
Deep vein thrombosis (DVT) is the fastest-growing application segment, expanding at 6.05% CAGR through 2031 as outpatient protocols and refined risk stratification prompt earlier intervention. Expanded reimbursement for lower-extremity DVT procedures, coupled with rising obesity and cancer prevalence, widens the patient base. Lower acuity allows ambulatory settings to capture incremental volume, aiding geographic penetration of the catheter-directed thrombolysis market.
Complete Report Scope:
- By Application
- Deep Vein Thrombosis
- Pulmonary Embolism
- Ischemic Stroke
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centers
- By Thrombolytic Technique
- Catheter-Directed Thrombolysis (CDT)
- Pharmacomechanical CDT
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 41.95% of 2025 catheter-directed thrombolysis market size, anchored by broad insurance coverage, mature IR networks, and constant clinical trial activity. CMS doubled payments for cardiovascular CT and lifted ASC cardiac reimbursements, structurally rewarding adoption. Yet, workforce shortages limit penetration into suburban and rural centers, prompting tele-mentoring initiatives and hub-and-spoke referral models to maximise installed capacity.
Europe represents a mature but cost-pressured territory. France's mechanical thrombectomy plateau illustrates system bottlenecks that also hamper CDT. Regulatory tightening under the Medical Device Regulation raises compliance costs but ultimately favors well-capitalized manufacturers. CE-mark clearances for devices such as Penumbra's CAVT platform confirm steady pipeline flow, though budget scrutiny could cap premium pricing across the catheter-directed thrombolysis market.
Asia-Pacific is the fastest-growing region at a 7.1% CAGR, fueled by infrastructure upgrades and rising VTE awareness in China, Japan, and India. Inari Medical's distribution alliances and Penumbra's acknowledgment of geopolitical headwinds signal both opportunity and complexity. Value-engineered systems and modular pricing tiers are gaining traction as hospitals balance innovation with affordability. Expanding private insurance coverage in India and universal health reforms in China position the region as a pivotal demand driver for the catheter-directed thrombolysis market.
- AngioDynamics
- BD (Becton Dickinson)
- Boston Scientific
- Edward Lifesciences
- Inari Medical
- Medtronic
- Penumbra
- Teleflex
- iVascular
- Thrombolex
- UN & UP LLC
- EkoSonic (BTG/Boston Scientific)
- Shockwave Medical
- Johnson & Johnson (Cordis)
- Abbott Laboratories
- Terumo Corp.
- Merit Medical Systems
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Incidence Of VTE & PAD
- 4.2.2 Rapid Adoption Of Pharmacomechanical CDT Systems
- 4.2.3 Surge In Hospital Demand For "Day-Case" Minimally-Invasive Pe Care
- 4.2.4 Ai-Guided Vascular Imaging Improving Procedural Success
- 4.2.5 Value-Based Reimbursement Models Favouring Reduced ICU Stay
- 4.2.6 Next-Gen Catheter Coatings Lowering Re-Intervention Rates
- 4.3 Market Restraints
- 4.3.1 High Upfront Device & Drug Costs In Low-Income Settings
- 4.3.2 Limited Interventional Radiology Capacity Outside Tier-1 Centers
- 4.3.3 Bleeding-Risk Concerns For Elderly With Polypharmacy
- 4.3.4 Growing Competition From Mechanical Thrombectomy-Only Devices
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Reimbursement Scenario
5 Market Size & Growth Forecasts
- 5.1 By Application
- 5.1.1 Deep Vein Thrombosis
- 5.1.2 Pulmonary Embolism
- 5.1.3 Ischemic Stroke
- 5.1.4 Other Applications
- 5.2 By End User
- 5.2.1 Hospitals
- 5.2.2 Ambulatory Surgical Centers
- 5.3 By Thrombolytic Technique
- 5.3.1 Catheter-Directed Thrombolysis (CDT)
- 5.3.2 Pharmacomechanical CDT
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, Recent Developments)
- 6.3.1 AngioDynamics
- 6.3.2 BD (Becton Dickinson)
- 6.3.3 Boston Scientific Corp.
- 6.3.4 Edwards Lifesciences
- 6.3.5 Inari Medical
- 6.3.6 Medtronic
- 6.3.7 Penumbra
- 6.3.8 Teleflex
- 6.3.9 iVascular SLU
- 6.3.10 Thrombolex
- 6.3.11 UN & UP LLC
- 6.3.12 EkoSonic (BTG/Boston Scientific)
- 6.3.13 Shockwave Medical
- 6.3.14 Johnson & Johnson (Cordis)
- 6.3.15 Abbott
- 6.3.16 Terumo Corp.
- 6.3.17 Merit Medical
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


