|
시장보고서
상품코드
2114986
폴리비닐 알코올(PVA) 필름 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Polyvinyl Alcohol (PVA) Films - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
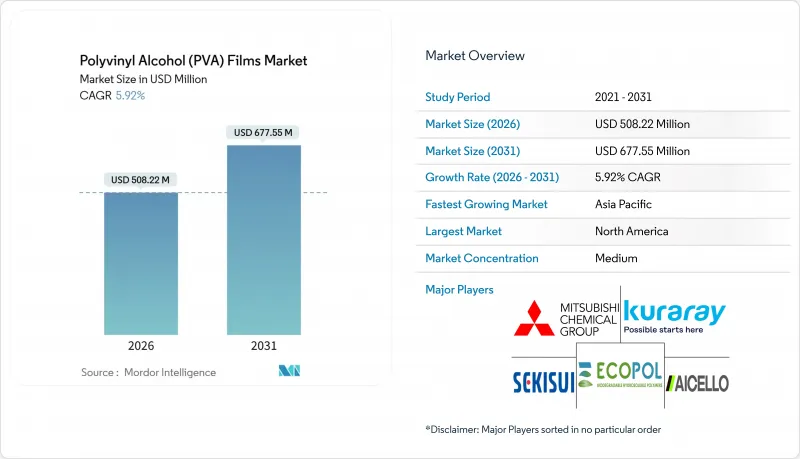
에 의하면, 폴리비닐 알코올 필름 시장 규모는 2026년에 5억 822만 달러로 추정되며, 예측 기간(2026-2031년) CAGR 5.92%로 성장을 지속하여, 2031년까지 6억 7,755만 달러에 이를 전망입니다.
본 보고서는 등급별(완전 가수분해, 부분 가수분해 등), 용도별(일회 투여용 포장, 세탁 가방 등), 최종 사용자 산업별(가정용 및 산업용 세정, 전자 및 광전자 등),지역별(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
전 세계 폴리비닐 알코올(PVA) 필름 시장 동향 및 인사이트
북미 및 유럽에서 냉수 용해형 세제 포드의 급증
15°C 이하에서 완전히 용해되는 이 포드는 2025년에 양 지역에서 세탁량의 60% 이상을 차지할 것으로 예상되는 에너지 절약형 세탁 주기에 부합합니다. 각 배합 제조업체는 EN 13432에 규정된 보다 엄격한 잔류물 제로 기준을 충족하기 위해 PVA의 가수분해율을 87%에서 92% 범위로 조정했습니다. 그 결과, 포드 처리 능력을 분당 1,000개 이상으로 전환한 세제 공장에서의 필름 주문이 급증했습니다. 수용성 세탁용 포드 시장 매출액은 2025년에 3억 3,370만 달러에 달하고, 2034년까지 12억 3,000만 달러를 넘어설 것으로 예측됩니다. 따라서, 이러한 고성장을 달성하고 있는 포드 부문은 예측 기간 동안 폴리비닐 알코올 필름 시장에서 예상되는 최대의 절대 수량 증가를 뒷받침하는 요인이 되고 있습니다.
아시아태평양의 플라스틱 금지 지침이 수용성 농업용 포장의 보급을 가속화
중국의 ‘농업용 필름 관리 조치’에서는 회수 또는 인증된 생분해성이 의무화되어 있으며, 이에 따라 농약 제조업체들은 폴리에틸렌으로 만든 작은 봉지에서 분무 탱크 내에서 용해되는 일회용 PVA 필름 팩으로 전환하고 있습니다. 2023년 4월 이후, 3개 부처가 농작물 재배 성수기에 합동 점검을 시작하면서 규제 집행이 강화되었습니다. 인도의 농약 폐기물 관련 규정도 유사한 입장을 보이며, 비워진 용기를 식품과 접촉하는 용도로 재사용하는 것을 금지하고 있습니다. 이러한 정책들이 맞물려 아시아태평양이 폴리비닐 알코올 필름 시장에서 가장 빠르게 성장하는 지역이 된 이유를 설명해 줍니다.
비닐아세테이트 모노머(VAM) 가격 변동
2025년, 에틸렌과 아세트산 가격의 급등에 따라 VAM 현물 가격은 톤당 100달러 상승하여 쿠라레와 미쓰비시 화학 등 통합형 제조업체에 명확한 마진 헤지를 가져다주었습니다. 반면, 라틴아메리카의 독립 가공업체들은 가격 급등 기간 중 수입 VAM이 중국의 접착제 부문으로 전용됨에 따라 200-300 베이시스 포인트의 마진 축소가 확인되었습니다. 장기 계약 및 자사 VAM 공장에 대한 직접 투자가 여전히 유일하고 신뢰할 수 있는 완충책으로 작용하고 있습니다.
부문별 분석
2025년, 부분 가수분해 필름은 폴리비닐 알코올 필름 시장의 54.19%를 차지하고, 87-92%의 가수분해 범위가 빠른 용해성과 뛰어난 인장 강도를 제공하기 때문에 2031년까지 주요 수익원으로 남아 있을 것으로 전망됩니다. 이 등급의 제품은 20°C에서 30-90초 만에 용해되므로, 분당 1,000개 이상의 속도로 작동하는 고속 포드 충전기의 사용이 가능합니다. 가수분해도가 98%를 초과하는 완전 가수분해 필름은 산소 차단값이 0.02 cc m2일 미만이며, 백플레인의 수명 연장에 기여하는 광학 편광판으로서 우수하지만, 냉수에서 분해 속도가 너무 빠르기 때문에 세제 용도에는 적합하지 않습니다. 에틸렌이 그래프트된 코폴리머 등급은 열 밀봉 강도와 내습성을 향상시켜 용해 지연이 요구되는 세탁용 봉투나 자수용 안감 용도로 사용됨에 따라, 2031년까지 6.50%의 성장이 예상됩니다. 특수한 저점도 및 고점도 등급은 섬유 사이즈 가공 및 접착 테이프용으로 제공되며, 안정적이긴 하지만 완만한 성장세를 보이고 있습니다.
등급별 폴리비닐 알코올 필름 시장 점유율은 부분 가수분해에 의한 높은 범용성을 여실히 보여주고 있습니다. 폴리바사는 가수분해도를 90%로 높이고 인라인 필름 템퍼링을 병용함으로써 캐스팅 속도를 60% 향상시켰습니다. 이를 통해 취성 현상을 30% 줄이고 플랜트 가동률을 85%로 끌어올렸습니다. 미쓰비시 화학은 TV 패널의 대형화에 대응하여 2027년도까지 연간 1억 5,400만 m²를 목표로 완전 가수분해 제품의 생산 능력을 지속적으로 확대하고 있으며, 포드 제품에 비해 성장 속도는 둔화되고 있지만 확고한 입지를 구축하고 있습니다.
지역별 분석
북미는 포드의 높은 보급률과 멕시코의 디스플레이 조립 제조업체를 대상으로 한 편광판 수출 덕분에 2025년에는 매출의 35.87%를 차지했습니다. 한편, 아시아태평양은 중국의 농업용 필름 회수 제도와 인도의 2선 도시에서의 포드 판매망 확대를 배경으로 연평균 성장률(CAGR) 6.88%를 기록하며 성장세를 이어가고 있습니다. 유럽은 유럽 그린딜에 따라 이탈리아,독일, 튀르키예에서 순환형 섬유 사이즈 가공 공장이 잇달아 설립됨에 따라 5.5%의 성장률을 기록하고 있습니다. 남미는 브라질의 세제 시장 변화와 함께 5.2%의 성장률을 보이고 있으며, 중동 및 아프리카는 농업용 소포장 봉투의 도입이 아직 초기 단계에 머물러 있어 4.8%의 성장률을 기록하고 있습니다.
2023년, 중국의 포드 소비량은 약 30% 증가했으며, 이에 따라 안후이 완웨이는 국내 및 수출 수주를 확보하기 위해 바이오 PVA 생산 라인 가동을 서둘러 추진하고 있습니다. 일본의 쿠라레와 미쓰비시 화학이 광학 필름 수출을 주도하고 있으며, 후자는 2027년 하반기까지 오가키에 연간 2,700만 m² 규모의 생산 라인을 증설할 예정입니다. 인도에서는 용기 재사용을 금지하는 농약 폐기물 규제가 시행되고 있으며, 이것이 수용성 소포에 대한 안정적인 수요를 견인하고 있습니다. 한국의 스미토모 화학은 미니 LED의 성장세를 타기 위해 2025년에 편광판 생산 능력을 25% 증강했습니다. 북미에서는 이미 가구의 40% 이상에 보급된 세탁용 포드보다 헬스케어용 필름 분야에서 더 큰 성장이 예상됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.08.26According to Mordor Intelligence, the polyvinyl alcohol films market size is estimated at USD 508.22 million in 2026, and is expected to reach USD 677.55 million by 2031, at a CAGR of 5.92% during the forecast period (2026-2031).
This report is Segmented by Grade Type (Fully Hydrolyzed, Partially Hydrolyzed, and More), Application (Unit-Dose Packaging, Laundry Bags, and More), End-User Industry (Household and Industrial Cleaning, Electronics and Optoelectronics, and More), and Geography (Asia-Pacific, North America, Europe, South America, and the Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Polyvinyl Alcohol (PVA) Films Market Trends and Insights
Surge in Cold-Water-Soluble Detergent Pods Across North America and Europe
Pods that dissolve completely below 15°C meet energy-saving wash cycles that represented more than 60% of loads in both regions during 2025. Formulators aligned PVA hydrolysis between 87% and 92% to meet the stricter residue-free benchmarks embedded in EN 13432, prompting a surge in film call-offs from detergent plants that switched pod throughput to over 1,000 units per minute. Market revenue for water-soluble laundry pods climbed to USD 333.7 million in 2025 and is projected to top USD 1.23 billion by 2034. The high-growth pod segment, therefore, underpins the largest absolute volume gain expected in the polyvinyl alcohol films market over the outlook period.
Asia-Pacific Plastic-Ban Directives Accelerating Water-Soluble Agro-Packs
China's Agricultural Film Management Measures require recovery or certified biodegradation, moving pesticide formulators away from polyethylene sachets toward unit-dose PVA film packs that dissolve in spray tanks. Enforcement intensified after April 2023 when three ministries launched joint inspections during peak planting seasons . India's pesticide-waste rules echo this stance, disallowing reuse of emptied containers for any food contact. Together, these policies explain why Asia-Pacific is the fastest advancing geography in the polyvinyl alcohol films market.
Volatility in Vinyl-Acetate-Monomer Pricing
Spot VAM rose by USD 100 per ton in 2025 after ethylene and acetic acid rallied, handing integrated producers such as Kuraray and Mitsubishi Chemical a clear margin hedge. Independent converters in Latin America documented 200-300 basis-point margin erosion because imported VAM was rerouted to China's adhesives sector during the spike. Long-term contracts and direct investment in captive VAM units remain the only credible buffer.
Other drivers and restraints analyzed in the detailed report include:
- Expanded Optical-Grade Polarizer Production for OLED and Mini-LED Displays
- Growing Demand for Unit-Dose Detergent Packaging in Emerging Economies
- Higher Cost and Limited Heat Resistance Versus PE and PET Films
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Partially hydrolyzed films supplied 54.19% of the polyvinyl alcohol films market in 2025 and are forecast to remain the dominant revenue stream through 2031 because the 87-92% hydrolysis window delivers quick dissolution and robust tensile strength. These grades dissolve in 30-90 seconds at 20°C, enabling high-speed pod fillers that run beyond 1,000 units per minute. Fully hydrolyzed films, with hydrolysis above 98%, excel as optical polarizers where oxygen barrier values below 0.02 cc m2 day align with long back-plane service life, yet they break down too rapidly in cold water for detergent use. Copolymer grades that graft ethylene improve hot-seal strength and moisture resistance, growing at 6.50% to 2031 by serving laundry bags and embroidery backing where delayed dissolution is desired. Specialty low-viscosity and high-viscosity grades cater to textile sizing and adhesive tapes, posting stable but modest expansion.
Polyvinyl alcohol films market share at the grade level illustrates the versatility premium of partial hydrolysis. Polyva upgraded casting speed by 60% when it refined hydrolysis to 90% alongside in-line film tempering, cutting brittleness events by 30% and lifting plant utilization to 85%. Mitsubishi Chemical continues to lift fully hydrolyzed capacity, targeting 154 million m2 per year by fiscal 2027 in response to television panel enlargement, thereby securing its foothold despite slower growth relative to pods.
Complete Report Scope:
- By Grade Type
- Fully Hydrolyzed
- Partially Hydrolyzed
- Substituted / Copolymer PVA
- Other Grades
- By Application
- Unit-Dose Packaging
- Detergents
- Agrochemicals
- Disinfectants
- Other Unit Dose Packaging
- Laundry Bags
- Embroidery
- Polarizing Panels
- Other Applications(Medical and Healthcare,Food and Beverage Packaging)
- Unit-Dose Packaging
- By End-user Industry
- Household and Industrial Cleaning
- Agriculture
- Electronics and Optoelectronics
- Healthcare and Pharmaceuticals
- Textile and Embroidery
- Food and Beverage
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
North America commanded 35.87% revenue in 2025 through high pod penetration and polarizer exports to Mexico based display assemblers. Asia-Pacific, however, gathers velocity at a 6.88% CAGR given China's agro-film recovery laws and India's widening retail network that sells pods in tier-two cities. Europe advances 5.5% as circular textile sizing plants spring up in Italy, Germany, and Turkey under the European Green Deal. South America grows at 5.2% with Brazil's detergent shift, and the Middle East & Africa hit 4.8% where agricultural sachets are early in the adoption curve.
China's pod consumption climbed about 30% in 2023, prompting Anhui Wanwei to fast-track a bio-PVA line that will secure both domestic and export orders. Japan's Kuraray and Mitsubishi Chemical dominate optical film exports, with the latter adding a 27 million m2 annual line at Ogaki by H2 2027. India leverages pesticide-waste rules that forbid container reuse, driving volume-secure demand for water-soluble sachets. South Korea's Sumitomo Chemical raised polarizer capacity by 25% in 2025 to ride mini-LED momentum. North America sees incremental upside from healthcare films rather than laundry pods, whose penetration already exceeds 40% of households.
- Aicello Corporation
- Amtrex Nature Care Pvt. Ltd.
- Anhui Dingzheng Packing Material Co., Ltd.
- Arrow Coated Products Ltd.
- Cangzhou Water Supply and Drainage Group Co., Ltd.
- Cortec Corporation
- Ecopol SpA
- Guangzhou Plastic Industrial Group Co., Ltd.
- Jiangmen Proudly Water-Soluble Plastic Co., Ltd.
- Joyforce Chemical Industrial Co., Ltd.
- Kuraray Co., Ltd.
- LG Chem
- Mitsubishi Chemical Group Corporation
- Nippon Chemical Industrial CO., LTD.
- Nitto Denko Corporation
- Noble Industries
- SEKISUI CHEMICAL CO., LTD.
- Sumitomo Chemical Co., Ltd.
- UNITIKA LTD.
- WATERSOL
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Cold-Water Soluble Detergent Pods across North America and Europe
- 4.2.2 Asia-Pacific Plastic-Ban Directives Accelerating Water-Soluble Agrochemical Packs
- 4.2.3 Growing Demand for Detergent Packaging
- 4.2.4 Government Policies and Shift Toward Eco-friendly Materials
- 4.2.5 Increasing Green-Deal Incentives for Biodegradable Food Packaging
- 4.3 Market Restraints
- 4.3.1 Volatility in Vinyl Acetate Monomer (VAM) Pricing
- 4.3.2 Higher Cost and Limited Applications
- 4.3.3 Availability of Suitable Substitutes
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Grade Type
- 5.1.1 Fully Hydrolyzed
- 5.1.2 Partially Hydrolyzed
- 5.1.3 Substituted / Copolymer PVA
- 5.1.4 Other Grades
- 5.2 By Application
- 5.2.1 Unit-Dose Packaging
- 5.2.1.1 Detergents
- 5.2.1.2 Agrochemicals
- 5.2.1.3 Disinfectants
- 5.2.1.4 Other Unit Dose Packaging
- 5.2.2 Laundry Bags
- 5.2.3 Embroidery
- 5.2.4 Polarizing Panels
- 5.2.5 Other Applications(Medical and Healthcare,Food and Beverage Packaging)
- 5.2.1 Unit-Dose Packaging
- 5.3 By End-user Industry
- 5.3.1 Household and Industrial Cleaning
- 5.3.2 Agriculture
- 5.3.3 Electronics and Optoelectronics
- 5.3.4 Healthcare and Pharmaceuticals
- 5.3.5 Textile and Embroidery
- 5.3.6 Food and Beverage
- 5.3.7 Others
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Aicello Corporation
- 6.4.2 Amtrex Nature Care Pvt. Ltd.
- 6.4.3 Anhui Dingzheng Packing Material Co., Ltd.
- 6.4.4 Arrow Coated Products Ltd.
- 6.4.5 Cangzhou Water Supply and Drainage Group Co., Ltd.
- 6.4.6 Cortec Corporation
- 6.4.7 Ecopol SpA
- 6.4.8 Guangzhou Plastic Industrial Group Co., Ltd.
- 6.4.9 Jiangmen Proudly Water-Soluble Plastic Co., Ltd.
- 6.4.10 Joyforce Chemical Industrial Co., Ltd.
- 6.4.11 Kuraray Co., Ltd.
- 6.4.12 LG Chem
- 6.4.13 Mitsubishi Chemical Group Corporation
- 6.4.14 Nippon Chemical Industrial CO., LTD.
- 6.4.15 Nitto Denko Corporation
- 6.4.16 Noble Industries
- 6.4.17 SEKISUI CHEMICAL CO., LTD.
- 6.4.18 Sumitomo Chemical Co., Ltd.
- 6.4.19 UNITIKA LTD.
- 6.4.20 WATERSOL
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment