|
시장보고서
상품코드
2122374
폴리비닐 알코올 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Polyvinyl Alcohol - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
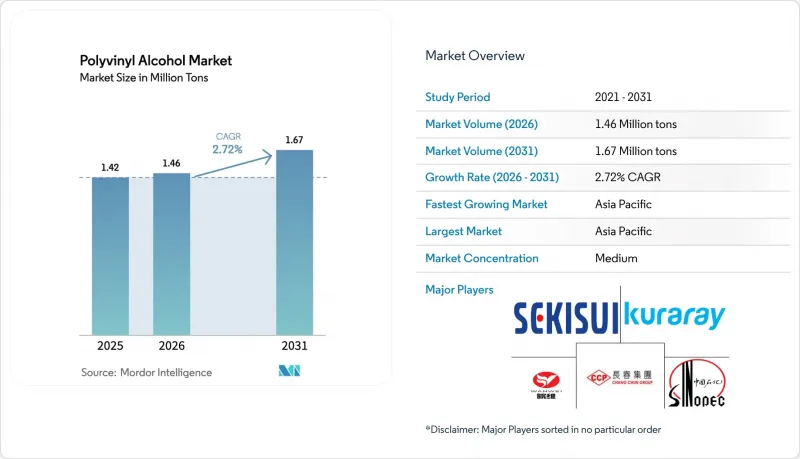
에 의하면, 폴리비닐 알코올 시장 규모는 2025년 142만 톤, 2026년 146만 톤에서 2031년까지 167만 톤으로 확대될 것으로 예측되며, 2026-2031년 연평균 복합 성장률(CAGR)은 2.72%를 기록할 전망입니다.
본 보고서는 등급별(부분 가수분해, 완전 가수분해, 기타),형태별(분말, 과립, 기타), 용도별(중합 첨가제, 폴리비닐부티랄, 기타), 최종 이용 산업별(식품 포장, 제지, 기타), 지역별(아시아태평양, 북미, 기타)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시되어 있습니다.
전 세계 폴리비닐 알코올 시장 동향 및 인사이트
식품 포장 산업 수요 증가
1회분 용량의 편리한 포장 형태가 소비자의 구매 선택을 새롭게 변화시켰습니다. 식기세척기용 정제 포장, 커피 포드, 소스 소포장은 2025년 최종 용도 출하량의 33.67%를 차지했습니다. 2024년 미국 식품의약국(FDA)이 식품 접촉에 관한 프로토콜을 개정함에 따라, 항균성 나노 입자가 함유된 PVA 필름의 승인이 신속해졌으며, 2025년에는 FDA에 제출된 신청 건수가 22% 증가했습니다. 일본 후생노동성은 승인까지 소요되는 기간을 절반으로 단축하여, 도시락 용기 라이너 및 인스턴트 면 포장 필름에 대한 국내 채택을 촉진했습니다. 독일과 네덜란드의 식료품 소매업체들은 싱크대에서 녹는 포장에 대해 소비자들이 12-15%의 프리미엄 가격을 지불하고 있다고 보고하여, 가격 탄력성이 있는 수요가 입증되었습니다.
건축용 실란트 및 모르타르에서의 사용량 증가
부분 가수분해 PVA는 타일용 접착제 및 셀프 레벨링 재료에서 유변학적 특성과 내균열성을 향상시킵니다. 중국이 2024년에 공공 인프라용으로 정한 저VOC 규제로 인해, 2025년에는 건설용 PVA 수요가 9% 증가했습니다. 인도의 저소득층 주택 건설 촉진 정책에서는 철근 비용을 절감하기 위해 PVA 섬유가 채택되었습니다. 한편, 중동의 메가 프로젝트에서는 50℃에서 15℃에 이르는 일교차를 견딜 수 있는 PVA 개질 실란트가 지정되었습니다.
변동이 심한 비닐아세테이트 모노머(VAM) 가격으로 인한 이익률 압박
2025년, VAM 현물 가격은 18% 변동하여 비통합형 생산자의 매출 총이익률을 12-15% 끌어내렸고, 일시적인 가동 중단을 초래했습니다. 한편, 중국의 통합형 기업들은 톤당 180달러의 비용 우위를 누리며 수출을 23% 끌어올렸습니다.
부문별 분석
2025년에는 부분 가수분해 제품이 수량의 37.51%를 차지했으며, 섬유 제조업체들이 냉수 및 온수 모두에 용해되는 특성을 선호함에 따라 2031년까지 3.01%의 성장률을 보였습니다. 완전 가수분해 제품은 세제 포드용 필름을 뒷받침하고 있으며, 가수분해율 98.5%인 쿠라레사의 ‘POVAL 205’가 2025년에 기준 등급이 되었습니다. 특수 용도의 혁신 제품으로는 고속 잉크젯 코팅용 초저발포 유형, 재사용형 보냉 팩용 열가역성 젤 등이 있습니다. 이러한 첨단 등급 제품들은 전반적으로 평균 판매 가격을 끌어올려 이익률을 안정시키고 있습니다.
각 제조업체는 점도, 분자량, 관능기를 조정하고 있습니다. 미쓰비시화학은 2025년, 결함이 없는 광학 필름 코팅을 실현하기 위해 표면 장력이 28다인/cm인 PVA를 출시했습니다. 세키스이 화학 공업의 열가역성 겔은 60℃ 이상에서 액화되었습니다가 이후 재고화되기 때문에 데이터센터의 열 완충재로 새로운 용도가 발견되고 있습니다. 이러한 개발을 통해 고객 충성도가 유지되고, 폴리비닐알코올 시장이 부가가치가 높은 틈새 시장으로 전환되는 기반이 마련되었습니다.
2025년에는 접착제 및 섬유 부문의 현장 용해 수요에 힘입어 분말 제품의 점유율은 54.36%를 유지했습니다. 한편, 포드 및 농약용 소포장에 대한 수요가 확대됨에 따라 수용성 필름은 2031년까지 연평균 성장률(CAGR) 3.41%를 기록할 전망입니다. 일본 VAM & Poval의 2025년산 3층 필름은 냉수에서의 용해 속도가 30% 향상되어 세제 공장의 사이클 타임을 단축했습니다. 과립은 분진이 발생하지 않는 건설 현장에서 활용되며, 섬유는 콘크리트 및 아스팔트 보강에 사용되고 있습니다. 쿠라레의 ‘쿠라론’ 섬유는 일본 리니어 모터카용 터널의 분사 콘크리트에서 강재를 대체하여 무게를 40% 줄였습니다.
필름 제조업체는 인장 강도와 용해성의 균형을 맞추기 위해 가소제의 배합 비율을 조정하고 있습니다. 드럼 건조를 통해 제조되는 플레이크 형태의 제품은 제지 공장에서의 자동 계량에 적합합니다. 따라서 폴리비닐 알코올 시장에서 물리적 형태의 선택이 적용 가능한 용도와 가격 결정력을 좌우하게 됩니다.
지역별 분석
아시아태평양은 2025년에 수량 기준으로 47.72%를 차지하며 시장을 주도하고 있으며, 연평균 성장률(CAGR) 2.92%로 확대될 것으로 예측됩니다. 중국의 85만 톤에 달하는 통합 생산 능력은 에틸렌계 제조 공정에 비해 톤당 180달러의 비용 우위를 가지고 있어, 적극적인 상품 가격 책정이 가능합니다. 인도에서는 주택 건설 및 섬유 사이징제 용도로 인해 2025년 수요가 급증했습니다. 일본은 광학 필름용 고점도 등급 제품을 수출했습니다. 동남아시아에서는 다국적 기업들이 생산을 현지화함에 따라 세제 포드 수요가 증가했습니다.
북미에서는 FDA 승인 절차의 효율화로 필름 제품의 승인이 가속화되었으며, Procter & Gamble사의 포드 전환이 수요를 끌어올렸습니다. 캐나다에서는 염분을 함유한 토양에서 발아율이 10% 향상되는 PVA 종자 코팅에 대한 검사가 진행되었습니다. 멕시코에서는 니어쇼어링에 따른 건설 수요와 연동하여 PVA 개질 모르타르가 완만한 성장세를 보였습니다.
유럽에서는 2025년 폐기물 규정에 따라 생분해성 필름이 우선적으로 채택되고 있으며, 이는 일본으로부터의 수입 증가를 뒷받침하고 있습니다. 남미, 중동 및 아프리카에서는 인프라 정비 및 농업 부문에서의 검사가 잇따르는 가운데 수요가 견조한 흐름을 보였습니다. 페트로브라스는 PVA를 배합한 시추 유체 첨가제에 대한 검사를 실시했으며, 사우디아라비아의 NEOM 프로젝트에서는 유리 파사드용 PVA 실란트가 지정되는 등, 지역별로 새로운 틈새 시장이 부각되고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트의 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.04According to Mordor Intelligence, the polyvinyl alcohol market size is projected to expand from 1.42 million tons in 2025 and 1.46 million tons in 2026 to 1.67 million tons by 2031, registering a CAGR of 2.72% between 2026 to 2031.
This report is Segmented by Grade (Partially Hydrolyzed, Fully Hydrolyzed, and More), Form (Powder, Granules, and More), Application (Polymerization Additives, Polyvinyl Butyral, and More), End-Use Industry (Food Packaging, Paper Manufacturing, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Polyvinyl Alcohol Market Trends and Insights
Growing Demand from Food-Packaging Industry
Single-serve convenience formats reshaped purchasing choices. Dishwasher-tablet wraps, coffee pods, and sauce sachets jointly held 33.67% of end-use volume in 2025. Updated U.S. FDA food-contact protocols in 2024 fast-tracked approvals for PVA films with antimicrobial nanoparticles, lifting agency submissions by 22% in 2025. Japan's health ministry halved approval lead times, spurring domestic uptake in bento-box liners and noodle-packet films . German and Dutch grocers reported a 12-15% consumer premium for dissolve-in-sink packaging, validating price-elastic demand.
Increasing Usage in Construction Sealants and Mortar
Partially hydrolyzed PVA improves rheology and crack resistance in tile adhesives and self-leveling compounds. China's 2024 low-VOC mandate for public infrastructure lifted construction-grade PVA offtake 9% in 2025. India's affordable-housing drive adopted PVA fibers to cut rebar costs, while Middle Eastern mega-projects specified PVA-modified sealants able to absorb daily thermal swings from 50 °C to 15 °C.
Volatile Vinyl-Acetate-Monomer Prices Squeezing Margins
Spot VAM swung 18% in 2025, narrowing non-integrated producers' gross margins by 12-15% and prompting temporary shutdowns. Integrated Chinese firms enjoyed a USD 180 per-ton cost edge, boosting exports 23%.
Other drivers and restraints analyzed in the detailed report include:
- Surging Adoption in Detergent Pods and Water-Soluble Films
- Expansion of PVA-Based Emulsion Polymers for Water-Borne Coatings
- Availability of Bio-Based and Petro-Based Substitutes (PLA, EVOH)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Partially hydrolyzed captured 37.51% of 2025 volume, expanding at 3.01% through 2031 as textile mills favored its dual cold- and hot-water solubility. Fully hydrolyzed variants underpin detergent-pod films; Kuraray's POVAL 205 with 98.5% hydrolysis became the reference grade in 2025. Specialty innovations include super-low-foaming types for high-speed inkjet coating and thermally reversible gels for reusable cold packs. Collectively, advanced grades increase average selling prices and stabilize margins.
Manufacturers tailor viscosity, molecular weight, and functional groups. Mitsubishi Chemical launched a PVA with surface tension of 28 dynes/cm in 2025 for defect-free optical-film coating. Sekisui's thermally reversible gels liquefy above 60 °C then resolidify, finding new use in data-center thermal buffers. These developments maintain customer lock-in and underpin the polyvinyl alcohol market's shift toward value-added niches.
Powder retained 54.36% share in 2025, driven by on-site dissolution needs in adhesives and textiles. Water-soluble films, however, will post a 3.41% CAGR to 2031 as pod and agrochemical-sachet demand widens. Japan VAM & Poval's 2025 tri-layer film dissolved 30% faster in cold water, cutting cycle times for detergent plants. Granules serve dust-free construction job sites, while fibers reinforce concrete and asphalt; Kuraray's Kuralon fiber replaced steel in Japan's maglev tunnel shotcrete, lowering weight 40%.
Film producers manage plasticizer ratios for balance between tensile strength and dissolution. Flake forms, produced via drum drying, cater to automated dosing in paper mills. Physical format choice therefore dictates reachable applications and pricing power within the polyvinyl alcohol market.
Complete Report Scope:
- By Grade
- Partially Hydrolyzed
- Fully Hydrolyzed
- Sub-Partially Hydrolyzed
- Low-Foaming Grades
- Other Grades (Tactified Grades, Fine Particle Grades)
- By Form
- Powder
- Granules
- Flakes
- Water-Soluble Films
- Fibers
- By Application
- Polymerization Additives
- Polyvinyl Butyral
- Adhesives
- Textile
- Paper Pulp and Coating
- Developing Application
- Other Applications
- By End-use Industry
- Food Packaging
- Paper Manufacturing
- Construction
- Electronics
- Textile
- Other End-use Industries (Detergent, Agrochemicals, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- Qatar
- United Arab Emirates
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated with 47.72% volume in 2025 and is forecast to expand at 2.92% CAGR. China's 850,000-ton integrated capacity enjoys USD 180/t cost advantages vs. ethylene routes, allowing aggressive commodity pricing. India's 2025 offtake jumped due to housing construction and textile sizing. Japan exported high-viscosity grades for optical films. Southeast Asia posted detergent-pod demand growth as multinationals localized production.
In North America, streamlined FDA clearances accelerated film approvals, and Procter & Gamble's pod shift added demand. Canada piloted PVA seed coatings with 10% germination uplift in saline soils. Mexico enjoyed moderate growth in PVA-modified mortars tied to near-shoring construction.
Europe is prioritizing biodegradable films under its 2025 waste regulation, driving import growth from Japan. South America and the Middle East and Africa commanded demand as infrastructure and agricultural trials multiply. Petrobras tested PVA drilling-fluid additives, while Saudi Arabia's NEOM project specified PVA sealants for glass facades, underscoring emerging regional niches.
- Anhui Wanwei Updated High Tech Material Industry Co Ltd
- Astrra Chemicals
- Chang Chun Group
- JAPAN VAM & POVAL CO.,LTD.
- KURARAY CO., LTD.
- Mitsubishi Chemical Group Corporation
- Nippon Chemical Industrial CO., LTD.
- OCI COMPANY Ltd
- Polysciences
- SEKISUI CHEMICAL CO., LTD.
- Shandong Tiancheng Chemical Co., Ltd.
- Shuangxin PVA Tech Co., Ltd.
- Sinopec Sichuan Vinylon Works
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Demand from Food-Packaging Industry
- 4.2.2 Increasing Usage in Construction Sealants and Mortar
- 4.2.3 Surging Adoption in Detergent Pods and Water-Soluble Films
- 4.2.4 Expansion of PVA-Based Emulsion Polymers for Water-Borne Coatings
- 4.2.5 Emergence of PVA-Based Biodegradable Agricultural Films
- 4.3 Market Restraints
- 4.3.1 Volatile Vinyl-Acetate-Monomer (VAM) Prices Squeezing Margins
- 4.3.2 Availability of Bio-Based and Petro-Based Substitutes (PLA, EVOH)
- 4.3.3 Limited Recycling Infrastructure for PVA Films in Emerging Economies
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Grade
- 5.1.1 Partially Hydrolyzed
- 5.1.2 Fully Hydrolyzed
- 5.1.3 Sub-Partially Hydrolyzed
- 5.1.4 Low-Foaming Grades
- 5.1.5 Other Grades (Tactified Grades, Fine Particle Grades)
- 5.2 By Form
- 5.2.1 Powder
- 5.2.2 Granules
- 5.2.3 Flakes
- 5.2.4 Water-Soluble Films
- 5.2.5 Fibers
- 5.3 By Application
- 5.3.1 Polymerization Additives
- 5.3.2 Polyvinyl Butyral
- 5.3.3 Adhesives
- 5.3.4 Textile
- 5.3.5 Paper Pulp and Coating
- 5.3.6 Developing Application
- 5.3.7 Other Applications
- 5.4 By End-use Industry
- 5.4.1 Food Packaging
- 5.4.2 Paper Manufacturing
- 5.4.3 Construction
- 5.4.4 Electronics
- 5.4.5 Textile
- 5.4.6 Other End-use Industries (Detergent, Agrochemicals, etc.)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Malaysia
- 5.5.1.6 Thailand
- 5.5.1.7 Indonesia
- 5.5.1.8 Vietnam
- 5.5.1.9 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 Italy
- 5.5.3.4 France
- 5.5.3.5 Spain
- 5.5.3.6 NORDIC Countries
- 5.5.3.7 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Colombia
- 5.5.4.4 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 Qatar
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 Anhui Wanwei Updated High Tech Material Industry Co Ltd
- 6.4.2 Astrra Chemicals
- 6.4.3 Chang Chun Group
- 6.4.4 JAPAN VAM & POVAL CO.,LTD.
- 6.4.5 KURARAY CO., LTD.
- 6.4.6 Mitsubishi Chemical Group Corporation
- 6.4.7 Nippon Chemical Industrial CO., LTD.
- 6.4.8 OCI COMPANY Ltd
- 6.4.9 Polysciences
- 6.4.10 SEKISUI CHEMICAL CO., LTD.
- 6.4.11 Shandong Tiancheng Chemical Co., Ltd.
- 6.4.12 Shuangxin PVA Tech Co., Ltd.
- 6.4.13 Sinopec Sichuan Vinylon Works
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Innovations in Polyvinyl Alcohol for Packaging and Medical