

|
시장보고서
상품코드
2116831
유럽의 온라인 데이트 서비스 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Online Dating Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
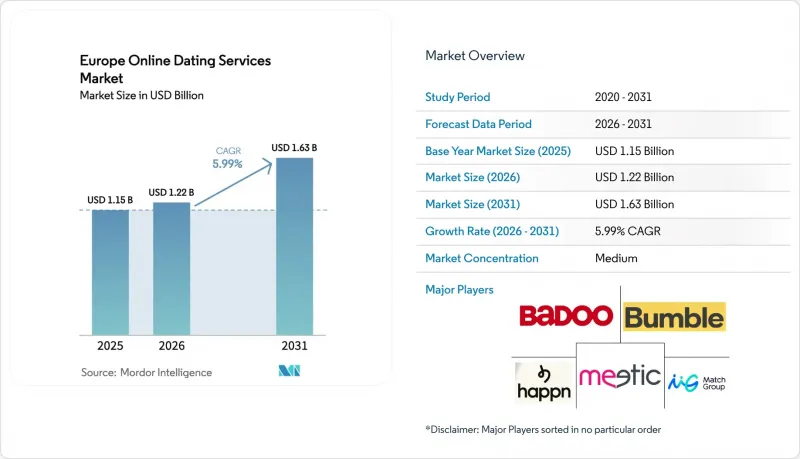
유럽의 온라인 데이트 서비스 시장 규모는 2025년에 11억 5,000만 달러로 평가되었고, 2026년 12억 2,000만 달러에서 2031년까지 16억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 5.99%를 나타낼 전망입니다.
본 보고서는 유형별(무료 온라인 데이트, 유료 온라인 데이트), 기기 플랫폼별(모바일 앱 등), 연령대별(18-24세, 25-34세 등), 교제 목적별(캐주얼 데이트, 장기적인 교제 등), 성적 지향별(이성애자용 플랫폼, LGBTQ+용 플랫폼), 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽의 온라인 데이트 서비스 시장 동향 및 인사이트
디지털 우선의 교류를 추구하는 밀레니얼 세대 및 Z세대 사용자의 급증
밀레니얼 세대 및 Z세대는 데이트 앱을 단순한 부가적인 경험이 아닌 주요 사회 인프라로 인식하고 있습니다. 유로스타트(Eurostat) 보고서에 따르면, 2024년 16-29세 인터넷 이용률은 97%에 달했으며, 이 중 83%가 소셜 네트워크를 적극적으로 이용하고 있습니다. Ofcom의 조사에 따르면, 2024년 5월 기준 영국 18-24세 사용자의 18%, 25-34세 사용자의 17%가 데이트 서비스를 이용하고 있었습니다. Hinge가 2024년 3분기에 매출을 36% 증가한 1억 4,500만 달러로 끌어올린 것은 의도적인 만남을 중시하는 서비스 설계가 이 연령대의 지지를 얻고 있음을 보여줍니다. 결혼 연령의 고령화로 인해 독일, 프랑스, 영국에서는 초혼 평균 연령이 30세를 넘어섰으며, 수익화 기간이 장기화되고 있습니다. ‘HER’의 사용자 수는 1,500만 명에 달하며, 그중 60%가 18-24세 연령층을 차지하고 있어, 젊은 층의 이용 규모 확대와 참여도 심화가 두드러지고 있습니다.
AI를 활용한 매칭 알고리즘이 사용자 참여도를 향상
인공지능은 제품 차별화 분야에서 최전선에 나서며, 궁합 예측, 대화의 시작점 마련, 개인화된 온보딩 흐름을 주도하고 있습니다. 매치 그룹의 AI ‘매치제조업체’는 프로파일 미세 조정을 제안하며, 범블의 채팅 코치는 실시간으로 대화 톤에 대한 조언을 제공합니다. AI 기반 생체 인증을 채택한 틴더의 신원 확인 기능 도입으로, 2024년에는 영국 및 기타 시장에서 신원 확인을 마친 사용자의 매칭률이 67% 향상되었습니다. ‘슈렘스 판결’은 무기한 데이터 집적을 제한하고 있어, 각 플랫폼 기업들은 GDPR(EU 개인정보보호규정)의 틀 내에서 운영되기 위해 연합 학습(federated learning) 및 기기 내 추론으로의 전환을 강요받고 있습니다. 모델 재학습에 필요한 자금력을 갖춘 기존 기업들은 소규모 신생 기업에 비해 실행 면에서 우위를 점하고 있습니다.
데이터 개인정보 보호 및 보안 침해에 대한 우려 고조
노르웨이는 2024년, 동의 없이 위치 정보 및 성적 지향 데이터를 공유했다는 이유로 Grindr에 6,500만 노르웨이 크로네(643만 달러)의 벌금을 부과했습니다. 이탈리아 규제 당국은 2024년 2월, 100만 건의 프로파일을 불법적으로 처리했다는 이유로 Nirvam에 20만 유로(23만 2,910달러)의 벌금을 부과했습니다. 유럽 데이터 보호 위원회는 2024년 10월의 견해에서 ‘동의 아니면 지불’ 모델이 GDPR(EU 개인정보보호규정)에 부합하지 않는다고 선언했습니다. 루벤 가톨릭 대학교(KU Leuven)의 연구에 따르면, 2024년에 15개의 인기 앱이 기밀 데이터를 유출했으며, 그중 6개는 정확한 위치 정보를 유출한 것으로 밝혀졌습니다. 이러한 움직임으로 인해 플랫폼들은 구독형 수익 모델로의 전환이나 더욱 엄격한 데이터 최소화 조치를 취해야 하는 상황에 직면해 있습니다.
부문 분석
유료 서비스는 2025년 매출의 60.72%를 차지한 것으로 평가되었으며, AI 매칭, 화상 통화, 구독에 포함된 우선 노출 기능에 힘입어 연평균 성장률(CAGR) 7.72%를 나타낼 것으로 전망됩니다. 유럽 온라인 데이트 서비스 시장에서 유료 플랜에 기인한 시장 규모는 2031년까지 프리미엄의 성장을 능가할 전망입니다. Match사는 Tinder의 유료 사용자 1,000만 명을 유지한 반면, Hinge의 유료 사용자 수는 2024년 3분기에 38% 증가한 190만 명에 도달했습니다. Bumble의 유료 사용자 수는 400만 명이었으나, 총 사용자 수는 7% 감소했습니다. 가격 조정으로 인해 Tinder Platinum의월이용료는 32.99파운드(41달러)가 되었습니다.
무료 요금제의 점유율은 39.28%를 차지하고 있지만, 광고 규제가 강화되는 상황에 직면해 있습니다. 유럽의 온라인 데이팅 서비스 시장에서는 ‘동의인가, 아니면 과금인가’라는 논쟁이 주목받고 있습니다. 규제 당국이 데이터 소모가 많은 광고를 금지할 경우, 무료 요금제는 기본적인 스와이프 기능만으로 축소되어 사용자들은 유료 요금제로 전환해야 할 상황에 처하게 됩니다. 이미 무료 사용자의 3-5%가 유료 사용자로 전환되었으며, 이들은 플랫폼 수익의 최대 90%를 창출하고 있습니다.
모바일 애플리케이션는 2025년 수익의 71.15%를 차지한 것으로 평가되었으며, 5G 보급과 푸시 알림을 통한 사용자 참여도 심화에 힘입어 연평균 성장률(CAGR) 7.88%를 기록할 전망입니다. 유럽의 온라인 데이트 서비스 시장은 모바일 기반 위치 정보 검색, 카메라 기능을 활용한 컨텐츠, 인앱 결제에 의존하고 있으며, 이는 데스크톱에서는 실현할 수 없는 장점입니다. Bumble은 웹을 통한 수익은 미미한 반면, 모바일 수익은 2억 2,100만 달러를 기록했습니다.
데스크톱 및 웹은 28.85%의 점유율을 유지했으며, 큰 화면에서 장문의 설문조사에 응답하는 고령 사용자들의 지지를 받고 있습니다. 반응형 웹 디자인(Responsive Web Design)과 프로그레시브 웹 앱(PWA)은 데스크톱을 주축으로 하는 브랜드가 앱 스토어의 30% 수수료를 회피하는 데 도움이 되고 있습니다. ‘디지털 서비스법’에 따른 규제 평준화로 인해, 웹 전문 사업자가 기존에 누리던 규정 준수상의 우위는 해소되었으며, 두 플랫폼 모두 계속해서 경쟁력을 유지하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the Europe online dating services market size was valued at USD 1.15 billion in 2025 and estimated to grow from USD 1.22 billion in 2026 to reach USD 1.63 billion by 2031, at a CAGR of 5.99% during the forecast period (2026-2031).
This report is Segmented by Type (Non-Paying Online Dating, and Paying Online Dating), Device Platform (Mobile Applications, and More), Age Group (18-24 Years, 25-34 Years, and More), Relationship Intent (Casual Dating, Long-Term Relationship, and More), Sexual Orientation (Heterosexual Platforms, and LGBTQ+ Platforms), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Online Dating Services Market Trends and Insights
Surge in Millennial and Gen Z Users Seeking Digital-first Socialization
Millennial and Gen Z cohorts treat dating apps as primary social infrastructure rather than add-on experiences. Eurostat reported 97% daily internet usage among 16-29-year-olds in 2024, with 83% of them actively using social networks. Ofcom found that 18% of UK users aged 18-24 and 17% aged 25-34 visited dating services in May 2024. Hinge's 36% revenue jump to USD 145 million in Q3 2024 demonstrates how intentional-dating design resonates with this audience. Delayed marriage, average first-marriage age now above 30 in Germany, France, and the UK, extends monetization windows. HER reached 15 million users, 60% of whom fall in the 18-24 bracket, underscoring youth-driven volume and engagement depth.
AI-driven Matching Algorithms Enhancing User Engagement
Artificial intelligence has moved to the front end of product differentiation, guiding compatibility predictions, conversational nudges, and personalized onboarding flows. Match Group's AI "Matchmaker" suggests profile tweaks, while Bumble's chat coach offers real-time tone advice. Tinder's ID-verification rollout, which uses AI-based liveness checks, lifted matches 67% for verified users in the UK and other markets in 2024. The Schrems decision limits indefinite data aggregation, pressing platforms toward federated learning and on-device inference to stay within GDPR bounds. Incumbents with capital to retrain models enjoy an execution edge over smaller challengers.
Escalating Concerns over Data Privacy and Security Breaches
Norway upheld a NOK 65 million (USD 6.43 million) fine on Grindr in 2024 for sharing location and sexual-orientation data without consent. Italy's regulator fined Nirvam EUR 200,000 (USD 232910) in February 2024 for unlawful processing of 1 million profiles. The European Data Protection Board's October 2024 opinion declared "consent-or-pay" models incompatible with GDPR. A KU Leuven study found that 15 popular apps leaked sensitive data in 2024, six of them revealing precise location. These moves pressure platforms toward subscription-only revenue and stricter data minimization.
Other drivers and restraints analyzed in the detailed report include:
- Integration of Video Dating and Live Streaming Features Post Pandemic
- Niche Dating Apps Targeting Specific Communities Fuel Monetization
- Proliferation of Fake Profiles and Catfishing Incidents
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Paying services represented 60.72% of 2025 revenue and are forecast to grow at an 7.72% CAGR, buoyed by AI matching, video calls, and priority visibility bundled into subscriptions. The Europe online dating services market size attributable to paying tiers is set to outstrip freemium growth through 2031. Match retained 10 million paying Tinder users, while Hinge's paying base climbed 38% to 1.9 million in Q3 2024. Bumble counted 4 million paying users, although the total number slipped 7%. Price hikes saw Tinder Platinum reach GBP 32.99 (USD 41) per month.
Non-paying tiers held a 39.28% share but face tighter advertising rules. The Europe online dating services market is watching the consent-or-pay debate; should regulators outlaw data-heavy ads, free tiers will shrink to basic swipes, nudging users toward subscriptions. Already, 3-5% of free users convert to paid users, yet they generate up to 90% of the platform's revenue.
Mobile applications captured 71.15% of 2025 revenue and will post an 7.88% CAGR as 5G spreads and push-notification engagement deepens. The Europe online dating services market relies on mobile location discovery, camera-enabled content, and in-app billing, advantages desktop cannot match. Bumble reported USD 221 million mobile revenue versus modest web totals.
Desktop and web kept a 28.85% share, favored by older users who complete long questionnaires on larger screens. Responsive web design and progressive web apps help desktop-heavy brands avoid 30% app-store fees. Regulatory parity under the Digital Services Act removes historic compliance advantages for web-only operators, keeping both platforms in play.
Complete Report Scope:
- By Type
- Non-paying Online Dating
- Paying Online Dating
- By Device Platform
- Mobile Applications
- Desktop and Web Platforms
- By Age Group
- 18-24 Years
- 25-34 Years
- 35-44 Years
- 45 Years and Above
- By Relationship Intent
- Casual Dating
- Long-term Relationship
- Niche Interest Matchmaking
- By Sexual Orientation
- Heterosexual Platforms
- LGBTQ+ Platforms
- By Country
- Germany
- United Kingdom
- France
- Spain
- Italy
- Netherlands
- Nordics (Denmark, Sweden, Norway, Finland)
- Rest of Europe
List of Companies Covered in this Report:
- Match Group Inc.
- Bumble Inc.
- Badoo Ltd
- FTW and Co (happn)
- Meetic SA
- LOVOO GmbH and Co. KG
- Plentyoffish Media ULC
- Hinge Inc.
- eHarmony Inc.
- OkCupid LLC
- Grindr LLC
- Dattch Ltd (HER)
- Once Dating AG
- Parship GmbH
- EliteMedianet GmbH (ElitePartner)
- Zoosk Inc.
- Spark Networks SE
- The Meet Group Inc.
- Feeld Ltd
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Millennial and Gen Z Users Seeking Digital-first Socialization
- 4.2.2 Rising Smartphone Penetration and Affordable Mobile Data Plans
- 4.2.3 Increasing Acceptance of Online Dating as Social Norm in Europe
- 4.2.4 Integration of Video Dating and Live Streaming Features Post-Pandemic
- 4.2.5 AI-driven Matching Algorithms Enhancing User Engagement
- 4.2.6 Niche Dating Apps Targeting Specific Communities Fuel Monetization
- 4.3 Market Restraints
- 4.3.1 Escalating Concerns over Data Privacy and Security Breaches
- 4.3.2 Proliferation of Fake Profiles and Catfishing Incidents
- 4.3.3 Saturation of Urban Markets Leading to User Acquisition Costs Inflation
- 4.3.4 Regulatory Scrutiny on Use of Personal Data for Matchmaking Algorithms
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Impact of Macroeconomic Factors
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Intensity of Competitive Rivalry
- 4.8.5 Threat of Substitutes
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Type
- 5.1.1 Non-paying Online Dating
- 5.1.2 Paying Online Dating
- 5.2 By Device Platform
- 5.2.1 Mobile Applications
- 5.2.2 Desktop and Web Platforms
- 5.3 By Age Group
- 5.3.1 18-24 Years
- 5.3.2 25-34 Years
- 5.3.3 35-44 Years
- 5.3.4 45 Years and Above
- 5.4 By Relationship Intent
- 5.4.1 Casual Dating
- 5.4.2 Long-term Relationship
- 5.4.3 Niche Interest Matchmaking
- 5.5 By Sexual Orientation
- 5.5.1 Heterosexual Platforms
- 5.5.2 LGBTQ+ Platforms
- 5.6 By Country
- 5.6.1 Germany
- 5.6.2 United Kingdom
- 5.6.3 France
- 5.6.4 Spain
- 5.6.5 Italy
- 5.6.6 Netherlands
- 5.6.7 Nordics (Denmark, Sweden, Norway, Finland)
- 5.6.8 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Global Overview, Market Overview, Segments, Financials, Strategy, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Match Group Inc.
- 6.4.2 Bumble Inc.
- 6.4.3 Badoo Ltd
- 6.4.4 FTW and Co (happn)
- 6.4.5 Meetic SA
- 6.4.6 LOVOO GmbH and Co. KG
- 6.4.7 Plentyoffish Media ULC
- 6.4.8 Hinge Inc.
- 6.4.9 eHarmony Inc.
- 6.4.10 OkCupid LLC
- 6.4.11 Grindr LLC
- 6.4.12 Dattch Ltd (HER)
- 6.4.13 Once Dating AG
- 6.4.14 Parship GmbH
- 6.4.15 EliteMedianet GmbH (ElitePartner)
- 6.4.16 Zoosk Inc.
- 6.4.17 Spark Networks SE
- 6.4.18 The Meet Group Inc.
- 6.4.19 Feeld Ltd
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


