

|
시장보고서
상품코드
2125404
북미의 온라인 데이트 서비스 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Online Dating Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
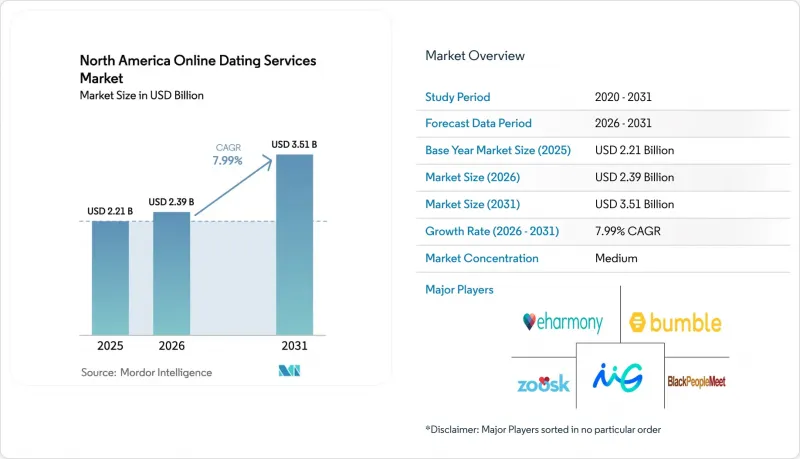
에 의하면, 2026년 북미의 온라인 데이트 서비스 시장 규모는 23억 9,000만 달러로 추정되고 2025년 22억 1,000만 달러에서 확대해, 2031년에는 35억 1,000만 달러에 이를 것으로 예측됩니다.
2026년부터 2031년까지의 연평균 성장률(CAGR)은 7.99%가 될 것으로 전망됩니다.

본 보고서는 서비스 유형(무료 온라인 데이트, 유료 온라인 데이트), 수익 모델(구독형, 프리미엄,광고 수익형, 알라카르트형 소액 결제), 기기 유형(모바일 앱, 데스크톱/웹 플랫폼), 연령대(18-30세, 30-40세, 40세 이상) 및 국가별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
북미의 온라인 데이트 서비스 시장 동향 및 인사이트
북미의 문화적 뉘앙스에 맞춘 AI 기반 매칭 알고리즘 도입이 급증
현재 각 플랫폼에서는 단순한 인구통계학적 필터에 그치지 않고, 대화의 맥락, 공통된 가치관, 지역 특유의 의사소통 단서를 반영하는 딥러닝 엔진을 도입하고 있습니다. eHarmony와 OkCupid는 북미에서 장기적인 매칭 성공률 향상에 효과가 입증된 협업 필터링 모델을 채택하고 있습니다. Match Group은 첫 메시지를 실시간으로 작성해 주는 ‘AI 윙맨’을 시범 운영 중이며, 이를 통해 첫 접촉 시의 장벽을 낮추고 구독 전환율을 높이고 있습니다. 이러한 도구들은 선택지의 과다로 인한 선택 곤란을 해결하고, 지각 가치(perceived value)를 높임으로써 사용자가 프리미엄 알고리즘을 통한 인사이트를 얻기 위해 업그레이드하도록 유도합니다. 그 결과, 사용자 수 증가세가 정체되더라도 정기 수익의 측정 가능한 증가를 가져오고 있습니다.
미국 Z세대 사이에서 특정 신앙이나 민족에 초점을 맞춘 틈새 플랫폼에 대한 수용도가 높아지고 있습니다.
문화적으로 친화적인 커뮤니티에 대한 수요가 사용자 확보 전략을 재편하고 있습니다. ‘ChristianMingle’과 ‘JDate’를 운영하는 Spark Networks는 단기적인 수익 감소에도 불구하고, Z세대 사용자를 유치하기 위해 마케팅 예산을 마이크로 인플루언서 및 캠퍼스 내 행사로 전환하고 있습니다. 커뮤니티 특화 플랫폼은 사용자 충성도 향상 및 세션당 참여 시간 연장이라는 이점을 제공하며, 이는 독점적인 기능을 통한 업셀링 가능성을 높이고 있습니다. 이러한 동향은 규모 확대를 추구하는 대중형 앱에서 특정 정체성 그룹에 서비스를 제공하는 심도 중심의 생태계로의 전환을 보여줍니다.
데이터 현지화 및 국경을 넘는 데이터 전송에 대한 규제 당국의 감시 강화
캐나다에서는 현재 명시적인 동의가 문서화되지 않은 한, 개인 데이터를 주 경계 내에 보관해야 할 의무가 있으며, 이로 인해 인프라 비용이 증가하고 데이터 사이언스 워크플로가 복잡해지고 있습니다. 미국 연방거래위원회(FTC)가 2025년 5월에 도입한 ‘정크 피(junk fee)’ 규정에 따라 총 구독 요금을 사전에 공개해야 하며, 이로 인해 은밀한 업셀링 전술이 제한되고 해지 위험이 높아지고 있습니다. 규정 준수에 드는 비용으로 인해 기능 혁신에 투입되어야 할 자원이 빼앗기고 있으며, 조정 기간 동안에는 이익률에 압박이 가해지고 있습니다.
부문별 분석
무료 요금제는 여전히 대중에게 서비스를 알리는 관문이지만, 프리미엄 요금제가 더 뛰어난 단위 수익성을 창출하고 있습니다. 2025년 북미의 온라인 데이팅 서비스 시장의 거래액 중 62.10%는 무료 사용자가 창출했습니다. AI 기반 엄선 부스트, 읽음 알림, 궁합 분석을 활용한 전환 엔진을 통해 Grindr의 유료 사용자 ARPU는 20.05달러까지 상승했습니다. 따라서 유료 사용자층은 연평균 성장률(CAGR) 10.35%로 성장하여 시장 전체의 성장세를 상회할 것으로 예측됩니다.
각 플랫폼은 광고 수익을 통한 무료 이용과 프로파일에 대한 ‘슈퍼 라이크’나 고급 검색 필터와 같은 전략적으로 배치된 유료 기능을 결합하여, 이용 의욕이 높은 사용자를 정기 결제 플랜으로 유도하고 있습니다. 신원 확인 및 부정 방지 기능과 결합된 구독 서비스의 견고한 기반은 사용자 유지율을 높이고 규제 준수 위험을 줄여줍니다. 그 결과, 북미의 온라인 데이팅 서비스 시장에서 유료 사용자 시장 규모는 2031년까지 꾸준히 확대될 것으로 예측됩니다.
투명성 관련 규제로 인해 숨겨진 프리미엄 업그레이드가 제한되고 있어, 구독 서비스 시장 점유율은 53.60%에서 정체되어 있습니다. 이에 대응하여 사업자들은 1-5달러 가격대의 단품 판매를 중시하며, 사용자가 특정 가치 제안을 체험해 볼 수 있도록 하고 있습니다. 이 소액 결제 부문은 연평균 12.35%의 성장률을 보일 것으로 예측되며, 북미의 온라인 데이팅 서비스 시장에서 가장 눈에 띄는 성장을 보일 것으로 전망됩니다.
세밀한 가격 책정은 더 광범위한 디지털 경제에서 나타나는 소비자 행동의 변화와 부합합니다. 이러한 환경에서는 사용자가 자신에게 즉각적으로 유용하다고 느끼는 기능에 대해서만 지불하는 경향이 있습니다. 경영진에게 마이크로트랜잭션은 기능 포트폴리오를 정교화하고 제품-시장 적합성을 최적화하기 위한 풍부한 분석 데이터를 얻을 수 있는 환경을 제공합니다. 이를 통해 구독 총비용을 늘리지 않으면서도 사용자 유지율을 향상시킬 수 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.14According to Mordor Intelligence, North America online dating services market size in 2026 is estimated at USD 2.39 billion, growing from 2025 value of USD 2.21 billion with 2031 projections showing USD 3.51 billion, growing at 7.99% CAGR over 2026-2031.
This report is Segmented by Service Type (Non-Paying Online Dating, Paying Online Dating), Revenue Model (Subscription-Based, Freemium, Advertising-Based, A-La-Carte Micro-Transactions), Device Type (Mobile Applications, Desktop / Web Platforms), Demographic Age Group (18-30 Years, 30-40 Years, More Than 40 Years) and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Online Dating Services Market Trends and Insights
Surging Adoption of AI-Driven Matchmaking Algorithms Tailored to North American Cultural Nuances
Platforms now deploy deep-learning engines that move beyond simple demographic filters to incorporate conversational context, shared values, and region-specific communication cues. eHarmony and OkCupid apply collaborative-filtering models proven to raise long-term match success rates in North America. Match Group is piloting "AI wingmen" that draft opening messages in real time, reducing first-contact friction and boosting subscription conversions. These tools address choice overload and improve perceived value, encouraging users to upgrade for premium algorithmic insights. The result is a measurable uplift in recurring revenue even as overall user growth normalizes.
Rising Acceptance of Niche Faith- & Ethnicity-Focused Platforms among U.S. Gen Z
Demand for culturally aligned communities is reshaping acquisition strategies. Spark Networks, owner of ChristianMingle and JDate, has redirected marketing budgets toward micro-influencers and on-campus events to attract Gen Z users despite short-term revenue contraction. Community-specific platforms gain loyalty advantages and higher engagement time per session, which translate into stronger upsell potential for exclusive features. The trend signals a shift from scale-seeking mass apps to depth-oriented ecosystems serving distinct identity groups.
Intensifying Regulatory Scrutiny around Data Localization & Cross-Border Transfers
Canada now requires personal data to stay within provincial borders unless explicit consent is documented, adding infrastructure costs and complicating data-science workflows. The U.S. Federal Trade Commission's May 2025 "junk-fee" rule demands up-front disclosure of total subscription pricing, constraining stealth upsell tactics and raising churn risk. Compliance spending diverts resources from feature innovation, pressuring margins during the adjustment window.
Other drivers and restraints analyzed in the detailed report include:
- Monetization Upside from Premium Safety Features amid Rising Scam Awareness in Canada
- Integration of Short-Form Video & Livestream Dating Driving User Engagement
- User Fatigue from Swipe-Based Interfaces Reducing Lifetime Value per Customer
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Non-paying formats remain the on-ramp for mass adoption, yet premium tiers capture superior unit economics. In 2025, non-paying users generated 62.10% of transaction volume across the North America online dating services market. Conversion engines leveraging AI-curated boosts, read receipts, and compatibility analytics lifted paying user ARPU to USD 20.05 at Grindr. The paying category is therefore forecast to grow at a 10.35% CAGR, outpacing overall market momentum.
Platforms blend ad-supported free access with strategically placed paywalls-such as profile super-likes or advanced search filters-to shift high-intent users into recurring plans. Subscription stack depth, bundled with identity verification and fraud protections, enhances stickiness and reduces regulatory compliance risk. Consequently, the North America online dating services market size for paying users is expected to climb steadily through 2031.
Subscription dominance is plateauing at 53.60% market contribution as transparency regulation limits hidden premium upgrades. In response, operators emphasize a-la-carte offerings priced between USD 1 and USD 5, allowing users to test specific value propositions. This micro-transaction segment is projected to expand 12.35% annually, making it the fastest-growing component of the North America online dating services market.
Granular pricing aligns with shifting consumer behavior in the broader digital economy, where users favor paying only for features they perceive as immediately useful. For management teams, micro-transactions provide an analytics-rich environment to refine feature portfolios and optimize product-market fit, thereby lifting retention without inflating headline subscription costs.
Complete Report Scope:
- By Service Type
- Non-Paying Online Dating
- Paying Online Dating
- By Revenue Model
- Subscription-Based
- Freemium
- Advertising-Based
- A-la-Carte Micro-Transactions
- By Device Type
- Mobile Applications
- Desktop / Web Platforms
- By Demographic Age Group
- 18-30 Years
- 30-40 Years
- More than 40 Years
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Match Group, Inc.
- Zoosk, Inc.
- Badoo
- BlackPeopleMeet.com, Inc.
- Bumble Inc.
- The Meet Group, Inc.
- Coffee Meets Bagel, Inc.
- The League App, Inc.
- HER (Dattch Ltd.)
- Taimi Inc.
- Grindr LLC
- eHarmony, Inc.
- Hily Corp.
- Raya App, Inc.
- PlentyOfFish Media ULC
- OkCupid LLC
- Spark Networks SE
- OurTime.com
- SilverSingles
- ChristianMingle (Spark)
- Ashley Madison (Ruby Corp.)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging Adoption of AI-driven Matchmaking Algorithms Tailored to North American Cultural Nuances
- 4.2.2 Rising Acceptance of Niche Faith- & Ethnicity-Focused Platforms among U.S. Gen-Z
- 4.2.3 Monetization Upside from Premium Safety Features amid Rising Scam Awareness in Canada
- 4.2.4 Integration of Short-Form Video & Livestream Dating Driving User Engagement
- 4.2.5 Growing LGBTQ+ Community Visibility Accelerating Platform Expansion in Urban Corridors
- 4.3 Market Restraints
- 4.3.1 Intensifying Regulatory Scrutiny around Data Localization & Cross-Border Transfers
- 4.3.2 User Fatigue from Swipe-Based Interfaces Reducing Lifetime Value per Customer
- 4.3.3 Heightened Competition from Social-Media-Embedded Dating Features (e.g., Facebook Dating)
- 4.3.4 Rising Acquisition Costs on Digital Ad Channels Pressuring Smaller Apps
- 4.4 Value Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Consumers
- 4.6.3 Threat of New Entrants
- 4.6.4 Intensity of Competitive Rivalry
- 4.6.5 Threat of Substitutes
- 4.7 Investment Analysis
- 4.8 Assessment of Macro Economic Trends on the Market
- 4.9 Major Use-Cases & Case-Studies
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Service Type
- 5.1.1 Non-Paying Online Dating
- 5.1.2 Paying Online Dating
- 5.2 By Revenue Model
- 5.2.1 Subscription-Based
- 5.2.2 Freemium
- 5.2.3 Advertising-Based
- 5.2.4 A-la-Carte Micro-Transactions
- 5.3 By Device Type
- 5.3.1 Mobile Applications
- 5.3.2 Desktop / Web Platforms
- 5.4 By Demographic Age Group
- 5.4.1 18-30 Years
- 5.4.2 30-40 Years
- 5.4.3 More than 40 Years
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves & Funding Activity
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Match Group, Inc.
- 6.4.2 Zoosk, Inc.
- 6.4.3 Badoo
- 6.4.4 BlackPeopleMeet.com, Inc.
- 6.4.5 Bumble Inc.
- 6.4.6 The Meet Group, Inc.
- 6.4.7 Coffee Meets Bagel, Inc.
- 6.4.8 The League App, Inc.
- 6.4.9 HER (Dattch Ltd.)
- 6.4.10 Taimi Inc.
- 6.4.11 Grindr LLC
- 6.4.12 eHarmony, Inc.
- 6.4.13 Hily Corp.
- 6.4.14 Raya App, Inc.
- 6.4.15 PlentyOfFish Media ULC
- 6.4.16 OkCupid LLC
- 6.4.17 Spark Networks SE
- 6.4.18 OurTime.com
- 6.4.19 SilverSingles
- 6.4.20 ChristianMingle (Spark)
- 6.4.21 Ashley Madison (Ruby Corp.)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Scenario Outlook: Metaverse Dating & Virtual Reality Integration


