|
시장보고서
상품코드
2116883
인도의 전기 이륜차 배터리 교환 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)India Battery Swapping For Electric Two-Wheelers - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
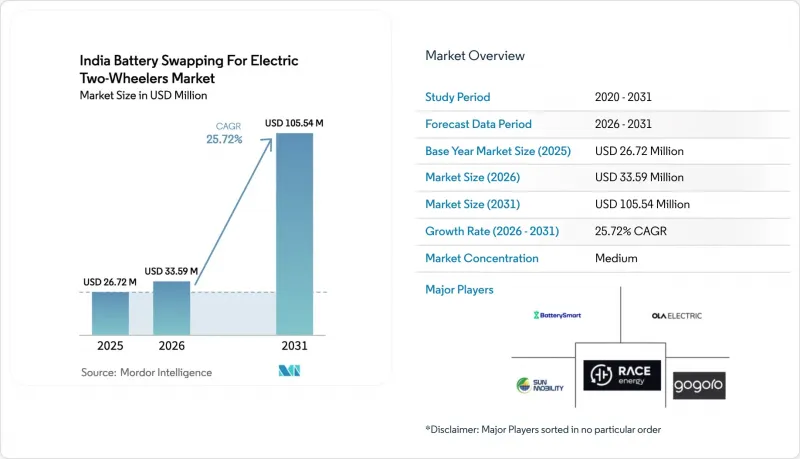
에 의하면, 인도 전기 이륜차 배터리 교환 시장 규모는 2025년에 2,672만 달러로 평가되었고 2026년 3,359만 달러에서 2031년까지 1억 554만 달러에 이를 것으로 예측되며, 예측 기간 CAGR은 25.72%입니다(2026-2031년).
본 보고서는 서비스 모델(사용량 기반 과금제 등), 배터리 화학 조성(리튬 이온 NMC/NCA 등), 차량 카테고리(전기 스쿠터 등), 최종 사용자(개인 통근자 등), 배터리 용량(2.0 이하, 2.1-3.0 이상 등),스테이션 유형(고정식 캐비닛, 이동식 키오스크 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
인도 전기 이륜차 배터리 교체 시장 동향 및 인사이트
FAME-II 인센티브에 따른 전기 이륜차 판매 대수의 급격한 증가
PM e-DRIVE는 2025년 6월 26일에 승인되었으며, 전기차 수요 촉진 인센티브를 지원하기 위해 2024-25 회계연도부터 2028-29 회계연도에 걸쳐 10,900 카롤 루피의 예산이 편성되었습니다. 기존 보조금 제도가 단계적으로 폐지되는 가운데, 각 제조업체는 가격 경쟁력을 유지하기 위해 혁신과 업무 효율화에 주력하고 있습니다. 특히 마하라슈트라주, 카르나타카주, 타밀나두주 등 추가 인센티브를 제공하는 주에서는 도입이 활발히 진행되고 있습니다. 이에 따라 사용자층이 확대되고 있으며, 편의성과 비용 면에서의 이점으로 인해 배터리 교체 인프라를 이용하는 사람이 늘고 있습니다.
리튬 이온 배터리 비용 감소와 팩 조립의 현지화
인도에서는 배터리 생태계에 획기적인 변화가 나타나고 있으며, 국내 생산 라인이 조만간 가동을 시작할 전망입니다. 이러한 전환은 수입 의존도를 낮추고, 외화 부족을 완화하며, 총비용을 절감하는 것을 목적으로 합니다. 배터리 화학 성분으로는 인산철리튬(LFP)이 주목받고 있는데, 특히 배터리 교환과 같이 사용 빈도가 높은 용도에서 다른 대안에 비해 수명이 길고 비용 대비 효율이 뛰어나기 때문입니다.
국내 생산은 기동성이 높은 공급망을 조성하고, 적시 납품을 촉진하는 동시에 대량의 재고 보유 필요성을 줄여줍니다. 또한, 로봇을 통한 취급에 대응하도록 표준화된 배터리 하우징은 업무 효율 향상에 기여합니다. 이러한 효율화가 누적됨에 따라 구독 비용은 낮아질 것으로 예상되며, 전기 이륜차의 보급이 촉진되어 시장 확대로 이어질 것으로 전망됩니다.
화재 사고가 소비자의 신뢰를 훼손한다.
전기 이륜차 시장에서는 특히 소셜 미디어를 통해 사고 소식이 퍼지면 안전에 대한 우려가 큰 그림자를 드리웁니다. 설령 화재가 비공식적인 애프터마켓 개조에 기인한 경우라 할지라도, 일반인들은 종종 그 위험을 해당 카테고리 전체로 일반화해 버립니다.
BIS 기준과 같은 규제 기준은 더 안전한 제품을 위한 틀을 제공하지만, 단순히 이러한 기준을 준수하는 것만으로는 소비자의 신뢰를 회복하기에 충분하지 않습니다. 가격에 민감한 구매자들에게 안심을 주고, 전기 모빌리티로의 전환 추세를 유지하기 위해서는 일관된 안전 성능을 확보하고, 투명한 조사를 실시하며, 사고에 대해 명확한 정보를 제공하는 것이 필수적입니다.
부문 분석
종량제 옵션이 2025년 매출의 42.80%를 계속 차지했지만, 구독 플랜의 점유율은 확대되었습니다. 상업용 차량은 고정된월지출과 대차대조표 외 처리를 중시하고 있으며, 이는 구독 부문의 예상 연평균 성장률(CAGR) 27.36% 달성에 기여하고 있습니다. Hero MotoCorp가 2025년 7월에 출시한 VIDA VX2는 섀시와 배터리의 금융을 분리하여, 긱 경제(gig economy) 고객을 대상으로 하는 OEM의 기동성을 보여주고 있습니다.
구독 계약은 자본 지출(Capex)을 운영 비용(OpEx)으로 전환하여, 구매의 걸림돌이 되기 쉬운 배터리 비용의 30-40%를 경감시킵니다. Battery Smart의 단계별 요금제는 일일 주행 거리 대역에 따라 가격을 책정하여, 수요가 부진한 기간에 차량 함대가 과도한 비용을 지불하는 것을 방지합니다. 예측 가능한 수익원은 대출 기관의 위험을 줄이고 이자 부담을 경감시킵니다. 개인 통근자들은 여전히 고정형 계약을 피하기 위해 종량제 요금제를 선호하지만, 차량 대여와 결합된 하이브리드형이 계약 기간 중반의 틈새 시장을 채우고 있습니다.
2025년에는 리튬 이온 NMC/NCA가 62.40%의 점유율을 차지했지만, LFP의 27.70%라는 연평균 성장률(CAGR)은 안전성과 비용의 상충 관계에서 LFP에 유리하게 작용하고 있음을 시사합니다. LFP의 3,000-5,000 사이클 수명은 고처리량 배터리 교체와 자연스럽게 잘 어울리며, 고유한 열적 안정성으로 화재 위험을 억제할 수 있어 기업 평판을 지키는 데 매우 중요합니다.
각 OEM 업체들의 움직임도 이러한 전환을 뒷받침하고 있습니다. Ola Electric의 3세대 플랫폼은 LFP로 전환되고 있으며, 국내 배터리 생산 라인도 원자재 확보 용이성 때문에 인산철계 화학 조성을 선호하고 있습니다. 수직 통합을 통해 팩 비용이 절감됨에 따라, LFP 팩에 의존하는 인도의 전기 이륜차 배터리 교체 시장 규모는 2031년까지 NMC와의 격차를 좁힐 것으로 예측됩니다. 납산 배터리가 살아남는 분야는 시속 25km 이하의 저속 차량으로 한정되지만, 리튬 가격 하락에 따라 이 틈새 시장은 급속히 축소되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.03According to Mordor Intelligence, the India battery swapping for electric two-wheelers market size was valued at USD 26.72 million in 2025 and estimated to grow from USD 33.59 million in 2026 to reach USD 105.54 million by 2031, at a CAGR of 25.72% during the forecast period (2026-2031).
This report is Segmented by Service Model (Pay-Per-Use, and More), Battery Chemistry (Lithium-Ion NMC/NCA, and More), Vehicle Category (Electric Scooters, and More), End User (Personal Commuters, and More), Battery Capacity (Up To 2. 0, 2. 1-3. 0, and More), Swap Station Type (Fixed Cabinet, Mobile Kiosk, and More). The Market Forecasts are Provided in Terms of Value (USD).
India Battery Swapping For Electric Two-Wheelers Market Trends and Insights
Rapid Growth in E-Two-Wheeler Sales Via FAME-II Incentives
PM e-DRIVE was approved on June 26, 2025, with an outlay of ₹10,900 crore for 2024-25 to 2028-29 to support demand incentives for EVs. With the phasing out of previous subsidy schemes, manufacturers are channeling their efforts into innovation and operational efficiency to maintain price competitiveness. Adoption is rising, especially in states like Maharashtra, Karnataka, and Tamil Nadu, which offer extra incentives. This has led to a broader user base, many turning to battery-swapping infrastructure for its convenience and cost benefits.
Declining Li-Ion Costs and Localization of Pack Assembly
India is witnessing a pivotal shift in its battery ecosystem, with domestic production lines poised to commence operations. This transition aims to curtail import dependence, alleviate foreign exchange strains, and trim overall expenses. Lithium iron phosphate (LFP) is gaining traction among battery chemistries, especially for high-usage applications like swapping, due to its extended lifespan and cost-effectiveness compared to other options.
Domestic manufacturing fosters nimble supply chains, facilitating just-in-time deliveries and diminishing the necessity for extensive inventory. Moreover, standardized battery housings for robotic handling enhance operational efficiency. As these efficiencies accumulate, subscription costs are anticipated to decrease, broadening the accessibility of electric mobility and amplifying market reach.
Fire-Safety Incidents Dent Consumer Confidence
Safety concerns loom large over the electric two-wheeler market, especially when incidents gain traction on social media. Even when fires stem from unauthorized aftermarket conversions, the public often generalizes the risk across the entire category.
While regulatory standards like BIS norms provide a framework for safer products, merely adhering to these standards isn't enough to rebuild consumer trust. To reassure price-sensitive buyers and maintain momentum in the shift to electric mobility, it's crucial to ensure consistent safety performance, conduct transparent investigations, and communicate incidents clearly.
Other drivers and restraints analyzed in the detailed report include:
- Draft Battery Swapping Policy Enabling Interoperability
- BIS Safety Standards Unlocking Financing and Insurance
- Import-Dependent Cell Supply Exposed to Geo-Political Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Subscription plans increased their footprint even though the Pay-Per-Use option retained 42.80% of 2025 revenue. Commercial fleets value fixed monthly outlays and off-balance-sheet treatment, helping the subscription segment log a forecast 27.36% CAGR. Hero MotoCorp's July 2025 VIDA VX2 launch separates chassis and battery financing, showcasing OEM agility in serving gig-economy clients.
Subscription contracts convert capex into opex, mitigating the 30-40% battery cost that often stalls purchases. Tiered plans from Battery Smart align pricing with daily-kilometer bands, ensuring fleets avoid overpaying during slack demand. Predictable revenue streams lower lenders' risk, reducing interest burdens. Individual commuters still lean toward Pay-Per-Use to avoid fixed commitments, while fleet-leasing hybrids fill mid-tenure niches.
Lithium-ion NMC/NCA held 62.40% share in 2025, yet LFP's 27.70% CAGR suggests the safety-value trade-off tilts in its favor. LFP's 3,000-5,000 cycle life pairs naturally with high-throughput swapping, and inherent thermal stability curbs fire risks, a vital reputation safeguard.
OEM moves validate the shift: Ola Electric's Gen 3 platform pivots to LFP, while domestic cell lines favor iron-phosphate chemistry due to raw-material availability. The India battery swapping for electric two-wheelers market size tied to LFP packs is forecast to close the gap with NMC by 2031 as vertical integration compresses pack costs. Lead-acid persists only in low-speed, sub-25 km/h vehicles, a niche eroding fast as lithium prices fall.
Complete Report Scope:
- By Service Model
- Pay-Per-Use
- Subscription
- Fleet Leasing (Long-Term)
- By Battery Chemistry
- Lithium-ion (NMC/NCA)
- Lithium-ion (LFP)
- Lead-acid
- By Vehicle Category
- Electric Scooters
- Electric Motorcycles
- Electric Mopeds
- By End User
- Personal Commuters
- Gig-Economy Delivery Fleets
- Ride-Sharing / Subscription Platforms
- By Battery Capacity (kWh)
- Up to 2.0
- 2.1-3.0
- 3.1-5.0
- Above 5.0
- By Swap Station Type
- Fixed Cabinet
- Mobile Kiosk
- Fully-Automated Robotic
- Retail-Outlet Integrated (Battery ATM)
List of Companies Covered in this Report:
- SUN Mobility
- Upgrid Solutions Private Limited (Battery Smart)
- Ola Electric Mobility Limited
- RACE Energy Ltd.
- Lithion Power Private Limited
- VoltUp Mobility Pvt. Ltd.
- Esmito Solutions Pvt. Ltd.
- Numocity Technologies Pvt. Ltd.
- Charge-up Mobility Pvt. Ltd.
- Okaya Power Group
- Bounce Infinity
- Yulu Bikes Pvt. Ltd.
- Gogoro
- Hero MotoCorp Ltd.
- Kinetic Green Energy and Power Solutions Ltd.
- Ampere Vehicles Pvt. Ltd.
- Exide Industries Ltd.
- Bharat Petroleum Corporation Ltd. (BPCL)
- Indian Oil Corporation Ltd. (IOCL)
- Zypp Electric Pvt. Ltd.
- eBikeGo Mobility Pvt. Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid Growth in E-Two-Wheeler Sales Via FAME-II Incentives
- 4.2.2 Draft Battery Swapping Policy Enabling Interoperability
- 4.2.3 VC and OMC Investments Accelerating Swap Station Roll-Out
- 4.2.4 High-Utilization Gig-Economy Demand for Near-Zero Downtime
- 4.2.5 Declining Li-Ion Costs and Localization of Pack Assembly
- 4.2.6 BIS Safety Standards Unlocking Financing and Insurance
- 4.3 Market Restraints
- 4.3.1 Fragmented Battery Form-Factors Hinder Interoperability
- 4.3.2 Uncertain GST On Battery-as-a-Service Revenues
- 4.3.3 Fire-Safety Incidents Dent Consumer Confidence
- 4.3.4 Import-Dependent Cell Supply Exposed to Geo-Political Risk
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value, USD)
- 5.1 By Service Model
- 5.1.1 Pay-Per-Use
- 5.1.2 Subscription
- 5.1.3 Fleet Leasing (Long-Term)
- 5.2 By Battery Chemistry
- 5.2.1 Lithium-ion (NMC/NCA)
- 5.2.2 Lithium-ion (LFP)
- 5.2.3 Lead-acid
- 5.3 By Vehicle Category
- 5.3.1 Electric Scooters
- 5.3.2 Electric Motorcycles
- 5.3.3 Electric Mopeds
- 5.4 By End User
- 5.4.1 Personal Commuters
- 5.4.2 Gig-Economy Delivery Fleets
- 5.4.3 Ride-Sharing / Subscription Platforms
- 5.5 By Battery Capacity (kWh)
- 5.5.1 Up to 2.0
- 5.5.2 2.1-3.0
- 5.5.3 3.1-5.0
- 5.5.4 Above 5.0
- 5.6 By Swap Station Type
- 5.6.1 Fixed Cabinet
- 5.6.2 Mobile Kiosk
- 5.6.3 Fully-Automated Robotic
- 5.6.4 Retail-Outlet Integrated (Battery ATM)
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 SUN Mobility
- 6.4.2 Upgrid Solutions Private Limited (Battery Smart)
- 6.4.3 Ola Electric Mobility Limited
- 6.4.4 RACE Energy Ltd.
- 6.4.5 Lithion Power Private Limited
- 6.4.6 VoltUp Mobility Pvt. Ltd.
- 6.4.7 Esmito Solutions Pvt. Ltd.
- 6.4.8 Numocity Technologies Pvt. Ltd.
- 6.4.9 Charge-up Mobility Pvt. Ltd.
- 6.4.10 Okaya Power Group
- 6.4.11 Bounce Infinity
- 6.4.12 Yulu Bikes Pvt. Ltd.
- 6.4.13 Gogoro
- 6.4.14 Hero MotoCorp Ltd.
- 6.4.15 Kinetic Green Energy and Power Solutions Ltd.
- 6.4.16 Ampere Vehicles Pvt. Ltd.
- 6.4.17 Exide Industries Ltd.
- 6.4.18 Bharat Petroleum Corporation Ltd. (BPCL)
- 6.4.19 Indian Oil Corporation Ltd. (IOCL)
- 6.4.20 Zypp Electric Pvt. Ltd.
- 6.4.21 eBikeGo Mobility Pvt. Ltd.