

|
시장보고서
상품코드
2118064
디지털 오디오 플랫폼 시장 : 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Digital Audio Platforms - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
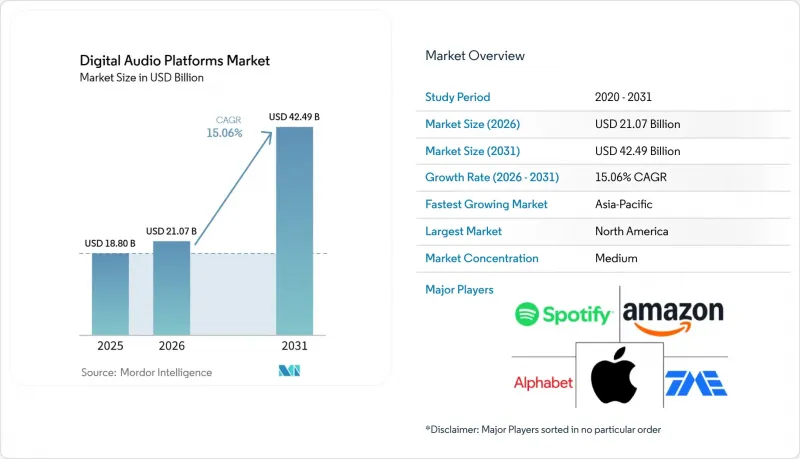
에 의하면, 디지털 오디오 플랫폼 시장 규모는 2025년 188억 달러에서 2026년에는 210억 7,000만 달러로 확대되어 2031년까지 424억 9,000만 달러에 이른다고 전망되고 있어 2026년부터 2031년까지 CAGR 15.06%를 나타낼 것으로 예측됩니다.
본 보고서는 포맷 유형(온디맨드 음악 스트리밍, 라이브 인터넷 라디오, 팟캐스트 호스팅 등), 수익화 모델(구독형, 광고형, 트랜잭션형, 하이브리드형 등), 기기(스마트폰·태블릿, 노트북·데스크톱 PC,스마트 스피커·스마트 디스플레이, 커넥티드카 등) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 디지털 오디오 플랫폼 시장 동향 및 인사이트
신흥 경제국에서의 구독 요금 합리화
2025년, 인도의 유료 음악 구독자 수는 1,440만 명이었으나, 인터넷 사용자 수는 7억 명을 넘어섰습니다. 인도의 유료 음악 구독은 연간 37% 증가했으며, 오디오 구독 매출은 103억 루피(1억 1,820만 달러)를 넘어섰습니다. 인도의 사용자 1인당 연간 수익은 4-10달러 범위였으나, 미국에서는 100-140달러였습니다. 따라서 저렴한 가격 책정을 통해 가구 소득이 상승하기 전에 대규모 사용자층에게 음악 청취 습관을 정착시킬 수 있습니다. 이 접근 방식에서는 저가 요금제를 일시적인 할인이 아닌, 장기적인 고객 유지를 위한 투자로 포지셔닝하고 있습니다. 인도의 유료 가입자 수는 2028년까지 2배 이상 증가할 것으로 예상되며, 매출은 220억 루피(2억 3,600만 달러)에 달할 것으로 전망됩니다.
통신사의 OTT 번들링이 유료 가입자 확대에 박차를 가하고 있습니다.
신용카드 이용 제한으로 인해 직접적인 디지털 결제가 제한되고 있는 디지털 오디오 플랫폼 시장에서 통신사는 중요한 가입자 확보 채널로 자리 잡고 있습니다. 2026년 5월, 릴라이언스 지오(Reliance Jio)는 15개의 스트리밍 플랫폼, 30GB의 데이터 용량, 28일간의 5G 무제한 접속을 이용할 수 있는 200루피(2.40달러)짜리 OTT 패스를 출시했습니다. 2026년 6월, 셀콤 디지(CelcomDigi)는 말레이시아에서 월 19.90 말레이시아 링깃(4.50 달러)부터 시작하는 ‘StreamMORE’ 요금제를 도입했습니다. 또한, 보다폰 아이디어(Vodafone Idea)도 2026년 6월, 대상 후불 요금제에 Spotify Premium을 통합한 인도 최초의 통신사가 되었습니다. 이 모델은 JioSaavn Pro 및 Apple Music을 둘러싼 기존 통신사들과의 제휴에 이은 것입니다. 모바일 요금제를 통해 확보한 가입자는 청구 주기가 요금제 갱신 주기와 연동되어 있어 해지율이 낮아질 가능성이 있습니다.
ARPU 증가율을 상회하는 로열티율 상승
2025년에는 컨텐츠 사용료가 주요 플랫폼 수익의 65%에서 68%를 차지하며, 매출 총이익률 상승 여지를 제한했습니다. Spotify는 2025년에 110억 달러 이상의 사용료를 지불했다고 보고했으며, 이는 전년 대비 10% 이상 증가한 수치입니다. Spotify의 2025년 4분기 매출총이익률은 32.2%로, 컨텐츠 및 플랫폼 비용이 수익에서 큰 비중을 차지했음을 보여줍니다. 미국의 ‘Phonorecords IV’ 체계에 따라 2027년 정점에 도달할 때까지 작사·작곡 로열티 비용은 계속 상승하고 있습니다. 또한, 대형 음반사들도 라이선싱 협상에서 소비자 세분화와 사용자 1인당 수익 증대를 최우선 과제로 삼고 있습니다. 디지털 오디오 플랫폼 시장 중에서도 저가대 부문은 특히 큰 압박을 받고 있습니다. 이는 청취자 1인당 수익 증가세가 총 재생 시간이나 로열티 지급 의무 증가세보다 완만하기 때문입니다.
부문 분석
2025년, 온디맨드 음악 스트리밍은 시장 가치의 52.53%를 차지했습니다. 청취자들이 라디오나 다운로드에서 개인화된 온디맨드 서비스로 전환함에 따라 디지털 오디오 플랫폼 시장은 혜택을 보고 있습니다. 2025년 말 기준, 유료 음악 스트리밍 계정 수는 전 세계적으로 8억 3,700만 건에 달했습니다. 2025년 구독형 스트리밍 수익은 8.8% 증가하여, 북미와 유럽에서 가입자 수 증가세가 둔화되었음에도 불구하고 지속적인 수익 창출을 뒷받침했습니다. 라이브 인터넷 라디오는 일부 유럽 및 미국 시장에서 이용량이 감소했으나, 신흥 경제국의 스마트폰 사용자들은 여전히 이를 이용하고 있습니다.
오디오북 스트리밍은 2026년부터 2031년까지 연평균 성장률(CAGR) 15.16%를 나타낼 것으로 예측됩니다. 2025년 미국의 오디오북 매출은 9% 증가한 24억 3,000만 달러에 달했으며, 75만 개 이상의 활성 타이틀을 이용할 수 있었습니다. Spotify는 2026년 5월, 오디오북 청취 시간이 전년 대비 60% 증가했다고 발표했습니다. ‘Audiobooks+’는 구독자 수 100만 명을 달성했으며, 연간 경상 수익(ARR)은 1억 달러에 달할 전망입니다. 기존의 스마트폰 및 스마트 스피커 인프라 덕분에, 이미 음악 플랫폼을 이용하고 있는 오디오북 청취자들에게 도달하는 데 드는 추가 비용을 절감할 수 있습니다.
지역별 분석
2025년, 북미는 세계 시장 가치의 38.40%를 차지했습니다. 이 지역은 미국 및 캐나다에서 사용자당 수익이 높고, 유료 구독자 기반도 성숙해 있습니다. 멕시코의 음반 시장은 2025년에 13.3% 성장했습니다. Spotify, Apple Music, Amazon Music, YouTube Music은 독점 제공 팟캐스트, 하드웨어 연동, 개인화 기능을 활용하여 미국 시장에서 경쟁을 펼치고 있습니다. 제너럴 모터스(GM)의 다년 계약을 통한 Apple Music 제공, 토요타의 Spotify 네이티브 연동, 볼보의 Apple Music 도입은 플랫폼 접근을 자동차 소유와 연계하고 있습니다. 남미 시장은 여전히 규모가 작지만, 브라질에서는 2025년에 14.1%의 성장률을 기록했습니다. Claro Musica는 브라질, 아르헨티나 및 인근 시장에서 통신사와의 번들 계약과 지역별 음악 카탈로그를 활용하고 있습니다.
아시아태평양은 디지털 오디오 플랫폼 시장에서 가장 빠르게 성장하는 지역이 될 것으로 예상되며, 2031년까지 연평균 성장률(CAGR)은 16.11%에 달할 전망입니다. 인도의 유료 음악 서비스 가입자 수는 가격 인하와 통신사와의 번들 계약이 가입 촉진을 뒷받침한 결과, 2025년에는 37% 증가하여 1,440만 명에 달했습니다. 중국은 2025년에 20.1% 성장하여 세계 4위의 음반 시장이 되었습니다. 텐센트 뮤직 엔터테인먼트는 2026년 6월, Ximalaya를 24억 달러에 인수하며 팟캐스트 및 오디오북 분야에서의 입지를 확대했습니다. 일본은 2025년에 8.9%의 성장을 기록했으며, 고음질 오디오에 대한 수요가 프리미엄 전략을 뒷받침했습니다. 한국에서도 현대자동차의 플랫폼을 통해 커넥티드카에서의 음악 청취 채널이 확대되고 있습니다. 유럽은 2025년에 5.6%의 성장률을 보였으나, 개인정보 보호 규정 변경으로 인해 광고 수익형 서비스의 설계가 재검토되고 있습니다.
중동 및 아프리카은 성장을 이루었으며, 사우디아라비아와 아랍에미리트(UAE)가 소비 증가를 뒷받침했습니다. 걸프협력회의(GCC) 국가 시장 전체에서 스마트폰 보급률이 90%를 넘어서면서, 앱을 통한 직접 이용이 촉진되고 있습니다. 이 지역의 통신 사업자들은 프리미엄 후불 요금제에 오디오 서비스를 포함시키는 사례가 늘고 있습니다. Anghami사는 이러한 통신 사업자 모델을 활용하여 세계 서비스와 병행하여 지역적인 가입자 기반을 구축해 왔습니다. Boomplay는 아프리카 전용 컨텐츠 카탈로그, 데이터 사용량을 줄인 스트리밍, 모바일 머니를 통한 결제를 통해 지역 내 입지를 확고히 했습니다. 사용자 1인당 수익이 낮은 점은 여전히 제약 요인이지만, 모바일 우선의 젊은 사용자층이 디지털 오디오 플랫폼 시장의 장기적인 이용 규모 확대를 뒷받침하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
JHS 26.09.01According to Mordor Intelligence, the digital audio platforms market size is expected to increase from USD 18.80 billion in 2025 to USD 21.07 billion in 2026 and reach USD 42.49 billion by 2031, growing at a CAGR of 15.06% over 2026-2031.
This report is Segmented by Format Type (On-Demand Music Streaming, Live Internet Radio, Podcast Hosting, and More), Monetization Model (Subscription-Based, Advertising-Based, Transaction-Based, Hybrid, and More), Device (Smartphones and Tablets, Laptops and Desktops, Smart Speakers and Smart Displays, Connected Cars, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Audio Platforms Market Trends and Insights
Subscription Price Rationalization in Emerging Economies
India had 14.4 million paid music subscribers in 2025, compared with an internet user base of more than 700 million people. Paid music subscriptions in the country increased 37% during the year, while audio subscription revenue exceeded INR 10.3 billion (USD 118.2 million). Annual revenue per user in India ranged from USD 4 to USD 10, compared with USD 100 to USD 140 in the United States. Lower prices can therefore build listening habits among large groups before household incomes rise. This approach treats lower-priced tiers as a longer-term engagement investment rather than a short-lived discount. India's paid subscriber base is forecast to more than double by 2028, with revenue forecast to reach INR 22 billion (USD 236 million).
Telco OTT Bundling Pushes Paid Uptake
Telecom operators have become important subscriber channels for the digital audio platforms market where card use limits direct digital payments. In May 2026, Reliance Jio launched an INR 200 (USD 2.40) OTT pass with 15 streaming platforms, 30 GB of data, and unlimited 5G access for 28 days. In June 2026, CelcomDigi introduced StreamMORE plans in Malaysia from MYR 19.90 (USD 4.50) per month. Vodafone Idea also became the first Indian carrier to include Spotify Premium in eligible postpaid plans during June 2026. This model follows earlier carrier relationships involving JioSaavn Pro and Apple Music. Subscribers acquired through a mobile plan can have lower churn because their billing is tied to the plan renewal cycle.
Royalty-Rate Inflation Exceeding ARPU Growth
Content royalties consumed 65% to 68% of major platform revenue in 2025, limiting the room for higher gross margins. Spotify reported paying more than USD 11 billion in royalties during 2025, which was more than 10% higher than the prior year. Spotify's fourth-quarter 2025 gross margin was 32.2%, meaning content and platform costs represented a large share of revenue. The U.S. Phonorecords IV framework continues to increase songwriting royalty costs through its 2027 peak. Major labels are also using consumer segmentation and higher revenue per user as priorities in licensing discussions. Pressure is greatest in lower-priced parts of the digital audio platforms market because revenue per listener grows more slowly than total listening and royalty obligations.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Smart Speaker Install Base Expansion
- OEM-Level In-Car Streaming Integrations
- Content-License Windowing by Major Labels
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
On-demand music streaming held 52.53% of market value in 2025. The digital audio platforms market has benefited as listeners shift from radio and downloads to personalized, on-demand services. Paid music streaming accounts reached 837 million worldwide by the end of 2025. Subscription streaming revenue increased 8.8% during 2025, which supported continuing monetization even as subscriber growth slowed in North America and Europe. Live internet radio has declined in volume across several Western markets but still serves smartphone users in emerging economies.
Audiobook streaming is projected to record a 15.16% CAGR between 2026 and 2031. U.S. audiobook sales increased 9% to USD 2.43 billion in 2025, and more than 750,000 active titles were available. Spotify stated in May 2026 that audiobook listening hours had increased 60% year over year. Audiobooks+ reached 1 million subscribers and was tracking toward USD 100 million in annualized recurring revenue. Existing smartphone and smart speaker infrastructure lowers the added cost of reaching audio listeners who already use a music platform.
Complete Report Scope:
- By Format Type
- On-Demand Music Streaming
- Live Internet Radio
- Podcast Hosting
- Audiobook Streaming
- Other Format Types
- By Monetization Model
- Subscription-Based
- Advertising-Based
- Transaction-Based
- Hybrid Model
- Freemium Model
- By Device
- Smartphones and Tablets
- Laptops and Desktops
- Smart TVs
- Smart Speakers and Smart Displays
- Connected Cars
- Other Devices (Wearable devices, IoT, etc.)
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America held 38.40% of global market value in 2025. The region has high revenue per user and mature paid subscriber bases in the United States and Canada. Mexico's recorded-music market grew 13.3% in 2025. Spotify, Apple Music, Amazon Music, and YouTube Music use exclusive podcasts, hardware integration, and personalized features to compete in the United States. General Motors' multiyear Apple Music offer, Toyota's native Spotify access, and Volvo's Apple Music rollout link platform access to vehicle ownership. South America remains smaller, but Brazil grew 14.1% in 2025. Claro Musica uses carrier bundling and regional catalogs across Brazil, Argentina, and nearby markets.
Asia-Pacific is projected to be the fastest-growing region in the digital audio platforms market, with a 16.11% CAGR through 2031. India's paid music subscriber base grew 37% to 14.4 million in 2025 as lower prices and carrier bundles supported conversion. China grew 20.1% in 2025 and became the fourth-largest recorded-music market globally. Tencent Music Entertainment completed its USD 2.4 billion acquisition of Ximalaya in June 2026, extending its position in podcasts and audiobooks. Japan grew 8.9% in 2025, with demand for high-resolution audio supporting premium positioning. South Korea is also expanding the connected-car listening channel through Hyundai's platform. Europe grew 5.6% in 2025, while privacy rules are changing the design of advertising-supported offers.
The Middle East and Africa region grew, with Saudi Arabia and the UAE supporting consumption growth. Smartphone penetration above 90% across Gulf Cooperation Council markets supports direct app-based use. Regional carriers increasingly include audio services in premium postpaid packages. Anghami has used this carrier model to develop a regional subscriber base alongside global services. Boomplay has built a regional position through African catalogs, data-efficient streaming, and mobile money payments. Low revenue per user remains a constraint, but younger mobile-first users support longer-term volume growth for the digital audio platforms market.
- Spotify Technology S.A.
- Apple Inc.
- Amazon.com, Inc.
- Alphabet Inc.
- Tencent Music Entertainment Group
- Sirius XM Holdings Inc.
- Deezer S.A.
- SoundCloud Global Limited and Co. KG
- iHeartMedia, Inc.
- Anghami Plc
- JioSaavn LLC
- Gaana Media Private Limited
- NetEase Cloud Music Inc.
- TIDAL Music AS
- Qobuz SAS
- KKBOX Inc.
- Boomplay Music Group
- Claro Musica
- Napster Group PLC
- Yandex Music
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Subscription Price Rationalization in Emerging Economies
- 4.2.2 Telco OTT Bundling Pushes Paid Uptake
- 4.2.3 Rapid Smart Speaker Install Base Expansion
- 4.2.4 OEM-Level In-Car Streaming Integrations
- 4.2.5 AI Voice DJ and Generative Playlists Extend Daily Listening Time
- 4.2.6 Blockchain-Based Royalty Settlement Attracts Independent Catalogs
- 4.3 Market Restraints
- 4.3.1 Royalty-Rate Inflation Exceeding ARPU Growth
- 4.3.2 Content-License Windowing by Major Labels
- 4.3.3 Data-Privacy Regulations Limiting Ad-Targeting
- 4.3.4 Algorithmic Discovery Bias Marginalizing Long-Tail Creators
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Format Type
- 5.1.1 On-Demand Music Streaming
- 5.1.2 Live Internet Radio
- 5.1.3 Podcast Hosting
- 5.1.4 Audiobook Streaming
- 5.1.5 Other Format Types
- 5.2 By Monetization Model
- 5.2.1 Subscription-Based
- 5.2.2 Advertising-Based
- 5.2.3 Transaction-Based
- 5.2.4 Hybrid Model
- 5.2.5 Freemium Model
- 5.3 By Device
- 5.3.1 Smartphones and Tablets
- 5.3.2 Laptops and Desktops
- 5.3.3 Smart TVs
- 5.3.4 Smart Speakers and Smart Displays
- 5.3.5 Connected Cars
- 5.3.6 Other Devices (Wearable devices, IoT, etc.)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Argentina
- 5.4.2.3 Rest of South America
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 Asia-Pacific
- 5.4.4.1 China
- 5.4.4.2 India
- 5.4.4.3 Japan
- 5.4.4.4 South Korea
- 5.4.4.5 Australia and New Zealand
- 5.4.4.6 Rest of Asia-Pacific
- 5.4.5 Middle East
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Turkey
- 5.4.5.4 Rest of Middle East
- 5.4.6 Africa
- 5.4.6.1 South Africa
- 5.4.6.2 Nigeria
- 5.4.6.3 Rest of Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Spotify Technology S.A.
- 6.4.2 Apple Inc.
- 6.4.3 Amazon.com, Inc.
- 6.4.4 Alphabet Inc.
- 6.4.5 Tencent Music Entertainment Group
- 6.4.6 Sirius XM Holdings Inc.
- 6.4.7 Deezer S.A.
- 6.4.8 SoundCloud Global Limited and Co. KG
- 6.4.9 iHeartMedia, Inc.
- 6.4.10 Anghami Plc
- 6.4.11 JioSaavn LLC
- 6.4.12 Gaana Media Private Limited
- 6.4.13 NetEase Cloud Music Inc.
- 6.4.14 TIDAL Music AS
- 6.4.15 Qobuz SAS
- 6.4.16 KKBOX Inc.
- 6.4.17 Boomplay Music Group
- 6.4.18 Claro Musica
- 6.4.19 Napster Group PLC
- 6.4.20 Yandex Music
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


