

|
시장보고서
상품코드
2118965
OTT 시청자 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)OTT Audience Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, OTT 시청자 분석 시장 규모는 2025년 12억 5,000만 달러로 평가되었고, 2031년까지 29억 9,000만 달러로 추정되고, 2026-2031년 연평균 복합 성장률(CAGR)은 15.42%를 나타낼 것으로 예측됩니다.
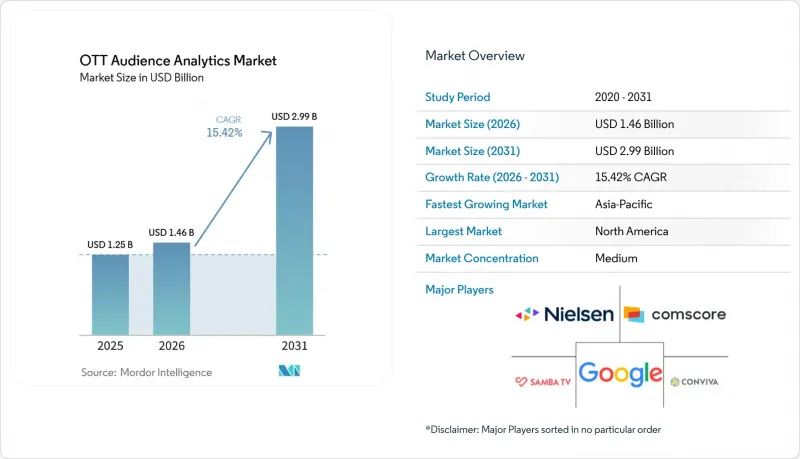
본 보고서는 분석 기능별(시청자 측정, 도달 범위 및 예측, 시청자 세분화 및 행동 분석, 컨텐츠 성과 및 편성 분석 등), 최종 사용자별(OTT 및 스트리밍 서비스 제공업체, 통신 사업자 및 유료 TV 사업자, 컨텐츠 소유자, 스튜디오, 저작권자 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 OTT 시청자 분석 시장 동향 및 인사이트
측정 가능한 커넥티드 TV 광고 슬롯으로의 광고 예산 이동
OTT 시청자 분석 시장은 기존 TV 예산이 커넥티드 TV 광고 슬롯으로 이동함에 따라 혜택을 보고 있습니다. 2026년에 커넥티드 TV 및 OTT에 대한 지출을 늘릴 계획인 광고주 중 54%는 자금원으로 기존 TV 예산의 재분배를, 40%는 인쇄 매체 및 라디오를, 25%는 신규 예산 증액을 꼽았습니다. 이러한 이전된 예산에는 시청자 도달, 브랜드 안전성, 캠페인 성과 측정에 대한 확립된 기대치가 수반됩니다. 분석 제공업체는 검증 및 어트리뷰션을 독립적인 보고서 제품이 아닌 업무 워크플로우의 일부로 통합해야 합니다. 이를 통해 캠페인 기간 동안의 가시성, 성과 및 오디언스 도달 범위를 기록할 수 있는 도구의 가치가 높아집니다. IAB의 ‘Open Measurement Software Development Kit’ 및 ‘SupplyChain’ 프레임워크는 디지털 비디오 공급망 전반에 걸쳐 보다 일관된 관리를 원하는 구매자에게 관련성이 높은 표준 규격입니다.
스트리밍의 세분화로 인해 통합된 오디언스 인텔리전스에 대한 수요가 증가하고 있습니다.
OTT 시청자 분석 시장은 수많은 스트리밍 서비스와 기기에 분산된 시청 동향을 반영해 나가고 있습니다. 단일 플랫폼에서는 자사 서비스 내 활동을 측정할 수 있지만, 광고주와 대행사 입장에서는 여전히 서비스 전반에 걸쳐 중복 제거된 시청자 데이터가 필요합니다. IAB의 ‘Project Eidos’는 공통된 분류 체계와 개인정보 보호를 고려한 측정 입력을 활용하는 상호 운용성이 높은 접근 방식을 통해, 채널 수준의 측정을 대체할 메커니즘 구축을 목표로 하고 있습니다. 이러한 수요로 인해 각 서비스를 고립된 환경으로 취급하지 않고 시청 데이터를 연동할 수 있는 제품에 대한 관심이 높아지고 있습니다. 패널을 통한 보정을 거친 크로스 디바이스 연동 기능을 갖추고, 시청자 데이터에 직접 접근할 수 있는 제공업체는 크로스 플랫폼 보고서 작성에 있어 보다 실용적인 기반을 제공할 수 있습니다. 반면, 주로 확률적 매칭에 의존하는 제공업체는 업계 인증 프로세스를 통해 연동 품질의 차이가 검증되게 될 경우 압박에 직면하게 될 것입니다.
개인정보 보호 규정 및 동의 관리의 복잡성
OTT 시청자 분석 시장에 영향을 미치는 개인정보 보호 및 동의 관련 요건으로 인해, 특히 유럽 및 신흥 시장에서 스트리밍 분석 제공업체가 수집하고 활용할 수 있는 데이터가 제한되고 있습니다. 이로 인해 시청자 모델에 활용할 수 있는 신호의 양이 감소할 가능성이 있으며, OTT 사업자에게는 도입이 더욱 복잡해질 우려가 있습니다. 소규모 제공업체는 다양한 관할권에 맞추어 제품과 거버넌스 프로세스를 조정해야 하므로, 규정 준수 부담이 더 커질 가능성이 있습니다. 이러한 영향은 벤더가 시청자 세분화에 기기 수준 또는 IP 기반 데이터를 활용하고자 할 때 특히 두드러집니다. 또한, 인도의 ‘디지털 개인 데이터 보호법’으로 인해 현지 및 지역 스트리밍 사업자에게 서비스를 제공하는 공급업체에게는 데이터 현지화와 관련된 고려 사항도 발생합니다. 따라서 OTT 시청자 분석 시장은 시청자 측정의 유용성을 유지하면서, 지역에 더 부합하는 데이터 관리 관행을 지원해야 합니다.
부문 분석
2025년 기준, ‘시청자 측정, 도달률, 예측’은 OTT 시청자 분석 시장 규모의 25.30%를 차지했습니다. 이 부문은 선형 TV 및 커넥티드 TV 협상에서 여전히 주요 측정 기반으로 자리 잡고 있습니다. 광고 대행사와 방송사는 계획 및 거래 워크플로우에서 수년 동안 도달률 기반 지표를 사용해 왔습니다. 고객이 성과 기반 측정 방식을 더 많이 채택하게 되었음에도 불구하고, 이러한 확립된 사용 방식은 계속되고 있습니다. ‘광고 시청자 및 캠페인 분석’ 부문은 2031년까지 연평균 성장률(CAGR) 15.85%로 확대될 것으로 예측됩니다. 이 부문은 커넥티드 TV의 프로그래매틱 구매 성숙화와 타겟팅, 검증, 캠페인 보고서에 대한 수요 증가의 혜택을 받고 있습니다.
2026년에는 커넥티드 TV 및 OTT 광고의 50%를 프로그래매틱 구매가 차지할 것으로 예상되며, 미디어 구매 워크플로우 내에서 작동하는 분석의 가치가 높아지고 있습니다. 컨텐츠 성과 및 프로그램 분석은 시청 완료율과 에피소드별 참여 데이터를 통해 계약 갱신, 공개 시기 설정, 배포에 관한 의사 결정을 지원합니다. ‘가입자 라이프사이클 및 유지 분석’은 플랫폼이 행동 패턴을 활용하여 시기적절한 유지 제안을 필요로 할 가능성이 있는 고객을 식별하는 데 도움이 됩니다. ‘시청자 세분화 및 행동 분석’은 광고주가 정의된 코호트에 접근할 수 있도록 지원하고, 컨텐츠 팀이 개인화 모델을 구축하는 데 도움을 줍니다. ‘제품 경험 및 오디언스 QoE 분석’은 라이브 스트리밍 및 FAST 서비스에서 전송 품질과 광고 가치가 연계됨에 따라 주목을 받고 있습니다. 또한 구매 담당자들은 미디어 기획, 구매 권장 사항, 인벤토리 발굴 분야에서 에이전트형 AI의 잠재적 활용 가능성을 발견하고 있으며, 이 모든 과정에는 구조화된 오디언스 데이터가 필요합니다.
지역별 분석
2025년, 북미는 OTT 시청자 분석 시장 점유율의 45.50%를 차지했습니다. 이 지역의 OTT 시청자 분석 시장에는 탄탄한 커넥티드 TV 광고 인프라가 구축되어 있으며, 측정, 어트리뷰션, 시청자 검증 도구의 구매가 빈번하게 이루어지고 있습니다. 합동 산업 위원회(Joint Industry Committee)는 2025년부터 2026년 방송 시즌에 걸쳐 Comscore, iSpot, VideoAmp를 대체 측정 기준으로 인증하여 구매자가 이용할 수 있는 측정 옵션의 폭을 넓혔습니다. 캐나다와 멕시코에서는 스트리밍 플랫폼이 현지 사업을 확장하고 현지 시청자 측정이 필요함에 따라 수요가 증가하고 있습니다.
2025년, 유럽은 OTT 시청자 분석 시장에서 두 번째로 큰 지역 기여도를 보였습니다. 이러한 수요는 스트리밍 이용의 성숙도에 힘입고 있지만, 개인정보 보호 요건으로 인해 데이터 수집 비용과 복잡성이 증가할 가능성이 있습니다. 독일에서는 ‘통신 및 디지털 서비스 데이터 보호법’ 제25조에 따라 특정 클라이언트 측 분석 추적에 대해 사전 동의가 의무화되어 있습니다. 유럽의 분석 제공업체들은 측정 범위와 각국 시장의 거버넌스 요건 간의 균형을 맞추어야 합니다.
아시아태평양은 2031년까지 연평균 성장률(CAGR) 15.89%로 확대될 것으로 예상되며, OTT 시청자 분석 시장에서 가장 빠르게 성장하는 지역이 될 것입니다. 이러한 성장의 배경에는 대규모 스트리밍 시청자 기반과 온라인 동영상 수익의 지속적인 성장이 있습니다. 인도의 개인정보 보호 체계에서는 공급업체가 현지에서의 데이터 처리를 고려할 것을 요구하고 있으며, 이는 현지에서 사업을 전개할 수 있는 능력을 갖춘 제공업체에게 유리하게 작용할 가능성이 있습니다. 중국에서는 동영상, 메시징, 결제 활동이 결합된 독자적인 데이터 환경이 형성되어 있습니다. 남미에서는 스트리밍 수익이 증가하고 유료 TV의 상대적 중요성이 낮아짐에 따라 수요가 높아지고 있습니다. 중동 및 아프리카는 여전히 초기 단계 시장이며, 정부 산하 미디어 플레이어, 통신 사업자의 번들 서비스, 그리고 인프라 구축 현황의 편차가 분석 도구 도입 속도를 좌우하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.01According to Mordor Intelligence, the OTT audience analytics market size is projected to grow from USD 1.25 billion in 2025 to USD 2.99 billion by 2031, at a CAGR of 15.42% from 2026 to 2031.
This report is Segmented by Analytics Capability (Audience Measurement, Reach, and Forecasting, Audience Segmentation and Behavioral Analytics, Content Performance and Programming Analytics, and More), End User (OTT and Streaming Service Providers, Telecom and Pay-TV Operators, Content Owner, Studios, and Rights Holder, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global OTT Audience Analytics Market Trends and Insights
Migration of Advertising Budgets Toward Measurable Connected TV Inventory
The OTT audience analytics market is gaining from a shift of linear television budgets into connected TV inventory. Among advertisers that plan to increase connected TV and OTT spending in 2026, 54% identified linear TV reallocation as the funding source, while 40% cited print and radio and 25% cited new budget growth. Those transferred budgets bring established expectations around audience delivery, brand safety, and campaign accountability. Analytics providers need to make verification and attribution part of the operating workflow rather than separate reporting products. This raises the value of tools that can document viewability, outcomes, and audience delivery during a campaign. The IAB's Open Measurement Software Development Kit and SupplyChain framework are relevant standards for buyers that want more consistent controls across the digital video supply chain.
Streaming Fragmentation Increasing Demand for Unified Audience Intelligence
The OTT audience analytics market is responding to viewing that is spread across many streaming services and devices. A single platform can measure activity within its own service, but advertisers and agencies still need deduplicated views of audiences across services. The IAB's Project Eidos seeks to replace channel-level measurement with more interoperable approaches that use shared taxonomies and privacy-resilient measurement inputs. This need puts greater emphasis on products that can connect viewing data without treating each service as an isolated environment. Providers with panel-calibrated cross-device linkage and direct access to viewership data can offer a more usable basis for cross-platform reporting. Providers relying mainly on probabilistic matching face pressure when differences in linkage quality can be tested through industry certification processes.
Privacy Regulation and Consent-Governance Complexity
Privacy and consent requirements affecting the OTT audience analytics market limit the data that streaming analytics providers can collect and use, particularly in Europe and emerging markets. This can reduce the volume of usable signals for audience models and make deployment more complex for OTT operators. Smaller providers can face greater compliance burdens because they must adapt products and governance processes for different jurisdictions. The effect is especially important where vendors want to use device-level or IP-derived data for audience segmentation. India's Digital Personal Data Protection Act also creates data-localization considerations for providers serving local and regional streaming operators. The OTT audience analytics market must therefore support more localized data practices while preserving the utility of audience measurement.
Other drivers and restraints analyzed in the detailed report include:
- AI-Enabled Personalization and Predictive Churn Management
- Real-Time Quality-of-Experience Signals Becoming Commercial KPIs
- Fragmented Identity, Measurement, and Interoperability Standards
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Audience Measurement, Reach and Forecasting held 25.30% of the OTT audience analytics market size in 2025. The segment remains the primary measurement foundation for linear television and connected TV negotiations. Agencies and broadcasters have long used reach-based measures in planning and trading workflows. This established use continues even as customers adopt more outcome-based measurement approaches. Advertising Audience and Campaign Analytics is projected to expand at a 15.85% CAGR through 2031. The segment benefits from the maturation of programmatic connected TV buying and the demand for targeting, verification, and campaign reporting.
Programmatic buying accounted for 50% of connected TV and OTT advertising in 2026, placing greater value on analytics that can operate within media buying workflows. Content Performance and Programming Analytics supports decisions on renewal, windowing, and distribution through completion and episode-level engagement data. Subscriber Lifecycle and Retention Analytics helps platforms use behavior patterns to identify customers who may need timely retention offers. Audience Segmentation and Behavioral Analytics helps advertisers address defined cohorts and helps content teams construct personalization models. Product Experience and Audience QoE Analytics is gaining attention as live and FAST services connect delivery quality with advertising value. Buyers also see potential uses for agentic AI in media planning, buying recommendations, and inventory discovery, all of which require structured audience data.
Complete Report Scope:
- By Analytics Capability
- Audience Measurement, Reach, and Forecasting
- Audience Segmentation and Behavioural Analytics
- Content Performance and Programming Analytics
- Advertising Audience and Campaign Analytics
- Subscriber Lifecycle and Retention Analytics
- Product Experience and Audience QoE Analytics
- By End User
- OTT and Streaming Service Providers
- Broadcasters, Networks, and FAST Operators
- Advertisers and Media Agencies
- Content Owners, Studios, and Rights Holders
- Telecom and Pay-TV Operators
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East
- Turkey
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America accounted for 45.50% of the OTT audience analytics market share in 2025. The OTT audience analytics market in the region has extensive connected TV advertising infrastructure and frequent purchasing of measurement, attribution, and audience verification tools. The Joint Industry Committee certified Comscore, iSpot, and VideoAmp as alternative currencies for the 2025-2026 broadcast season, expanding the range of measurement options used by buyers. Canada and Mexico add demand as streaming platforms increase their local operations and need local audience measurement.
Europe was the second-largest regional contributor to the OTT audience analytics market in 2025. Its demand is supported by mature streaming use, although privacy requirements can raise the cost and complexity of data collection. Germany requires prior consent for certain client-side analytics tracking under Section 25 of the Telecommunications Digital Services Data Protection Act. Analytics providers in Europe must balance measurement coverage with the governance requirements of individual national markets.
Asia-Pacific is projected to expand at a 15.89% CAGR through 2031, making it the fastest-growing region in the OTT audience analytics market. Its scale comes from a large streaming viewer base and continuing growth in online video revenue. India's privacy framework requires vendors to consider localized data processing, which can favor providers with local operating capabilities. China uses a distinct data environment that combines video, messaging, and payment activity. South America offers growing demand as streaming revenue rises and pay television loses relative importance. The Middle East and Africa remain earlier-stage opportunities, where government-linked media entities, telecom bundles, and uneven infrastructure shape the pace of analytics adoption.
- The Nielsen Company
- Comscore, Inc.
- Kantar Media Audiences Limited
- Samba TV, Inc.
- iSpot.tv, Inc.
- TVision Insights, Inc.
- Google LLC
- Adobe Inc.
- Oracle Corporation
- Conviva Inc.
- NicePeopleAtWork S.L.
- Amagi Corporation
- Parrot Analytics Limited
- RealityMine Limited
- MediaMelon, Inc.
- Innovid Corp.
- Roku, Inc.
- Xperi Inc.
- Akamai Technologies, Inc.
- Brightcove Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Impact of Macroeconomic Factors on the Market
- 4.3 Market Drivers
- 4.3.1 Migration of Advertising Budgets Toward Measurable Connected-TV Inventory
- 4.3.2 Streaming Content Fragmentation Increasing Demand for Unified Audience Intelligence
- 4.3.3 AI-Enabled Personalization and Predictive Churn Management
- 4.3.4 Real-Time Quality-of-Experience Signals Becoming Commercial KPIs
- 4.3.5 Cross-Market Content Planning Using Anonymized Viewing Logs
- 4.3.6 Attention-Based and Outcome-Based Measurement Currencies
- 4.4 Market Restraints
- 4.4.1 Privacy Regulation and Consent-Governance Complexity
- 4.4.2 Fragmented Identity, Measurement, and Interoperability Standards
- 4.4.3 High-Cardinality Data and Edge-Processing Cost
- 4.4.4 Limited Access to Walled-Garden and Platform-Native Signals
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Suppliers
- 4.8.3 Bargaining Power of Buyers
- 4.8.4 Threat of Substitutes
- 4.8.5 Rivalry Among Existing Competitors
- 4.9 Pricing Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Analytics Capability
- 5.1.1 Audience Measurement, Reach, and Forecasting
- 5.1.2 Audience Segmentation and Behavioural Analytics
- 5.1.3 Content Performance and Programming Analytics
- 5.1.4 Advertising Audience and Campaign Analytics
- 5.1.5 Subscriber Lifecycle and Retention Analytics
- 5.1.6 Product Experience and Audience QoE Analytics
- 5.2 By End User
- 5.2.1 OTT and Streaming Service Providers
- 5.2.2 Broadcasters, Networks, and FAST Operators
- 5.2.3 Advertisers and Media Agencies
- 5.2.4 Content Owners, Studios, and Rights Holders
- 5.2.5 Telecom and Pay-TV Operators
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 South America
- 5.3.2.1 Brazil
- 5.3.2.2 Argentina
- 5.3.2.3 Rest of South America
- 5.3.3 Europe
- 5.3.3.1 United Kingdom
- 5.3.3.2 Germany
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 Asia-Pacific
- 5.3.4.1 China
- 5.3.4.2 Japan
- 5.3.4.3 India
- 5.3.4.4 South Korea
- 5.3.4.5 Australia and New Zealand
- 5.3.4.6 Rest of Asia-Pacific
- 5.3.5 Middle East
- 5.3.5.1 Turkey
- 5.3.5.2 Saudi Arabia
- 5.3.5.3 United Arab Emirates
- 5.3.5.4 Rest of Middle East
- 5.3.6 Africa
- 5.3.6.1 South Africa
- 5.3.6.2 Nigeria
- 5.3.6.3 Egypt
- 5.3.6.4 Rest of Africa
- 5.3.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Positioning Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 The Nielsen Company
- 6.4.2 Comscore, Inc.
- 6.4.3 Kantar Media Audiences Limited
- 6.4.4 Samba TV, Inc.
- 6.4.5 iSpot.tv, Inc.
- 6.4.6 TVision Insights, Inc.
- 6.4.7 Google LLC
- 6.4.8 Adobe Inc.
- 6.4.9 Oracle Corporation
- 6.4.10 Conviva Inc.
- 6.4.11 NicePeopleAtWork S.L.
- 6.4.12 Amagi Corporation
- 6.4.13 Parrot Analytics Limited
- 6.4.14 RealityMine Limited
- 6.4.15 MediaMelon, Inc.
- 6.4.16 Innovid Corp.
- 6.4.17 Roku, Inc.
- 6.4.18 Xperi Inc.
- 6.4.19 Akamai Technologies, Inc.
- 6.4.20 Brightcove Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


