

|
시장보고서
상품코드
2123138
시청자 분석 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Audience Analytics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
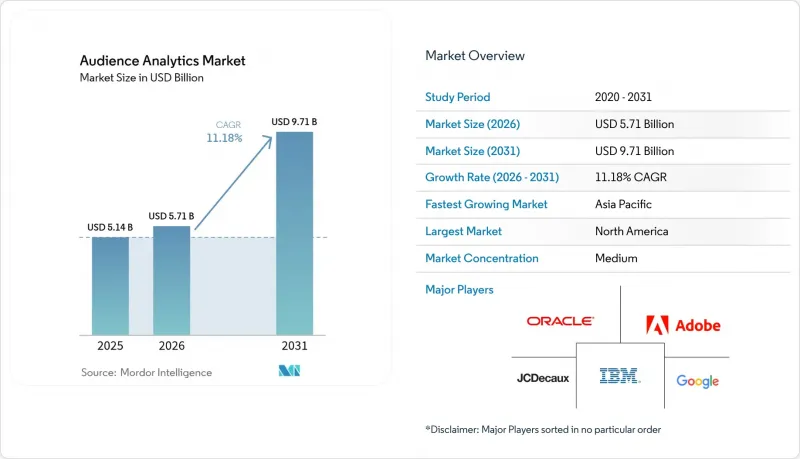
에 의하면, 시청자 분석 시장 규모는 2025년에 51억 4,000만 달러로 평가되었고, 2026년 57억 1,000만 달러에서 2031년까지 97억 1,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 11.18%를 나타낼 전망입니다.
본 보고서는 구성 요소별(솔루션 및 서비스), 도입 형태별(온프레미스 및 클라우드), 조직 규모별(대기업 및 중소기업(SME)), 용도별(영업·마케팅 최적화, 고객 경험 관리 등), 최종 사용자 산업별(미디어 및 엔터테인먼트, 소매 및 전자상거래 등), 그리고 지역별로 분류되어 있습니다.
세계의 시청자 분석 시장 동향 및 인사이트
옴니채널에서의 퍼스트파티 데이터 수집이 급속히 확대되고 있습니다.
각 브랜드는 자사가 보유한 상호작용 지점을 중심으로 데이터 아키텍처를 재구축하여 매장 내 행동, 모바일 참여도, 연결된 기기에서 발생하는 신호를 통합하고 있습니다. 소매업체들은 현재 오프라인 매장과 디지털 고객 경험을 연계하는 정교한 미디어 네트워크를 운영하고 있으며, 과거에는 제3자 데이터 브로커가 지배하던 수백만 달러 규모의 수익 채널을 개척하고 있습니다. 오프라인과 온라인 인사이트를 통합하는 능력을 통해 평생 가치(LTV) 모델링이 개선되고, 세분화 정확도가 향상됩니다.
AI/ML을 활용한 예측 분석 도입 급증
현재 주요 플랫폼 전반에 걸쳐 행동 모델링, 전환 예측 및 자동화된 코호트 생성의 기반으로서 머신러닝 알고리즘이 활용되고 있습니다. Google Analytics 4와 Adobe Experience Cloud는 인사이트 확보 지연을 몇 주에서 몇 분으로 단축하면서 예측 정확도를 30% 이상 향상시키는 AI 엔진을 탑재하고 있습니다. 클라우드를 통한 제공으로, 그동안 인프라 비용이나 인력 부족으로 제약을 받았던 중견 기업도 이러한 기능을 이용할 수 있게 되었습니다.
개인정보 보호를 우선시하는 규제 강화
GDPR(EU 개인정보보호규정), CPRA 및 디지털 시장법으로 인해 기업들은 데이터 흐름을 재설계할 수밖에 없게 되었으며, 많은 경우 분석 예산의 15-20%를 규정 준수 대책에 할당해야만 합니다. 쿠키 없는 웹 분석과 같은 개인정보 보호 솔루션은 행동 인사이트의 품질을 유지하면서 개인 식별자에 대한 의존도를 낮춥니다. 각 벤더들은 규제 요건과 상업적 목표 간의 균형을 맞추기 위해 컨텍스트 타겟팅 및 엣지 처리를 내세우고 있습니다.
부문 분석
솔루션은 2025년 매출의 67.20%를 차지했으며, 시청자 분석 시장의 중추적인 역할을 계속하고 있습니다. 여기에는 크로스 채널 인사이트 생성을 가능하게 하는 데이터 통합 허브, 고객 데이터 플랫폼, AI 추론 엔진이 포함됩니다. 기업은 초기 단계에서 확장성이 뛰어난 인프라에 막대한 투자를 하기 때문에 전환 비용이 높게 발생하며, 벤더와의 관계가 공고해집니다. 그러나 기업이 신원 관리, 모델 거버넌스, 규정 준수 감사에 대한 전문 지식을 외부에 위탁함에 따라 서비스 부문은 연평균 성장률(CAGR) 12.45%를 달성하고 있습니다. 매니지드 서비스는 지속적인 최적화를 실현하고 데이터 엔지니어링 인력 부족을 보완함으로써 프로젝트 전반의 성공률을 높이고 있습니다.
애널리틱스-어즈-어-서비스(AaaS)의 부상은 영구 라이선스에서 종량제 계약으로의 전략적 전환을 나타냅니다. 컨설팅 회사와 시스템 통합사업자는 기술 스택에 자문 지원을 결합함으로써 비즈니스 목표에 기반한 도입 선택을 보장하고 있습니다. 개인정보 보호 규제가 엄격해지는 가운데, 동의 관리 및 엣지 배포에 특화된 서비스는 프리미엄 가격을 책정하고 있으며, 수익 구조가 지속적인 전문 지원으로 전환되는 움직임을 가속화하고 있습니다.
2025년, 시청자 분석 시장에서 온프레미스 시스템의 점유율은 65.10%를 차지했으며, 이는 데이터 주권과 대용량 스트리밍 분석 시 발생하는 지연에 대한 뿌리 깊은 우려를 반영하고 있습니다. 은행 및 정부 등 일부 부문에서는 기밀성이 높은 개인 식별 정보를 보유하기 위해 자체 호스팅형 플랫폼에 의존하고 있습니다. 그럼에도 불구하고, 각 벤더들이 지역별 암호화, 주권 클라우드 옵션, 고급 규정 준수 인증을 도입함에 따라 클라우드 인스턴스는 연평균 성장률(CAGR) 12.84%로 성장하고 있습니다. Adobe와 AWS의 공동 솔루션은 실시간 고객 프로파일링을 위한 맞춤형 클라우드 솔루션의 한 예입니다.
하이브리드 아키텍처가 주류 모델로 부상하면서, 중요한 고객 프로파일은 온프레미스에 보관하고, 컴퓨팅 부하가 높은 워크로드는 클라우드로 버스트 처리하고 있습니다. 이러한 구성을 통해 인프라에 대한 자본 투자를 억제하면서도, 계절적 캠페인이나 데이터 수집의 급격한 증가에 대응할 수 있는 탄력적인 처리가 가능해집니다. 퍼블릭 클라우드 보안에 대한 신뢰가 높아짐에 따라, 클라우드 도입에 따른 시청자 분석 시장 규모는 2030년 이후 온프레미스 매출을 넘어설 것으로 예측됩니다.
지역별 분석
북미는 2025년에 매출의 39.90%를 차지한 것으로 평가되었으며, 그 배경에는 정교한 광고 생태계, 막대한 기술 투자, 그리고 프라이버시 우선형 도구의 조기 도입이 있습니다. 월마트나 타겟과 같은 미국 소매업체들이 리테일 미디어의 수익 창출을 주도하는 한편, 캐나다는 기업을 규정 준수 분석 아키텍처로 이끄는 선진적인 개인정보 보호법의 혜택을 받고 있습니다. 멕시코에서 전자상거래의 확산이 가속화되면서, 확장 가능하고 클라우드를 통해 제공되는 인사이트 엔진의 지역 사용자 기반이 확대되고 있습니다.
유럽은 GDPR(EU 개인정보보호규정) 및 디지털 시장법(DMA)의 영향으로 꾸준한 성장 단계에 있습니다. 이러한 요인들은 개인 데이터에 대한 의존도를 최소화하는 동의 기반 솔루션에 대한 수요를 높이고 있습니다. 독일과 영국은 데이터를 국내에 보관하고 국경을 넘는 전송의 복잡성을 줄이는 엣지 처리 시범 사업을 추진하고 있습니다. 프랑스와 이탈리아는 광고 효율성을 유지하기 위해 컨텍스트 타겟팅을 모색하고 있습니다. 여러 ID 프레임워크 간 상호 운용이 가능한 독립 벤더들은 유연한 규정 준수를 추구하는 중견 기업 도입자들을 끌어들이고 있습니다.
아시아태평양은 8,800억 달러 규모의 모바일 경제와 18억 명의 모바일 가입자에 힘입어 연평균 성장률(CAGR) 11.96%를 기록하며 가장 빠르게 성장하는 지역입니다. 중국은 동영상, 메시징, 결제를 융합한 소셜 커머스 분석을 선도하며, 세밀한 실시간 인사이트 스트림을 창출하고 있습니다. 인도의 핀테크 붐으로 거래 데이터 세트가 확대되는 한편, 일본과 한국에서는 사용자 분석을 게임 생태계에 통합하여 사용자 유지율을 최적화하고 있습니다. 호주 및 뉴질랜드에서는 옴니채널 소매 및 공공 서비스의 현대화를 지원하기 위해 엔터프라이즈 애널리틱스가 도입되고 있습니다. 스마트폰 보급률 상승과 정부의 디지털화 노력이 동남아시아 전역에서 추가적인 수요를 견인하며, 오디언스 애널리틱스 시장의 장기적인 성장 모멘텀을 뒷받침하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.07According to Mordor Intelligence, the audience analytics market size was valued at USD 5.14 billion in 2025 and estimated to grow from USD 5.71 billion in 2026 to reach USD 9.71 billion by 2031, at a CAGR of 11.18% during the forecast period (2026-2031).
This report is Segmented by Component (Solutions and Services), Deployment Mode (On-Premises and Cloud), Organization Size (Large Enterprises and Small and Medium Enterprises (SMEs)), Application (Sales and Marketing Optimisation, Customer Experience Management, and More), End-User Industry (Media and Entertainment, Retail and ECommerce, and More), and Geography.
Global Audience Analytics Market Trends and Insights
Rapid Growth in Omnichannel First-Party Data Collection
Brands are rebuilding data architectures around owned interaction points, integrating in-store behaviour, mobile engagement, and connected-device signals. Retailers now operate sophisticated media networks that align physical and digital journeys, opening USD-level revenue channels once dominated by third-party data brokers. The ability to merge offline and online insights improves lifetime value modelling and elevates segmentation precision.
Surging Adoption of AI/ML-Powered Predictive Analytics
Machine-learning algorithms now underpin behavioural modelling, conversion prediction, and automated cohort creation across mainstream platforms. Google Analytics 4 and Adobe Experience Cloud showcase AI engines that slash insight latency from weeks to minutes while improving forecast accuracy by more than 30%. Cloud delivery makes these functions accessible to mid-market firms previously constrained by infrastructure costs and talent shortages.
Increasing Privacy-First Regulation
GDPR, CPRA, and the Digital Markets Act compel firms to re-engineer data flows, often diverting 15-20% of analytics budgets to compliance efforts. Privacy-preserving solutions, such as cookieless web analytics, reduce dependence on personal identifiers while sustaining behavioural insight quality. Vendors tout contextual targeting and edge processing to balance regulatory demands with commercial goals.
Other drivers and restraints analyzed in the detailed report include:
- Media and Entertainment Shift to Real-Time Audience Monetisation
- Cookieless Marketing Pushes Demand for Consent-Based Identity Graphs
- Data-Engineering Skill Shortages Among SME Users
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions generated 67.20% of 2025 revenue and remain the backbone of the audience analytics market. They comprise data-integration hubs, customer data platforms, and AI inference engines that enable cross-channel insight generation. Organisations invest heavily at the outset in scalable infrastructures, creating high switching costs and entrenched vendor relationships. Services, however, achieve a 12.45% CAGR as firms outsource expertise in identity resolution, model governance, and compliance auditing. Managed offerings deliver continuous optimisation and bridge the data-engineering talent gap, elevating overall project success rates.
The rise of analytics-as-a-service signals a strategic shift from perpetual licences to consumption-based engagements. Consultancies and system integrators package technology stacks with advisory support, ensuring business objectives drive implementation choices. As privacy regulation tightens, specialised services in consent management and edge deployment command premium pricing, accelerating the revenue mix transition toward recurring professional support.
On-premises systems held 65.10% of the audience analytics market share in 2025, reflecting enduring concerns over data sovereignty and latency for high-volume streaming analyses. Sectors such as banking and government rely on self-hosted platforms to retain sensitive personally identifiable information. Nevertheless, cloud instances grow at a 12.84% CAGR as vendors implement region-specific encryption, sovereign-cloud options, and advanced compliance certifications. Adobe's joint offering with AWS exemplifies tailored cloud solutions for real-time customer profiling.
Hybrid architectures surface as the prevailing model, retaining golden customer profiles on-premises while bursting compute-intensive workloads to the cloud. This arrangement curbs infrastructure capital expenditure and unlocks elastic processing for seasonal campaigns and sudden surges in data ingestion. The audience analytics market size represented by cloud deployments is forecast to overtake on-premises revenue in the post-2030 horizon as confidence in public-cloud security matures.
Complete Report Scope:
- By Component
- Solutions
- Services
- By Deployment Mode
- On-premises
- Cloud
- By Organisation Size
- Large Enterprises
- Small and Medium Enterprises (SMEs)
- By Application
- Sales and Marketing Optimisation
- Customer Experience Management
- Competitive/Media Intelligence
- Product and Content Development
- Fraud and Risk Analytics
- By End-user Industry
- Media and Entertainment
- Retail and eCommerce
- BFSI
- Telecom and IT
- Healthcare and Life Sciences
- Government and Public Sector
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 39.90% revenue in 2025, anchored by a sophisticated advertising ecosystem, heavy technology investment, and early adoption of privacy-first tools. United States retailers such as Walmart and Target lead in retail media revenue generation, while Canada benefits from progressive privacy laws that nudge firms toward compliant analytics architectures. Mexico's accelerating e-commerce adoption widens the regional user base for scalable, cloud-delivered insight engines.
Europe sits in a steady growth phase shaped by GDPR and the Digital Markets Act, which elevate demand for consent-based solutions that minimise personal data dependence. Germany and the United Kingdom endorse edge-processing pilots that keep data resident, reducing cross-border transfer complexity. France and Italy explore contextual targeting to maintain advertising efficiency. Independent vendors that can interoperate across multiple identity frameworks attract mid-market adopters seeking flexible compliance.
Asia-Pacific is the fastest-growing region at a 11.96% CAGR, supported by a USD 880 billion mobile economy and 1.8 billion mobile subscribers. China pioneers social commerce analytics that blend video, messaging, and payments, creating granular, real-time insight streams. India's fintech boom expands transactional datasets, while Japan and South Korea integrate audience analytics into gaming ecosystems to optimise retention. Australia and New Zealand embrace enterprise analytics to support omnichannel retail and public-service modernisation. Rising smartphone penetration and government digital initiatives propel additional demand across Southeast Asia, reinforcing long-term momentum for the audience analytics market.
- Adobe Inc.
- Oracle Corporation
- Google LLC
- International Business Machines Corp.
- comScore, Inc.
- SAS Institute Inc.
- Microsoft Corp.
- Amazon Web Services, Inc.
- Salesforce, Inc.
- Nielsen Holdings Plc
- JCDecaux Group
- Akamai Technologies, Inc.
- Cxense ASA
- Meltwater
- Audiense Ltd.
- Upwave
- Mixpanel, Inc.
- Amplitude, Inc.
- Chartbeat, Inc.
- Piwik PRO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid growth in omnichannel first-party data collection
- 4.2.2 Surging adoption of AI/ML-powered predictive analytics
- 4.2.3 Media and entertainment shift to real-time audience monetisation
- 4.2.4 Cookieless marketing pushes demand for consent-based identity graphs
- 4.2.5 Retail media networks scaling first-party shopper insights
- 4.2.6 Edge analytics on devices enabling privacy-preserving insights
- 4.3 Market Restraints
- 4.3.1 Increasing privacy-first regulation (GDPR, CPRA, DMA)
- 4.3.2 Data-engineering skill shortages among SME users
- 4.3.3 Rising cloud-compute costs for petabyte-scale analytics workloads
- 4.3.4 Fragmentation of identity solutions hinders interoperability
- 4.4 Value Chain Analysis
- 4.5 Technological Outlook
- 4.6 Regulatory Landscape
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of the Impact of Macroeconomic Trends on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.2 Services
- 5.2 By Deployment Mode
- 5.2.1 On-premises
- 5.2.2 Cloud
- 5.3 By Organisation Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises (SMEs)
- 5.4 By Application
- 5.4.1 Sales and Marketing Optimisation
- 5.4.2 Customer Experience Management
- 5.4.3 Competitive/Media Intelligence
- 5.4.4 Product and Content Development
- 5.4.5 Fraud and Risk Analytics
- 5.5 By End-user Industry
- 5.5.1 Media and Entertainment
- 5.5.2 Retail and eCommerce
- 5.5.3 BFSI
- 5.5.4 Telecom and IT
- 5.5.5 Healthcare and Life Sciences
- 5.5.6 Government and Public Sector
- 5.5.7 Others
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Russia
- 5.6.2.7 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia and New Zealand
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 Saudi Arabia
- 5.6.5.1.2 United Arab Emirates
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Adobe Inc.
- 6.4.2 Oracle Corporation
- 6.4.3 Google LLC
- 6.4.4 International Business Machines Corp.
- 6.4.5 comScore, Inc.
- 6.4.6 SAS Institute Inc.
- 6.4.7 Microsoft Corp.
- 6.4.8 Amazon Web Services, Inc.
- 6.4.9 Salesforce, Inc.
- 6.4.10 Nielsen Holdings Plc
- 6.4.11 JCDecaux Group
- 6.4.12 Akamai Technologies, Inc.
- 6.4.13 Cxense ASA
- 6.4.14 Meltwater
- 6.4.15 Audiense Ltd.
- 6.4.16 Upwave
- 6.4.17 Mixpanel, Inc.
- 6.4.18 Amplitude, Inc.
- 6.4.19 Chartbeat, Inc.
- 6.4.20 Piwik PRO
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment


