|
시장보고서
상품코드
2119351
태양광 인버터 배터리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Solar Inverter Battery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
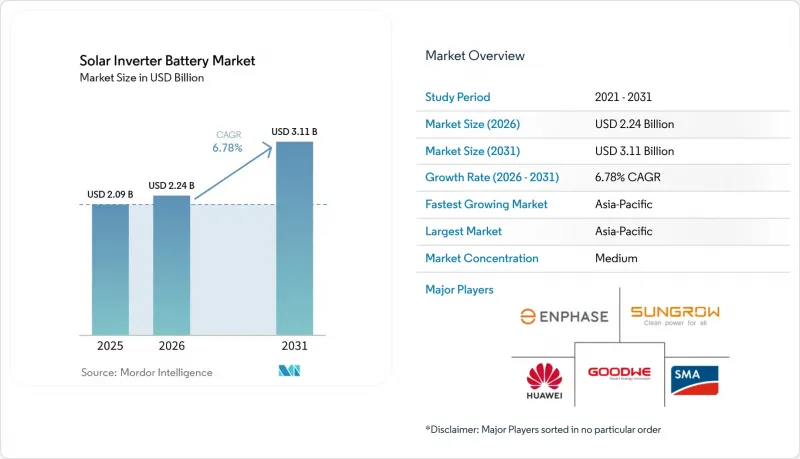
에 의하면, 태양광 인버터 배터리 시장 규모는 2025년 20억 9,000만 달러로 평가되었습니다. 2026년 22억 4,000만 달러에서 2031년까지 31억 1,000만 달러로 확대되고 2026년부터 2031년까지 연평균 복합 성장률(CAGR)은 6.78%를 나타낼 전망입니다.
본 보고서는 배터리의 화학적 구성(리튬 이온, 납산, 나트륨 이온, 흐름 전지, 기타), 배터리 용량(5kWh 미만, 5-10kWh, 10-20kWh, 20kWh 이상),최종 사용자(주거용, 상업용, 산업용, 유틸리티 규모), 지역(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(미 달러) 기준으로 제시되어 있습니다.
세계의 태양광 인버터 배터리 시장 동향 및 인사이트
태양광 발전과 에너지 저장 시스템의 병용 도입으로 도입률 상승
에너지 저장 시스템이 신규 태양광 발전 프로젝트의 표준 구성 요소로 자리 잡음에 따라, 태양광 인버터 배터리 시장은 혜택을 보고 있습니다. 미국의 주거용 태양광 에너지 저장 시스템 도입률은 2025년 1분기 38%에서 2026년 1분기에는 45%에 달했습니다. 이러한 변화는 넷 미터링 제도의 재검토와 더불어, 태양광 발전으로 얻은 전력을 나중에 활용하기 위해 더 많이 저장하고자 하는 고객의 관심이 높아진 것을 반영합니다. SEIA 보고서에 따르면, 미국에서는 2025년에 58 GWh의 에너지 저장 용량이 추가되었습니다. 통합 시스템의 경우, 공급업체가 인버터 제어, 배터리 관리, 설치 설계를 조율해야 합니다. 따라서 개별 하드웨어 부품이 아닌 완전한 시스템을 제공할 수 있는 기업이 유리합니다.
리튬이온 시스템의 비용 하락이 보급을 촉진
태양광 인버터 배터리 시장은 인산철리튬(LFP) 셀의 비용 감소로 인해 혜택을 보고 있습니다. 2025년 LFP 셀 가격은 1kWh당 약 50달러였으며, 이로 인해 주거용 시스템은 전기 요금이 높은 유럽이나 호주 시장에서도 경쟁력을 발휘할 수 있게 되었습니다. 2026년 상반기에 314Ah급 축전 셀 가격이 상승했음에도 불구하고, 태양광 인버터 배터리 시장의 상업 프로젝트에 대한 경제적 타당성은 훼손되지 않았습니다. Sungrow는 2026년 6월, 314 Ah 프리즘형 셀과 모듈 수준의 DC-DC 변환 기능을 갖춘 ‘PowerHarbor’를 발표했습니다. 이 설계는 시스템 전체의 비용 절감과 용량 증설을 간소화하는 것을 목표로 합니다. 다만, 국가 송전망 및 안전 규정의 적용을 받는 소규모 설치 업체의 경우, 인증 비용이 여전히 비용 절감의 걸림돌이 되고 있습니다.
높은 초기 비용이 신흥 지역에서의 보급을 저해하고 있습니다.
소비자 대상 대출이나 설치 업체의 수용 능력이 제한적인 지역에서는 태양광 인버터 배터리 시장 진출이 여전히 어려운 상황입니다. 셀 가격 하락에도 불구하고 설비, 설치 및 자금 조달에 드는 총비용 문제는 해결되지 않았습니다. 브라질에서는 2026년 1월 기준으로 500 MWh를 초과하는 계량기 후방 축전 시스템이 도입되어 있으며, 2026년 중에 650 MWh 이상이 추가로 도입될 것으로 예상되었습니다. 브라질 전력 규제 당국은 2026년에 ‘Consulta Publica 39’를 재검토하고 있으며, 이를 통해 에너지 저장 시스템의 비즈니스 모델이 명확해질 가능성이 있습니다. 올인원형 장비는 태양광 인버터 배터리 시장에서 시운전 기간을 단축할 수 있지만, 설치 업체 네트워크가 제한적인 시장에서는 인건비를 완전히 상쇄할 수는 없습니다. 이러한 제약은 기업 고객의 대용량 시스템 구매에도 영향을 미치고 있습니다.
부문 분석
2025년, 리튬 이온 배터리는 태양광 인버터 배터리 시장에서 72.1%의 점유율을 차지했습니다. 이 점유율의 대부분은 LFP 제품이 차지하고 있는데, 이는 주거용 에너지 저장 분야에서 확립된 공급망과 검증된 성능을 갖추고 있기 때문입니다. 그 작동 범위, 셀 수준의 안전 특성, 그리고 표준 배터리 관리 시스템과의 호환성은 인증된 시스템에서의 사용을 뒷받침하고 있습니다. 납축전지는 비용 효율성이 중요한 용도에서 여전히 일정한 역할을 하고 있습니다. 흐름 전지는 설치의 복잡성과 자본 수요로 인해 보급이 제한되고 있는 일부 장기 상업 및 산업 프로젝트에서 계속해서 사용되었습니다.
나트륨 이온 배터리는 2026년부터 2031년까지 연평균 성장률(CAGR) 9.1%를 나타낼 것으로 예측됩니다. CATL은 자사의 나트륨 이온 셀이 97%의 시스템 효율을 달성하며, 용량의 80%까지 1만 5,000사이클 이상 지속 가능하다고 밝혔습니다. 이 회사의 셀 설계는 코발트, 니켈, 구리를 사용하지 않기 때문에 생산량이 증가하더라도 비용 경쟁력을 유지할 수 있습니다. Alfen사와 CATL사는 2026년 7월, 유럽 전역에 5GWh 규모의 나트륨 이온 에너지 저장 시스템을 도입하기로 합의했습니다. 이 합의는 태양광 인버터 배터리 업계에서 이 화학 조성에 대한 관심이 시범 운영 단계를 넘어서는 중임을 보여줍니다.
지역별 분석
아시아태평양은 2025년에 태양광 인버터 배터리 시장 점유율의 46.4%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.5%로 성장할 것으로 전망됩니다. 중국은 계속해서 이 지역 내 최대의 설비 생산 거점이자 주요 에너지 저장 시스템 도입 거점입니다. 국가 계획에 따라 계통 안정화를 위한 에너지 저장 및 재생에너지 발전과의 결합을 통한 배터리의 보다 광범위한 활용이 지원되고 있습니다. 인도에서는 분산형 태양광 발전의 확대로 인해 수요가 증가하고 있습니다. 일본, 한국, 호주에서는 견조한 가정용 수요가 예상되는 반면, 베트남, 인도네시아, 태국에서는 전력 신뢰성이 중시되는 소규모 시스템에 대한 초기 수요가 발생하고 있습니다.
북미는 미국이 유틸리티 규모의 도입과 증가하는 가정용 설치율을 모두 갖추고 있어, 태양광 인버터 배터리 시장에 있어 여전히 중요한 지역입니다. SEIA 보고서에 따르면, 2025년 미국의 신규 에너지 저장 용량은 58 GWh에 달했습니다. 캘리포니아주, 텍사스주, 애리조나주가 유틸리티 규모의 도입에서 큰 비중을 차지하고 있습니다. 매사추세츠주, 텍사스주, 뉴저지주 및 중대서양 연안 지역의 가상 발전소(VPP) 프로그램은 고객 수익 창출의 새로운 길을 열어주고 있습니다. 캐나다와 멕시코는 여전히 초기 단계 시장이지만, 청정 전력에 관한 규제와 분산형 발전 계획이 미래 수요를 뒷받침하고 있습니다.
유럽에서는 2025년에 EU-27에서 36GWh의 에너지 저장 용량이 추가되어 누적 용량이 100GWh를 넘어섰습니다. 독일, 영국, 이탈리아가 최대의 국내 시장이 되었습니다. 독일의 2026년 도입 증가는 동적 요금 제도와 확립된 가정용 태양광 발전 기반의 영향을 반영하고 있습니다. 남미, 중동 및 아프리카는 여전히 초기 단계의 지역이지만, 명확한 수요 견인 요인이 존재합니다. 브라질에서는 분산형 태양광 발전, 불안정한 송전망, 시간대별 요금제가 결합된 기회가 존재합니다. 한편, 사우디아라비아와 아랍에미리트(UAE)에서는 유틸리티급 배터리 저장 시스템에 대한 투자가 주목받고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the solar inverter battery market size is projected to expand from USD 2.09 billion in 2025 and USD 2.24 billion in 2026 to USD 3.11 billion by 2031, at a CAGR of 6.78% between 2026 and 2031.
This report is Segmented by Battery Chemistry (Lithium-Ion, Lead-Acid, Sodium-Ion, Flow Batteries, Others), Battery Capacity (Below 5 KWh, 5-10 KWh, 10-20 KWh, Above 20 KWh), End User (Residential, Commercial, Industrial, Utility-Scale), and Geography (North America, Europe, Asia-Pacific, South America, Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Solar Inverter Battery Market Trends and Insights
Solar-Plus-Storage Deployment Lifts Attachment Rates
The solar inverter battery market benefits as storage becomes a standard part of new solar projects. The U.S. residential solar storage attachment rate reached 45% in the first quarter of 2026, compared with 38% in the first quarter of 2025. This change reflected revised net-metering arrangements as well as customer interest in retaining more solar generation for later use in the solar inverter battery market. SEIA reported that the United States added 58 GWh of energy storage capacity in 2025. Paired systems require suppliers to coordinate inverter controls, battery management, and site design. This favors firms that can offer a complete system rather than a separate hardware component.
Falling Lithium-Ion System Costs Support Wider Adoption
The solar inverter battery market has gained from lower lithium iron phosphate, or LFP, cell costs. LFP cell prices were near USD 50/kWh in 2025, helping residential systems compete in high-tariff European and Australian settings. A rise in 314 Ah storage-cell prices during the first half of 2026 did not remove the economic case for commercial projects in the solar inverter battery market. Sungrow introduced PowerHarbor in June 2026 with 314 Ah prismatic cells and module-level DC-DC conversion. The design aims to reduce balance-of-system costs and simplify capacity additions. Certification expenses still limit savings for smaller installers operating under the national grid and safety rules.
High Upfront Costs Limit Access in Emerging Geographies
The solar inverter battery market remains less accessible, where consumer financing and installer capacity are limited. Lower cell prices have not eliminated total equipment, installation, and financing costs. Brazil had more than 500 MWh of behind-the-meter storage installed by January 2026, while the country was expected to add more than 650 MWh during 2026. Brazil's electricity regulator was reviewing Consulta Publica 39 in 2026, which could clarify storage business models. All-in-one equipment can shorten commissioning time in the solar inverter battery market, but this does not fully offset labor costs in markets with limited installer networks. These limits also constrain purchases of larger capacity systems by commercial customers.
Other drivers and restraints analyzed in the detailed report include:
- Grid Reliability and Energy Independence Strengthen Demand
- Renewable-Energy Incentives and Storage Mandates Improve Project Visibility
- Interconnection and Compliance Timelines Slow Deployment
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium-ion batteries held 72.1% of the solar inverter battery market share in 2025. LFP products formed the main part of this position because they have established supply chains and known performance in residential storage. Their operating range, cell-level safety characteristics, and compatibility with standard battery management systems support use in certified systems. Lead-acid batteries retained a role in cost-sensitive applications. Flow batteries continued to serve a limited set of long-duration commercial and industrial projects, where installation complexity and capital needs constrain wider use.
Sodium-ion batteries are forecast to grow at a 9.1% CAGR from 2026 to 2031. CATL stated that its sodium-ion cells can reach 97% system efficiency and more than 15,000 cycles to 80% capacity. The company's cell design does not use cobalt, nickel, or copper, which supports its cost position at larger production volumes. Alfen and CATL agreed in July 2026 to deploy 5 GWh of sodium-ion storage across Europe. The agreement shows that the solar inverter battery industry is moving beyond pilot-scale interest in this chemistry.
Complete Report Scope:
- By Battery Chemistry
- Lithium-ion Batteries
- Lead-acid Batteries
- Sodium-ion Batteries
- Flow Batteries
- Other Battery Chemistries
- By Battery Capacity
- Below 5 kWh
- 5-10 kWh
- 10-20 kWh
- Above 20 kWh
- By End User
- Residential
- Commercial
- Industrial
- Utility-scale
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- Italy
- Spain
- United Kingdom
- Poland
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Indonesia
- Vietnam
- Thailand
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Egypt
- South Africa
- Morocco
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 46.4% of the solar inverter battery market share in 2025 and is forecast to grow at an 8.5% CAGR through 2031. China remains the region's largest source of equipment production and a major storage deployment center. National planning supports grid-forming storage and broader use of batteries with renewable generation. India adds demand through distributed solar expansion. Japan, South Korea, and Australia support steady household demand, while Vietnam, Indonesia, and Thailand offer early demand for smaller systems where power reliability matters.
North America remains important to the solar inverter battery market because the United States combines utility-scale deployment with a growing household attachment rate. SEIA reported 58 GWh of new U.S. energy storage capacity in 2025. California, Texas, and Arizona account for a large share of utility-scale activity. Virtual power plant programs in Massachusetts, Texas, New Jersey, and the Mid-Atlantic create an additional route to customer revenue. Canada and Mexico remain earlier-stage markets, but clean electricity rules and distributed generation plans support future demand.
Europe added 36 GWh of storage in the EU-27 during 2025, taking cumulative capacity above 100 GWh. Germany, the United Kingdom, and Italy were the largest national markets. Germany's 2026 installation growth reflects the effect of dynamic tariffs and an established household solar base. South America, the Middle East, and Africa remain earlier-stage regions with clear demand drivers. Brazil combines distributed solar, unreliable grids, and time-of-use tariff opportunities, while Saudi Arabia and the United Arab Emirates draw utility-scale battery investment.
- BYD Company Limited
- Contemporary Amperex Technology Co., Limited (CATL)
- Dyness Digital Energy Technology Co., Ltd.
- Enphase Energy, Inc.
- Fluence Energy, Inc.
- Fronius International GmbH
- Ginlong Technologies Co., Ltd. (Solis)
- GoodWe Technologies Co., Ltd.
- Growatt New Energy Technology Co., Ltd.
- Huawei Digital Power Technologies Co., Ltd.
- LG Energy Solution Ltd.
- Panasonic Holdings Corporation
- Pylon Technologies Co., Ltd.
- Samsung SDI Co., Ltd.
- Schneider Electric SE
- SMA Solar Technology AG
- SolarEdge Technologies, Inc.
- Sungrow Power Supply Co., Ltd.
- Tesla, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Solar-Plus-Storage Deployment
- 4.2.2 Falling Lithium-Ion System Costs
- 4.2.3 Grid Reliability and Energy Independence
- 4.2.4 Renewable-Energy Incentives and Storage Mandates
- 4.2.5 Cybersecurity and Bankability Requirements Elevating Qualified Suppliers
- 4.2.6 Software-Led Virtual Power Plant Monetization
- 4.3 Market Restraints
- 4.3.1 High Upfront System and Installation Cost
- 4.3.2 Interconnection, Permitting, and Safety-Compliance Delays
- 4.3.3 Hybrid-System Interoperability and Warranty Risk
- 4.3.4 Trade Barriers, Local-Content Rules, and Skilled-Labor Shortages
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Battery Chemistry
- 5.1.1 Lithium-ion Batteries
- 5.1.2 Lead-acid Batteries
- 5.1.3 Sodium-ion Batteries
- 5.1.4 Flow Batteries
- 5.1.5 Other Battery Chemistries
- 5.2 By Battery Capacity
- 5.2.1 Below 5 kWh
- 5.2.2 5-10 kWh
- 5.2.3 10-20 kWh
- 5.2.4 Above 20 kWh
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.3.4 Utility-scale
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 France
- 5.4.2.3 Italy
- 5.4.2.4 Spain
- 5.4.2.5 United Kingdom
- 5.4.2.6 Poland
- 5.4.2.7 Russia
- 5.4.2.8 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Indonesia
- 5.4.3.7 Vietnam
- 5.4.3.8 Thailand
- 5.4.3.9 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Chile
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 Egypt
- 5.4.5.4 South Africa
- 5.4.5.5 Morocco
- 5.4.5.6 Rest of Middle East and Africa
- 5.4.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 BYD Company Limited
- 6.4.2 Contemporary Amperex Technology Co., Limited (CATL)
- 6.4.3 Dyness Digital Energy Technology Co., Ltd.
- 6.4.4 Enphase Energy, Inc.
- 6.4.5 Fluence Energy, Inc.
- 6.4.6 Fronius International GmbH
- 6.4.7 Ginlong Technologies Co., Ltd. (Solis)
- 6.4.8 GoodWe Technologies Co., Ltd.
- 6.4.9 Growatt New Energy Technology Co., Ltd.
- 6.4.10 Huawei Digital Power Technologies Co., Ltd.
- 6.4.11 LG Energy Solution Ltd.
- 6.4.12 Panasonic Holdings Corporation
- 6.4.13 Pylon Technologies Co., Ltd.
- 6.4.14 Samsung SDI Co., Ltd.
- 6.4.15 Schneider Electric SE
- 6.4.16 SMA Solar Technology AG
- 6.4.17 SolarEdge Technologies, Inc.
- 6.4.18 Sungrow Power Supply Co., Ltd.
- 6.4.19 Tesla, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment