|
시장보고서
상품코드
2119352
인도의 태양광 인버터 배터리 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)India Solar Inverter Battery - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
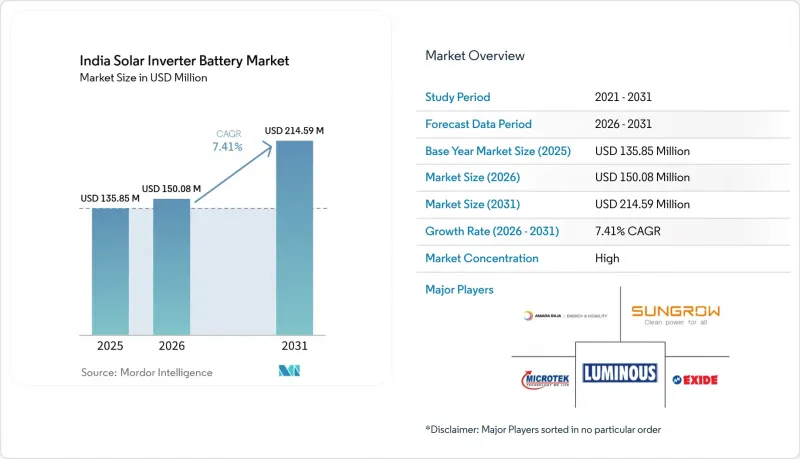
에 의하면, 인도의 태양광 인버터 배터리 시장 규모는 2025년 1억 3,585만 달러로 평가되었습니다. 2026년에는 1억 5,008만 달러로 확대되어 2031년까지 2억 1,459만 달러에 이를 것으로 예상되고 2026년부터 2031년에 걸쳐 CAGR은 7.41%를 나타낼 전망입니다.
본 보고서는 배터리의 화학적 구성(리튬 이온 배터리, 납축전지, 나트륨 이온 배터리, 플로우 배터리, 기타),배터리 용량(5KWh 미만, 5-10KWh, 10-20KWh, 20KWh 이상), 최종 사용자(주거용, 상업용, 산업용, 유틸리티 규모), 지역(인도)별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
인도의 태양광 인버터 배터리 시장 동향 및 인사이트
지붕형 태양광 발전 및 분산형 발전의 가속화
인도에서는 2024년 3.2 GW에 비해 2025년에는 7.1 GW의 옥상 태양광 발전 용량이 추가되었으며, 2025년 신규 도입 분의 76%를 주택이 차지했습니다. ‘PM Surya Ghar’ 제도는 2026년 8월까지 수혜 가구 수가 500만 가구를 돌파하면서, 향후 에너지 저장 시스템이 필요할 가능성이 있는 가구 수가 증가했습니다. 이 제도의 현행 체계에서는 축전지 조달과 태양광 발전 보조금 제도가 분리되어 있으므로, 각 가구는 여전히 백업 전원과 자가 소비를 통한 부가가치를 평가할 필요가 있습니다. 아삼주의 옥상 태양광 발전 용량은 전년 대비 463% 증가해 344 MW에 달한 반면, 우타르프라데시주에서는 용량이 2배 이상 증가해 714 MW를 기록했습니다. 이 주들은 서부의 주요 시장에 비해 전력 계통 상황이 불안정하기 때문에 축전지를 통한 백업의 실용적 가치가 높아지고 있습니다. 인도의 ‘미터 후방’ 설치형 축전 수요는 2025년에 32 GWh였으나, 2033년까지 39 GWh를 넘어설 것으로 예측됩니다.
유틸리티 규모의 ‘태양광+저장’ 입찰 및 DISCOM 지원
2025년까지 누적 기준으로 독립형 배터리 입찰 규모는 90.7 GW에 달했으며, 같은 해에는 총 102 GWh에 달하는 69건의 입찰이 실시되었습니다. 2026년 파이프라인에는 도입 단계에 있는 95GWh와 입찰 중인 80 GWh가 포함되어 있으며, 이는 배터리 공급업체에게 더 큰 잠재 시장을 시사합니다. GUVNL은 2026년 6월, 9단계 실행 가능성 격차 기금(VGF)에 따라 450 MW 및 900 MWh의 조달을 요청했습니다. 또한, 라자스탄주의 3개 배전 회사도 2026년 8월에 분산형 에너지 저장 설비로 172 MW 및 688 MWh에 대한 입찰을 실시했습니다. ‘에너지 저장 의무(ESO)’에 따라 배전 회사는 2030년까지 에너지 저장 용량을 전력 수요의 4%까지 끌어올려야 할 의무가 있으며, 이것이 장기적인 조달을 뒷받침하고 있습니다. 입찰 규모는 방대하지만, 공급업체에 대한 수요는 개발사가 자금 조달을 확보하고 프로젝트를 예정대로 완료할 수 있는지 여부에 따라 좌우될 것입니다.
수입 의존도와 셀 공급망의 위험
인도의 리튬 이온 배터리 생태계는 중국산 셀 수입에 크게 의존하고 있어, 공급 및 가격 변동에 취약한 상황입니다. 중국의 배터리 수출 환급 제도 변경과 루피화 약세로 인해 인도 바이어들의 셀 도착 가격은 추정치로 11-12% 상승했습니다. 314Ah LFP 셀 비용 중 원자재비가 65% 가까이 차지하고 있어, 가격이 반등할 경우 부품 원가가 15-20% 증가할 가능성이 있습니다. 2025년 12월까지 정식 경로를 통해 58.26락 톤의 배터리 폐기물이 처리되었으나, 사용 후 리튬 이온 배터리 중 정식 재활용 공정에 들어간 것은 5% 미만에 그쳤습니다. 아마라 라자(Amara Raja)사는 2027년에 리튬 이온 배터리 양산을 계획하고 있으며, 와리 ESS(Wari ESS)사도 2027 회계연도까지 생산 능력 확충을 예정하고 있습니다. 이러한 프로젝트로 인해 공급 압박은 완화될 가능성이 있지만, 단기적으로는 수입 배터리가 계속해서 중요한 역할을 할 것입니다.
부문 분석
2025년에는 저렴한 비용과 확고한 설치 업체 기반에 힘입어 리튬 이온 배터리가 71.1%의 점유율을 차지했습니다. 가격은 2023년 이후 30-40% 하락하여, 이로 인해 리튬 이온 배터리는 신규 하이브리드 설치에서 더욱 실용적인 선택지가 되었습니다. 납축전지는 초기 비용이 낮고 기존 인버터 시스템과 호환되기 때문에 2선 도시 및 농촌 지역에서 수요를 유지하고 있습니다. 플로우 배터리는 긴 사이클 수명과 설치 장소 요건으로 인해 높은 자본 비용이 정당화되는 제한된 유틸리티 규모의 용도로 사용되고 있습니다. IS 16221 Part II 및 IS 16169에 기반한 MNRE의 요건으로 인해 계통 연계 시스템의 인증 요건이 강화되었습니다.
나트륨 이온 배터리는 2031년까지 연평균 성장률(CAGR) 9.1%로 확대될 것으로 예상되며, 인도의 태양광 인버터 배터리 시장에서 가장 빠르게 성장하는 배터리 기술이 될 전망입니다. 나크시온 에너지(Naxion Energy)는 2025년 12월 코임바토르에서 연간 팩 생산 능력 1.5GWh 규모의 나트륨 이온 에너지 저장 시스템을 출시했습니다. 또한, 이 회사는 2027년까지 500 MWh 규모의 셀 제조 시범 프로젝트에 200 카롤 루피를 투자할 것이라고 발표했습니다. 탄산나트륨의 원가가 탄산리튬보다 훨씬 저렴하기 때문에 나트륨 이온 셀은 대규모 생산 시 리튬 이온 셀보다 20-30% 더 경제적일 가능성이 있습니다. 아마라 라자 씨가 이끄는 소디온 에너지(Sodion Energy)는 텔랑가나 주에서 1 GWh 규모의 나트륨 이온 생산 능력을 확보하겠다고 약속했으며, 이는 국내에서 이에 대한 관심이 지속적으로 높아지고 있음을 보여줍니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the India solar inverter battery market size is expected to increase from USD 135.85 million in 2025 to USD 150.08 million in 2026 and reach USD 214.59 million by 2031, at a CAGR of 7.41% over 2026-2031.
This report is Segmented by Battery Chemistry (Lithium-Ion Batteries, Lead-Acid Batteries, Sodium-Ion Batteries, Flow Batteries, Others), Battery Capacity (Below 5 KWh, 5-10 KWh, 10-20 KWh, Above 20 KWh), End User (Residential, Commercial, Industrial, Utility-Scale), and Geography (India). The Market Forecasts are Provided in Terms of Value (USD).
India Solar Inverter Battery Market Trends and Insights
Accelerating Rooftop Solar and Distributed Generation
India added 7.1 GW of rooftop solar capacity in 2025, compared with 3.2 GW in 2024, and residential consumers contributed 76% of the 2025 additions. PM Surya Ghar crossed 50 lakh beneficiary households by August 2026, which expanded the number of homes with a potential future need for storage. The scheme's current design keeps battery procurement separate from the solar subsidy, so households must still assess the added value of backup power and self-consumption. Assam's rooftop solar capacity reached 344 MW after 463% year-over-year growth, while Uttar Pradesh more than doubled its capacity to 714 MW. These states have more variable grid conditions than the large western markets, which increases the practical value of battery backup. India's behind-the-meter stationary storage demand was 32 GWh in 2025 and is expected to exceed 39 GWh by 2033.
Utility-Scale Solar-Plus-Storage Tendering and DISCOM Support
Standalone battery tenders reached 90.7 GW cumulatively through 2025, and 69 tenders totaling 102 GWh were issued during that year. The 2026 pipeline includes 95 GWh in deployment stages and another 80 GWh in tendering, which points to a larger addressable base for battery suppliers. GUVNL sought 450 MW and 900 MWh in June 2026 under Phase IX viability gap funding. Rajasthan's three distribution companies also tendered 172 MW and 688 MWh of decentralized storage in August 2026. The Energy Storage Obligation requires distribution companies to increase storage to 4% of electricity demand by 2030, supporting longer-term procurement. Tender volumes are substantial, but supplier demand will depend on developers securing finance and completing projects on schedule.
Import Dependence and Cell Supply-Chain Exposure
India's lithium-ion ecosystem relies heavily on imported Chinese cells, creating exposure to supply and pricing movements. China's battery export rebate changes and rupee depreciation added an estimated 11-12% to landed cell prices for Indian buyers. Raw materials represented nearly 65% of the cost of a 314Ah LFP cell, so a rebound could add 15-20% to the bill of materials. Formal channels handled 58.26 lakh tonnes of battery waste by December 2025, while fewer than 5% of end-of-life lithium-ion batteries entered formal recycling. Amara Raja plans bulk lithium-ion cell production in 2027, and Waaree ESS plans capacity additions by FY2027. These projects may ease supply pressure, but imported cells will remain important during the near term.
Other drivers and restraints analyzed in the detailed report include:
- Falling Lithium-Ion and LFP Storage Costs
- PM Surya Ghar, PM-KUSUM and Renewable Capacity Targets
- Aggressive BESS Tender Pricing and Bankability Risk
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Lithium-ion held 71.1% share in 2025, supported by lower costs and an established installer base. Prices had fallen 30-40% since 2023, making lithium-ion more practical for new hybrid installations. Lead-acid batteries retained demand in tier-2 and rural locations because they have a lower initial cost and work with existing inverter systems. Flow batteries serve limited utility-scale applications where long cycle life and site requirements justify higher capital costs. MNRE requirements under IS 16221 Part II and IS 16169 have raised certification requirements for grid-connected systems.
Sodium-ion is forecast to expand at a 9.1% CAGR through 2031, making it the fastest-growing chemistry in the India solar inverter battery market. Naxion Energy launched sodium-ion energy storage systems from Coimbatore in December 2025 with 1.5 GWh of annual pack capacity. It also announced INR 200 crore for a 500 MWh cell manufacturing pilot by 2027. Sodium-ion cells could be 20-30% more economical than lithium-ion cells at scale because sodium carbonate costs much less than lithium carbonate. Amara Raja's Sodion Energy unit has committed to 1 GWh of sodium-ion capacity in Telangana, indicating continued domestic interest.
Complete Report Scope:
- By Battery Chemistry
- Lithium-ion Batteries
- Lead-acid Batteries
- Sodium-ion Batteries
- Flow Batteries
- Other Battery Chemistries
- By Battery Capacity
- Below 5 kWh
- 5-10 kWh
- 10-20 kWh
- Above 20 kWh
- By End User
- Residential
- Commercial
- Industrial
- Utility-scale
List of Companies Covered in this Report:
- Amara Raja Energy and Mobility Limited
- BYD Company Limited
- Contemporary Amperex Technology Co., Limited (CATL)
- Delta Electronics, Inc.
- Enphase Energy, Inc.
- Exide Energy Solutions Limited
- GoodWe Technologies Co., Ltd.
- Growatt New Energy Technology Co., Ltd.
- Huawei Digital Power Technologies Co., Ltd.
- Jakson Group
- Luminous Power Technologies Private Limited
- Microtek International Private Limited
- Naxion Energy India Pvt. Ltd.
- Sineng Electric Co., Ltd.
- SOFARSOLAR Co., Ltd.
- SolarEdge Technologies, Inc.
- Sungrow Power Supply Co., Ltd.
- Tesla, Inc.
- Waaree Energies Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Rooftop Solar and Distributed Generation
- 4.2.2 Utility-Scale Solar-Plus-Storage Tendering
- 4.2.3 Falling Lithium-Ion and LFP Storage Costs
- 4.2.4 PM Surya Ghar, PM-KUSUM and Renewable Capacity Targets
- 4.2.5 DISCOM Energy Storage Obligations and VGF Support
- 4.2.6 India-Specific Firmware and Installer Localization for Weak-Grid Operation
- 4.3 Market Restraints
- 4.3.1 Import Dependence and Cell Supply-Chain Exposure
- 4.3.2 Aggressive BESS Tender Pricing and Bankability Risk
- 4.3.3 Fragmented DISCOM Interconnection and Installer Approval Workflows
- 4.3.4 Limited End-of-Life Traceability for Distributed Lithium Batteries
- 4.4 Supply-Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
- 4.6 Technology Outlook
- 4.7 Regulatory Landscape
- 4.8 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Battery Chemistry
- 5.1.1 Lithium-ion Batteries
- 5.1.2 Lead-acid Batteries
- 5.1.3 Sodium-ion Batteries
- 5.1.4 Flow Batteries
- 5.1.5 Other Battery Chemistries
- 5.2 By Battery Capacity
- 5.2.1 Below 5 kWh
- 5.2.2 5-10 kWh
- 5.2.3 10-20 kWh
- 5.2.4 Above 20 kWh
- 5.3 By End User
- 5.3.1 Residential
- 5.3.2 Commercial
- 5.3.3 Industrial
- 5.3.4 Utility-scale
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Amara Raja Energy and Mobility Limited
- 6.4.2 BYD Company Limited
- 6.4.3 Contemporary Amperex Technology Co., Limited (CATL)
- 6.4.4 Delta Electronics, Inc.
- 6.4.5 Enphase Energy, Inc.
- 6.4.6 Exide Energy Solutions Limited
- 6.4.7 GoodWe Technologies Co., Ltd.
- 6.4.8 Growatt New Energy Technology Co., Ltd.
- 6.4.9 Huawei Digital Power Technologies Co., Ltd.
- 6.4.10 Jakson Group
- 6.4.11 Luminous Power Technologies Private Limited
- 6.4.12 Microtek International Private Limited
- 6.4.13 Naxion Energy India Pvt. Ltd.
- 6.4.14 Sineng Electric Co., Ltd.
- 6.4.15 SOFARSOLAR Co., Ltd.
- 6.4.16 SolarEdge Technologies, Inc.
- 6.4.17 Sungrow Power Supply Co., Ltd.
- 6.4.18 Tesla, Inc.
- 6.4.19 Waaree Energies Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment