

|
시장보고서
상품코드
2119570
북미의 빌딩 자동화 시스템 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)North America Building Automation Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 북미의 빌딩 자동화 시스템 시장 규모는 2026년에 765억 7,000만 달러에 이르고, 2031년까지 1,289억 3,000만 달러로 확대되며 CAGR은 10.98%를 나타낼 전망입니다.
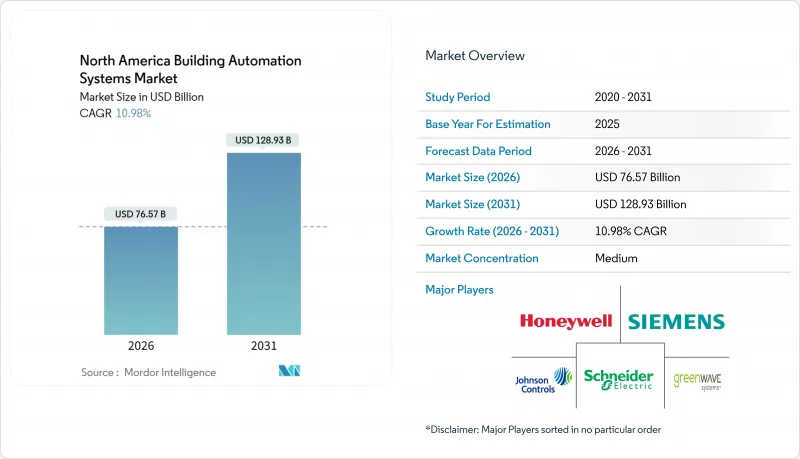
본 보고서는 구성 요소(하드웨어, 소프트웨어, 서비스), 시스템 유형(HVAC 제어 시스템, 조명 제어 시스템, 보안 및 출입 통제 시스템 등), 통신 기술(유선, 무선), 최종 사용자(주거용, 상업시설 등), 국가별로 세분화되어 있습니다. 시장 규모 및 전망은 상기 모든 부문에 대해 달러 기준으로 제시되어 있습니다.
북미의 빌딩 자동화 시스템 시장 동향 및 인사이트
AI를 활용한 예측 유지보수 및 분석 도입
머신러닝 모델은 센서에서 얻은 원시 데이터를 조기 경보 진단 정보로 변환하여 85%의 정확도로 3일 후까지의 설비 노후화를 예측합니다. 이를 통해 긴급 수리를 40% 줄이고 자산 수명을 15% 연장할 수 있습니다. 구독형 분석 플랫폼을 통해 공급업체는 가동 시간을 보장할 수 있게 되었으며, 수익원을 일회성 부품 판매에서 성과 기반 계약으로 전환하고 있습니다. 2025년에 1,200개 건물에서 실시된 도입 사례에서는 집계된 클라우드 데이터가 운영자가 전체 포트폴리오에서 이상 현상을 벤치마킹하는 데 도움이 된다는 사실이 입증되었습니다. 이는 단일 사이트에서의 분석으로는 실현할 수 없는 과제입니다. 추론 엔진이 통합된 엣지 컨트롤러는 알고리즘을 로컬에서 실행함으로써 지연 시간을 50밀리초로 단축하고 클라우드 대역폭 요구 사항을 줄입니다.
건물의 탈탄소화를 가속화하는 연방 및 주 정부의 인센티브
‘인플레이션 억제법’에 따라 에너지 소비량을 50% 감축하는 프로젝트에 대한 섹션 179D 공제액이 평방피트당 5달러로 인상되어, 단순 회수 기간이 8년에서 4년으로 절반으로 단축되었습니다. 뉴욕시 법안 97호에 따르면, 배출 상한선을 초과한 CO2 환산 배출량 1톤당 268달러의 벌금이 부과되므로, 자동화는 선택적인 업그레이드가 아니라 규정 준수를 위한 도구가 되었습니다. 캘리포니아주의 2025년판 ‘타이틀 24’ 개정안에서는 대규모 HVAC 시스템의 고장 감지가 의무화되어, 사실상 신규 상업시설 설치의 90%에서 자동화가 표준화되었습니다. 이러한 ‘당근과 채찍’의 조합으로 인해, 소유주들이 2032년의 단계적 감축에 앞서 인센티브를 확보하기 위해 서두르면서 조달 주기가 18개월에서 9개월로 단축되었습니다.
기존 건물의 개보수에는 막대한 초기 비용이 소요됩니다.
종합적인 개조 비용은 평방피트당 2.50-6달러가 들며, 10만 평방피트 규모의 프로젝트에서는 25만-60만 달러에 달할 전망입니다. 소규모 부동산 소유자의 경우, 보조금이 없다면 투자 회수에 7-10년이 소요되어, 선택적 지출에 일반적으로 적용되는 5년이라는 기준을 초과하게 됩니다. 무선 키트를 통해 인건비는 최대 40% 절감되지만, 하드웨어 비용은 여전히 현금 흐름에 부담을 줍니다. 시애틀에서 진행된 시범 사업에서는 공과금 청구서에 추가 요금을 부과하는 방식을 통한 무이자 대출 참여율이 92%에 달했으나, 사업 확장을 위해서는 규제 당국의 승인이 필요하며, 해당 절차에는 2년이 소요될 수 있습니다.
부문별 분석
소프트웨어 시장은 2031년까지 연평균 11.55%의 성장률을 기록했으며, 클라우드 플랫폼이 기기 데이터를 지속적인 이용료로 전환함에 따라 2025년에는 북미의 빌딩 자동화 시스템 시장에서 하드웨어 점유율 46.84%를 넘어섰습니다. 2025년, 존슨 컨트롤즈(Johnson Controls) 단독의 빌딩 자동화 시스템 소프트웨어 시장 규모는 12억 달러에 달하여 전년 대비 34% 증가했습니다. 소유주들은 포트폴리오 전반에 걸쳐 규모를 확대하면서도 자산의 감가상각을 피할 수 있는 OPEX 계약을 선호하고 있습니다. 상품화(commoditization)로 인해 컨트롤러 가격이 연간 8%-12% 하락함에 따라 하드웨어의 이익률은 축소되고 있으며, 제조업체들은 디바이스를 분석 서비스 구독과 세트로 판매하는 추세입니다.
엣지 컴퓨팅으로 인해 카테고리 간의 경계가 모호해지고 있습니다. 새로운 컨트롤러는 로컬에서 머신 러닝 추론을 실행하여 지연 시간을 500밀리초에서 50밀리초로 단축하는 동시에 아웃바운드 트래픽을 줄입니다. 서비스 수익은 고장 수리 대응에서 성능 보증으로 전환되고 있으며, 벤더가 비용 절감분을 공유할 경우 25%의 프리미엄이 적용됩니다. 이러한 변화는 경쟁 우위가 독자적인 사양의 디바이스에서 추가되는 건물마다 알고리즘의 정확도를 향상시키는 데이터 생태계로 이동하고 있음을 보여줍니다.
에너지 관리 및 분석 플랫폼은 시스템 유형 중 가장 빠른 속도인 연평균 11.74%로 성장하고 있습니다. 이 플랫폼은 하루 후의 부하를 92%의 정확도로 예측하고, 피크 시간대의 요금을 피할 수 있도록 사전 냉각을 가능하게 함으로써 에너지 비용을 최대 25% 절감합니다. HVAC 제어는 2025년 북미의 빌딩 자동화 시스템 시장에서 매출 점유율 39.42%를 차지했으나, A급 오피스 시장의 포화가 진행됨에 따라 그 성장세는 둔화되고 있습니다. 조명 시스템은 설치 시간을 40% 단축하고 리모델링의 실현 가능성을 높이는 무선 시운전 도구의 혜택을 받고 있습니다.
통합 대시보드를 통해 출입 통제 및 HVAC 구역 설정이 연동되어, 무인 구역에서의 에너지 낭비가 제거되고 있습니다. 화재 예방 및 생명 안전 대책의 업그레이드는 법규 요건에 따라 이루어지고 있습니다. NFPA 72의 2025년판에서는 네트워크 연결형 감지기의 요건이 확대되어, 대상 리모델링 프로젝트가 18% 증가했습니다. 전력 회사가 유연성을 높이 평가하는 가운데, PJM은 2025년에 수요 반응(Demand Response)에 대해 kW시당 85달러를 지급했습니다. 에너지 플랫폼은 새로운 수익원을 개척하여 수익률을 300 베이시스 포인트 끌어올립니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.10According to Mordor Intelligence, the North America building automation systems market size reached USD 76.57 billion in 2026 and is forecast to climb to USD 128.93 billion by 2031, reflecting a 10.98% CAGR.
This report is Segmented by Component (Hardware, Software, and Services), System Type (HVAC Control Systems, Lighting Control Systems, Security and Access Control Systems, and More), Communication Technology (Wired, and Wireless), End-User (Residential, Commercial, and More), and Country. The Market Sizes and Forecasts are Provided in Terms of Value in USD for all the Above Segments.
North America Building Automation Systems Market Trends and Insights
Adoption Of AI Enabled Predictive Maintenance And Analytics
Machine-learning models convert raw sensor feeds into early-warning diagnostics that predict equipment degradation three days ahead with 85% accuracy, cutting emergency repairs by 40% and lengthening asset life by 15%. Subscription-based analytics platforms allow vendors to guarantee uptime, shifting revenue from one-time parts sales to performance contracts. A 2025 deployment across 1,200 buildings demonstrated that aggregated cloud data helps operators benchmark anomalies portfolio-wide, a task single-site analysis cannot match. Edge controllers embedding inference engines now execute algorithms locally, trimming latency to 50 milliseconds and reducing cloud bandwidth needs.
Federal And State Incentives Accelerating Building Decarbonization
The Inflation Reduction Act increased the Section 179D deduction to USD 5.00 per square foot for projects hitting 50% energy savings, halving simple payback from eight to four years. New York City's Local Law 97 fines USD 268 per tonne of CO2-equivalent emissions above caps, converting automation into a compliance tool rather than a discretionary upgrade. California's 2025 Title 24 update mandates fault detection on large HVAC systems, effectively making automation standard in 90% of new commercial installs. Combined carrots and sticks have compressed procurement cycles from 18 months to nine as owners race to secure incentives before the 2032 phase-down.
High Upfront Retrofit Costs For Legacy Buildings
Comprehensive retrofits cost USD 2.50-USD 6.00 per square foot, pushing a 100,000 square-foot project to USD 250,000-USD 600,000. Smaller landlords face 7-10 year paybacks without rebates, exceeding the five-year hurdle typical of discretionary spending. Wireless kits trim labor by up to 40% but hardware still strains cash flow. On-bill, zero-interest utility financing reached 92% participation in a Seattle pilot, yet scaling needs regulatory approval that can take two years.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Growth Of Connected HVAC Retrofit Projects
- Corporate ESG Commitments Driving Smart Building Investments
- Skilled Labor Shortage For BAS Integration And Cybersecurity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Software grew 11.55% annually through 2031, outpacing hardware's 46.84% of North America building automation systems market share in 2025 as cloud platforms convert device data into recurring fees. The building automation systems market size for software reached USD 1.2 billion at Johnson Controls alone in 2025, up 34% year over year. Owners favor opex contracts that avoid capital depreciation while scaling across portfolios. Hardware margins are tightening as commoditization pushes controller prices down by 8%-12% annually, prompting manufacturers to bundle devices with analytics subscriptions.
Edge computing blurs category lines. New controllers perform machine-learning inference locally, cutting latency from 500 milliseconds to 50 milliseconds and reducing outbound traffic. Service revenue pivots from break-fix calls to performance guarantees, commanding a 25% premium when vendors share savings. These shifts indicate that competitive advantage is migrating away from proprietary devices toward data ecosystems that improve algorithm accuracy with every additional building.
Energy management and analytics platforms are expanding at 11.74% a year, the fastest pace among system types. They forecast load a day ahead with 92% accuracy, enabling pre-cooling that avoids peak tariffs and trims utility bills by up to 25%. HVAC control retained 39.42% of the 2025 revenue share in the North America building automation systems market, yet its growth moderates as saturation rises in Class A offices. Lighting systems benefit from wireless commissioning tools that reduce installation time by 40% and lift retrofit viability.
Unified dashboards now link access control with HVAC zoning, eliminating energy waste from unoccupied areas. Fire and life-safety upgrades follow code mandates; the 2025 edition of NFPA 72 broadened networked detector requirements, growing the addressable retrofit pool by 18%. As utilities reward flexibility, PJM paid USD 85 per kilowatt-hour for demand response in 2025. Energy platforms unlock a new revenue stream, boosting returns by 300 basis points.
Complete Report Scope:
- By Component
- Hardware
- Software
- Services
- By System Type
- HVAC Control Systems
- Lighting Control Systems
- Security and Access Control Systems
- Energy Management and Analytics Platforms
- Fire and Life Safety Systems
- By Communication Technology
- Wired
- Wireless
- By End-User
- Residential
- Commercial
- Industrial
- Institutional / Government
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Johnson Controls International PLC
- Honeywell International Inc.
- Siemens AG
- Schneider Electric SE
- Greenwave Systems Inc.
- Uplight Inc.
- Panasonic Holdings Corporation
- ABB Ltd.
- Carrier Global Corporation
- Trane Technologies plc
- Rockwell Automation Inc.
- Legrand SA
- Lutron Electronics Co. Inc.
- Cisco Systems Inc.
- Delta Controls Inc.
- Distech Controls Inc.
- Emerson Electric Co.
- Crestron Electronics Inc.
- Hubbell Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Adoption of AI-Enabled Predictive Maintenance and Analytics
- 4.2.2 Federal and State Incentives Accelerating Building Decarbonization
- 4.2.3 Rapid Growth of Connected HVAC Retrofit Projects
- 4.2.4 Corporate ESG Commitments Driving Smart Building Investments
- 4.2.5 Move Toward Open Interoperable BACnet/IP and MQTT Protocols
- 4.2.6 Emerging Demand for Indoor Air Quality Monitoring Post-Pandemic
- 4.3 Market Restraints
- 4.3.1 High Upfront Retrofit Costs for Legacy Buildings
- 4.3.2 Skilled Labor Shortage for BAS Integration and Cybersecurity
- 4.3.3 Rising Cyber-Security Compliance Costs
- 4.3.4 Semiconductor Supply Chain Volatility Impacting Controller Availability
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.2 Software
- 5.1.3 Services
- 5.2 By System Type
- 5.2.1 HVAC Control Systems
- 5.2.2 Lighting Control Systems
- 5.2.3 Security and Access Control Systems
- 5.2.4 Energy Management and Analytics Platforms
- 5.2.5 Fire and Life Safety Systems
- 5.3 By Communication Technology
- 5.3.1 Wired
- 5.3.2 Wireless
- 5.4 By End-User
- 5.4.1 Residential
- 5.4.2 Commercial
- 5.4.3 Industrial
- 5.4.4 Institutional / Government
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Johnson Controls International PLC
- 6.4.2 Honeywell International Inc.
- 6.4.3 Siemens AG
- 6.4.4 Schneider Electric SE
- 6.4.5 Greenwave Systems Inc.
- 6.4.6 Uplight Inc.
- 6.4.7 Panasonic Holdings Corporation
- 6.4.8 ABB Ltd.
- 6.4.9 Carrier Global Corporation
- 6.4.10 Trane Technologies plc
- 6.4.11 Rockwell Automation Inc.
- 6.4.12 Legrand SA
- 6.4.13 Lutron Electronics Co. Inc.
- 6.4.14 Cisco Systems Inc.
- 6.4.15 Delta Controls Inc.
- 6.4.16 Distech Controls Inc.
- 6.4.17 Emerson Electric Co.
- 6.4.18 Crestron Electronics Inc.
- 6.4.19 Hubbell Incorporated
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


