

|
시장보고서
상품코드
2119698
냉장 창고 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Cold Storage - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
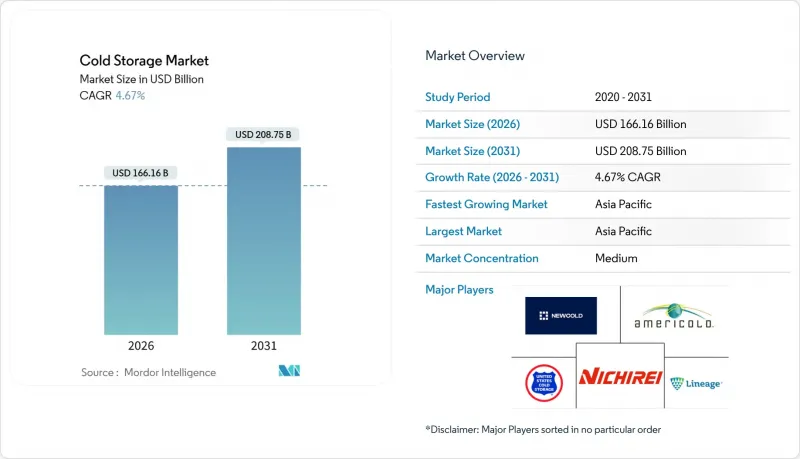
에 의하면, 냉장 창고 시장 규모는 2026년에 1,661억 6,000만 달러로 평가되었습니다. 예측 기간(2026-2031년) CAGR 4.67%로 성장을 지속하여, 2031년에는 2,087억 5,000만 달러에 이를 전망입니다.
본 보고서는 온도 유형별(냉장, 냉동, 상온, 초저온), 자동화 수준별(기존, 자동화 창고), 용도별(과일 및 채소, 육류, 가금류, 수산물, 유제품, 제빵 제품, 즉석식품, 의약품, 백신,화학제품, 기타), 지역(북미, 유럽, 아시아태평양, 기타)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 제시되어 있습니다.
세계의 냉장 창고 시장 동향 및 인사이트
조직화된 소매업 및 온라인 식료품 판매의 성장
온라인 식료품 판매는 2025년까지 미국 식료품 총 매출의 21.5%를 차지했으며, 대규모 인구 밀집 지역으로부터 10-15마일 반경 내에 설치된 전용으로 설계된 도시형 냉장 창고의 설치를 정당화할 수 있는 임계점에 도달할 전망입니다. 인도만 해도 현대식 소매업 시장 규모는 2024년 7,900억 달러에서 2025년에는 8,500억 달러로 확대되었으며, 이러한 매장에는 기존의 도매 네트워크로는 제공할 수 없는 온도 관리형 백엔드 물류가 요구되고 있습니다. 마이크로 풀필먼트의 설계는 공간 활용도를 극대화하며, 대부분의 경우 30분 이내 배송 시간대에 10만 가구 이상에 서비스를 제공하는 동시에 라스트 마일 비용을 최대 50% 절감합니다. 이러한 이점은 수요 예측의 과제로 인해 상쇄됩니다. 임대료가 높은 도시 지역 거점에서의 재고 부족이나 식품 품질 저하는 이익률의 우위를 급속히 훼손하기 때문에 사업자들은 정교한 수요 계획 소프트웨어와 고급 분석 기법의 도입을 서둘러야 합니다.
의약품 콜드체인의 확대
생물학적 제제, 세포 치료, 유전자 치료의 경우 현재 -40°C에서 -196°C까지의 보관이 요구되며, 이 온도 범위는 기존의 백신 요건을 훨씬 뛰어넘습니다. 2025년에 출시될, -180°C까지의 내구성이 검증된 SCHOTT Pharma의 폴리머 주사기는 포장 분야의 혁신이 급속도로 진행되고 있음을 여실히 보여줍니다. GDP 인증, 자동 온도 모니터링, 검증된 보관 이력 관리 프로토콜로 인해 규정 준수 비용은 상승했지만, 동시에 진입 장벽도 더욱 견고해져 인증을 받은 시설은 30-50%의 가격 프리미엄을 책정할 수 있게 되었습니다. 제조업체들이 회복력을 확보하기 위해 지역별 집배 거점을 설립함에 따라 지역적 분포가 다양해지고 있으며, 지금까지 의약품 물류에서 간과되었던 2차 시장에서 냉장 창고 운영 사업자들에게 새로운 기회가 생겨나고 있습니다.
높은 에너지 소비량과 전력 비용
일반적인 냉장 창고에서는 에너지비가 운영비의 50-70%를 차지하며, 수익성은 전기 요금 변동에 매우 민감합니다. 사하라 이남 아프리카의 일부 지역에서는 전력망의 불안정성으로 인해 디젤 발전기를 이용한 백업이 불가피하며, 이로 인해 운영 비용이 25% 상승할 가능성이 있습니다. 각 시설에서는 건물 외피 개보수, 가변 속도 드라이브 도입, 그리고 허니웰의 ‘Solstice ze’와 같은 저GWP 냉매 채택이 진행되고 있으며, 이를 통해 에너지 사용량을 46% 절감할 수 있는 것으로 보고되고 있습니다. 그러나 설비 투자액이 10만 제곱피트당 100만-300만 달러에 달하기 때문에 이익률이 낮은 시설에서는 도입 속도가 둔화되고 있습니다.
부문별 분석
2025년에도 냉동 보관은 금액 기준으로 냉장 시장 전체의 62.34%를 계속 차지했습니다. 그러나 -20°C 이하로 정의되는 초저온·극저온 부문은 2031년까지 연평균 성장률(CAGR) 13.01%로 확대될 전망이며, 이는 냉장 시장 전체 성장률의 약 3배에 해당합니다. -40°C에서 -86°C 범위에서 작동하는 초저온 냉동고는 세포 치료 및 유전자 치료에 필수적이며, -150°C 이하의 극저온 액체 질소 저장 수요도 증가하고 있습니다. 이러한 고사양 공간은 표준 냉동실에 비해 2-3배 높은 임대료가 책정되어 있어, 자본 비용을 상쇄하고 높은 이익률을 뒷받침하고 있습니다.
조기에 투자하는 사업자에게는 지속적인 경쟁 우위가 주어집니다. 초저온 보관실에는 이중화된 압축기, 장기 정전에 대비한 용량의 백업 발전기, 극저온 환경에 대응하는 스테인리스 랙, 그리고 검증된 실험실 정보 시스템과 연동된 지속적인 모니터링이 필요합니다. 팔레트 슬롯 1개당 초기 설비 투자액은 1,500달러를 초과할 수 있지만, 높은 가동률과 의약품 물류에서 일반적인 수년에 걸친 테이크 오어 페이(Take-or-Pay) 계약을 통해 수익의 확실성이 보장됩니다. 한편, 0-5°C의 냉장 구역에서는 유제품, 농산물 및 비냉동 의약품에 대한 안정적인 수요가 유지되고 있습니다. 냉장실에서는 가격 압박이 심화되고 있으며, 사업자들이 고정된 에너지 비용과 규정 준수 비용을 분산시키기 위해 규모 확대를 모색함에 따라 업계 재편이 진행되고 있습니다. 냉장, 냉동, 상온 각 구역을 유연하게 전환할 수 있는 하이브리드 시설이 주목받고 있으며, 단일 거점 내에서 부피당 처리 능력을 극대화하고 수익원을 다각화하고 있습니다.
지역별 분석
아시아태평양은 2025년에 냉장 창고 시장 가치의 36.61%를 차지했으며, 2031년까지 연평균 성장률(CAGR) 12.02%를 기록하며 다른 모든 지역을 앞지를 전망입니다. 중국에서는 각 성의 보조금과 의무화된 친환경 설계 기준이 에너지 효율이 높은 창고에 대한 투자를 촉진하고 있는 반면, 인도에서는 정부 프로그램을 통해 농장에서 대도시에 이르는 통합 네트워크가 지원되고 있습니다. 동남아시아는 싱가포르와 말레이시아의 온도 조절이 가능한 항구를 통해 수산물과 의약품을 운송하는 지역적 중계 허브로 성숙해 가고 있습니다. 규제 체계의 파편화와 기술 격차는 여전히 존재하지만, 경험이 풍부한 사업자들은 현지 파트너와의 합작 투자를 활용하여 인허가 및 토지 확보의 장벽을 극복하고 있습니다.
북미는 성숙해 가면서도 역동적인 상황을 보이고 있습니다. 미국만 해도 약 37억 입방피트의 냉장 창고를 보유하고 있지만, 시설의 평균 연식은 40년을 넘어서고 있어 현대화의 물결이 밀려오고 있습니다. 온라인 식품 쇼핑의 보급과 의약품 시장의 성장에 따라, 투자는 도시 지역의 마이크로 풀필먼트 거점이나 복합 일괄 운송 회랑에 인접한 자동화된 초대형 창고로 이동하고 있습니다. 주요 연안 시장의 토지 부족으로 지대가 급등함에 따라, 철도가 정비된 물류 단지 인근의 내륙 지역으로 개발이 진행되고 있습니다. 캐나다와 멕시코는 각각 수출 지향형 농업과 니어쇼어링 동향을 뒷받침하기 위해 용량을 확대하고 있으며, 이 지역의 통합된 공급망을 공고히 하고 있습니다.
남미, 유럽, 중동 및 아프리카에서는 대조적인 상황이 관찰됩니다. 브라질과 페루에서는 육류 및 과일 수출을 위한 수용 능력을 확대하고 있지만, 환율 변동과 높은 차입 비용으로 인해 소규모 프로젝트는 제한되고 있습니다. 유럽의 냉장 시장에서는 F가스 금지 조치로 인해 천연 냉매 도입이 가속화되며, 규제 주도의 근본적인 재검토가 진행되고 있습니다. 독일, 베네룩스 국가, 북유럽 국가들은 자동화와 재생에너지의 통합을 주도하고 있는 반면, 남유럽에서는 높은 전기 요금을 상쇄하기 위해 태양광 발전을 병용한 하이브리드형 시설이 도입되고 있습니다. 중동에서는 UAE와 사우디아라비아가 지역 허브로서의 위상을 확립해 가는 반면, 사하라 이남 아프리카에서는 수확 후 손실을 줄이기 위해 태양광 발전과 연계된 마이크로 저장 실증 실험이 진행되고 있어, 콜드체인의 성숙을 향한 다양한 경로가 부각되고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측-금액(달러)
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the cold storage market size is estimated at USD 166.16 billion in 2026, and is expected to reach USD 208.75 billion by 2031, at a CAGR of 4.67% during the forecast period (2026-2031).
This report is Segmented by Temperature Type (Chilled, Frozen, Ambient, Deep-Frozen/Ultra-Low), by Automation Level (Conventional, Automated Stores), by Application (Fruits & Vegetables, Meat, Poultry, Seafood, Dairy, Bakery, Ready-To-Eat Meals, Pharmaceuticals, Vaccines, Chemicals, and Others), by Geography (North America, Europe, Asia-Pacific, and More). Market Forecasts are Provided in Value (USD).
Global Cold Storage Market Trends and Insights
Growth of Organized Retail & E-grocery
Online grocery is on track to capture 21.5% of total U.S. grocery sales by 2025, reaching the critical mass that justifies purpose-built urban cold stores positioned within 10-15 miles of large population centers. Modern trade formats in India alone are set to rise from USD 790 billion in 2024 to USD 850 billion in 2025, and these outlets require temperature-controlled back-end logistics that legacy wholesale networks cannot supply. Micro-fulfillment designs maximize cubic utilization, often serving more than 100,000 households with a 30-minute delivery window while cutting last-mile costs by up to 50%. The upside is balanced by forecasting challenges: stockouts or spoilage in high-rent urban nodes rapidly erode margin advantages, pushing operators toward sophisticated demand-planning software and advanced analytics.
Expansion of Pharmaceutical Cold Chains
Biologics, cell therapies, and gene therapies now demand storage from -40 °C down to -196 °C, a range far beyond traditional vaccine requirements. SCHOTT Pharma's polymer syringe validated to -180 °C, launched in 2025, underscores the pace of packaging innovation. GDP certification, automated temperature monitoring, and validated chain-of-custody protocols have raised compliance costs but also created durable barriers to entry, allowing certified facilities to charge 30-50% pricing premiums. Geography is diversifying as manufacturers establish regional depots for resilience, opening opportunities for cold storage operators in secondary markets previously overlooked by pharmaceutical logistics.
High Energy Consumption & Electricity Costs
Energy accounts for 50-70% of operating expense in a typical cold store, leaving profitability highly sensitive to tariff swings. In parts of Sub-Saharan Africa, grid unreliability forces diesel backup that can raise operating costs by 25%. Facilities are upgrading building envelopes, installing variable-speed drives, and adopting low-GWP refrigerants such as Honeywell's Solstice ze, reported to cut energy use by 46%. Capital outlays, however, range from USD 1 million to USD 3 million per 100,000 ft2, slowing adoption in lower-margin facilities.
Other drivers and restraints analyzed in the detailed report include:
- Rising Demand for Frozen & Convenience Foods
- Government Incentives for Cold-Chain Infrastructure
- Heavy Upfront CapEx & Regulatory Compliance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Frozen storage continues to anchor 62.34% of the cold storage market in 2025 by value. Yet the deep-frozen and ultra-low segment, defined as below -20 °C, is climbing at a 13.01% CAGR to 2031, nearly triple the overall cold storage market growth. Ultra-low freezers operating between -40 °C and -86 °C are indispensable for cell and gene therapies, and demand for cryogenic liquid nitrogen storage below -150 °C is emerging. This high-specification space commands rental rates two to three times higher than standard frozen rooms, cushioning capital costs and supporting premium margins.
Operators investing early enjoy durable advantages. Ultra-low rooms require redundant compressors, backup generators sized for extended outages, stainless-steel racks compatible with cryogenic exposure, and continuous monitoring that integrates with validated laboratory information systems. Upfront capex per pallet slot can exceed USD 1,500, but high utilization and multi-year take-or-pay contracts common in pharma logistics provide revenue certainty. Conversely, the chilled 0-5 °C band retains steady demand for dairy, produce, and non-frozen pharmaceuticals. Pricing pressure is more acute in chilled rooms, prompting consolidation as operators seek scale to spread fixed energy and compliance costs. Hybrid facilities that flex zones among chilled, frozen, and ambient conditions are gaining traction, maximizing cubic throughput and diversifying revenue streams within a single site.
Complete Report Scope:
- By Temperature Type
- Chilled (0-5 °C)
- Frozen (-18-0 °C)
- Ambient
- Deep-Frozen / Ultra-Low (<-20 °C)
- By Automation Level (Storage)
- Conventional Facilities
- Automated Cold Stores (AS/RS, Robotics)
- By Application
- Fruits & Vegetables
- Meat & Poultry
- Fish & Seafood
- Dairy & Frozen Desserts
- Bakery & Confectionery
- Ready-to-Eat Meals
- Pharmaceuticals & Biologics
- Vaccines & Clinical Trial Materials
- Chemicals & Specialty Materials
- Other Perishables
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Peru
- Chile
- Argentina
- Rest of South America
- Asia Pacific
- India
- China
- Japan
- Australia
- South Korea
- South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- Rest of Asia-Pacific
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- BENELUX (Belgium, Netherlands, and Luxembourg)
- NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- Rest of Europe
- Middle East And Africa
- United Arab of Emirates
- Saudi Arabia
- South Africa
- Nigeria
- Rest of Middle East And Africa
- North America
Geography Analysis
Asia-Pacific held 36.61% of the cold storage market value in 2025 and is set to outpace all other regions with a 12.02% CAGR to 2031. China's provincial subsidies and mandatory green-design codes spur investment in energy-efficient warehouses, while India's government programs underwrite integrated networks from farmgate to megacity. Southeast Asia is maturing into a regional transshipment hub, channeling seafood and pharmaceuticals through Singapore's and Malaysia's temperature-controlled ports. Fragmented regulatory frameworks and skills gaps persist, yet savvy operators leverage joint ventures with local partners to navigate permitting and land acquisition hurdles.
North America exhibits a mature yet dynamic landscape. The United States alone controls roughly 3.7 billion cubic feet of refrigerated storage, but average facility age exceeds 40 years, prompting a modernization wave. E-grocery penetration and pharmaceutical growth are redirecting investment toward urban micro-fulfillment nodes and automated mega-warehouses near intermodal corridors. Land scarcity in Tier-1 coastal markets inflates ground rents, pushing development inland along rail-served logistics parks. Canada and Mexico are expanding capacity to support export-oriented agriculture and near-shoring trends, respectively, cementing the region's integrated supply networks.
South America, Europe, and the Middle East-Africa offer contrasting profiles. Brazil and Peru expand capacity for meat and fruit exports, though currency volatility and high borrowing costs limit smaller projects. Europe's cold storage market is undergoing a regulatory-driven overhaul as the F-gas ban accelerates adoption of natural refrigerants. Germany, the BENELUX, and the Nordics lead in automation and renewable integration, while Southern Europe deploys hybrid solar-powered plants to offset high electricity tariffs. In the Middle East, the UAE and Saudi Arabia position themselves as regional hubs, while Sub-Saharan Africa experiments with solar-linked micro-storage to cut post-harvest losses, highlighting diverse pathways toward cold chain maturity.
- Lineage Logistics Holdings, LLC
- Americold Realty Trust, Inc.
- United States Cold Storage, Inc.
- Burris Logistics, Inc.
- NewCold Cooperatief U.A.
- United States Cold Storage, Inc. (USCS)
- Nichirei
- Emergent Cold Latin America
- FreezPak Logistics
- Interstate Warehousing, Inc
- Cube Cold Europe NL HoldCo B.V. (CubeCold)
- SuperFrio Logistica Frigorificada
- Vertical Cold Storage
- Magnavale Ltd
- Conestoga Cold Storage
- Agile Cold Storage LLC
- Arcadia Cold Storage & Logistics
- Congebec Inc.
- Cold-Link Logistics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growth of organized retail & e-grocery
- 4.2.2 Expansion of pharmaceutical cold chains
- 4.2.3 Rising demand for frozen & convenience foods
- 4.2.4 Government incentives for cold-chain infrastructure
- 4.2.5 Solar-powered refrigeration in emerging markets
- 4.2.6 Warehouse automation (AS/RS, robotics) adoption
- 4.3 Market Restraints
- 4.3.1 High energy consumption & electricity costs
- 4.3.2 Heavy upfront CapEx & regulatory compliance
- 4.3.3 Shortage of skilled refrigeration technicians
- 4.3.4 Rising insurance premiums for ammonia systems
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory or Technological Outlook
- 4.6 Porter's Five Forces
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
- 4.7 Cold Storage Capacity Expansion Trend Analysis
5 Market Size & Growth Forecasts - Value (USD)
- 5.1 By Temperature Type
- 5.1.1 Chilled (0-5 °C)
- 5.1.2 Frozen (-18-0 °C)
- 5.1.3 Ambient
- 5.1.4 Deep-Frozen / Ultra-Low (<-20 °C)
- 5.2 By Automation Level (Storage)
- 5.2.1 Conventional Facilities
- 5.2.2 Automated Cold Stores (AS/RS, Robotics)
- 5.3 By Application
- 5.3.1 Fruits & Vegetables
- 5.3.2 Meat & Poultry
- 5.3.3 Fish & Seafood
- 5.3.4 Dairy & Frozen Desserts
- 5.3.5 Bakery & Confectionery
- 5.3.6 Ready-to-Eat Meals
- 5.3.7 Pharmaceuticals & Biologics
- 5.3.8 Vaccines & Clinical Trial Materials
- 5.3.9 Chemicals & Specialty Materials
- 5.3.10 Other Perishables
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 South America
- 5.4.2.1 Brazil
- 5.4.2.2 Peru
- 5.4.2.3 Chile
- 5.4.2.4 Argentina
- 5.4.2.5 Rest of South America
- 5.4.3 Asia Pacific
- 5.4.3.1 India
- 5.4.3.2 China
- 5.4.3.3 Japan
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 South East Asia (Singapore, Malaysia, Thailand, Indonesia, Vietnam, and Philippines)
- 5.4.3.7 Rest of Asia-Pacific
- 5.4.4 Europe
- 5.4.4.1 United Kingdom
- 5.4.4.2 Germany
- 5.4.4.3 France
- 5.4.4.4 Spain
- 5.4.4.5 Italy
- 5.4.4.6 BENELUX (Belgium, Netherlands, and Luxembourg)
- 5.4.4.7 NORDICS (Denmark, Finland, Iceland, Norway, and Sweden)
- 5.4.4.8 Rest of Europe
- 5.4.5 Middle East And Africa
- 5.4.5.1 United Arab of Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Rest of Middle East And Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Lineage Logistics Holdings, LLC
- 6.4.2 Americold Realty Trust, Inc.
- 6.4.3 United States Cold Storage, Inc.
- 6.4.4 Burris Logistics, Inc.
- 6.4.5 NewCold Cooperatief U.A.
- 6.4.6 United States Cold Storage, Inc. (USCS)
- 6.4.7 Nichirei
- 6.4.8 Emergent Cold Latin America
- 6.4.9 FreezPak Logistics
- 6.4.10 Interstate Warehousing, Inc
- 6.4.11 Cube Cold Europe NL HoldCo B.V. (CubeCold)
- 6.4.12 SuperFrio Logistica Frigorificada
- 6.4.13 Vertical Cold Storage
- 6.4.14 Magnavale Ltd
- 6.4.15 Conestoga Cold Storage
- 6.4.16 Agile Cold Storage LLC
- 6.4.17 Arcadia Cold Storage & Logistics
- 6.4.18 Congebec Inc.
- 6.4.19 Cold-Link Logistics


