|
시장보고서
상품코드
2120571
주택용 태양에너지 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Residential Solar Energy - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
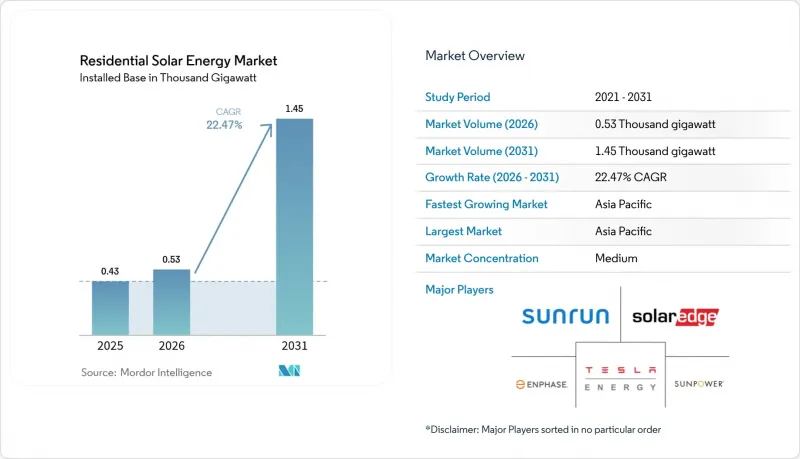
에 의하면, 주택용 태양에너지 시장 규모는 2025년에 430기가와트로 평가되었습니다. 2026년 530기가와트에서 2031년까지 1,450기가와트에 이를 것으로 예상되며, 예측 기간(2026-2031년) CAGR은 22.47%를 나타낼 전망입니다.
본 보고서는 기술별(단결정 PERC, N형 TOPCon·HJT, 기타), 설치 유형별(지붕 설치형 태양광 발전, 건축 일체형 태양광 지붕 기와), 그리드 유형별(온그리드, Off-grid, 하이브리드),지역별(북미, 유럽, 아시아태평양, 남미, 중동 및 아프리카)로 분류되어 있습니다. 시장 규모와 전망은 설치 용량(GW) 기준으로 제시되어 있습니다.
세계의 주택용 태양에너지 시장 동향 및 인사이트
모듈 및 BOS 비용의 하락
모듈 가격은 2024년에 1W당 0.20달러를 하회했으며, 규모의 경제 효과를 가져오는 중국의 지속적인 공장 확장에 힘입어 2027년까지 1W당 0.15달러 수준으로 하락할 것으로 예측됩니다. N형 TOPCon 생산 라인에서 현재 26.5%의 생산 효율을 달성할 수 있게 된 데 더해, 고출력 모듈로 인해 어레이의 설치 면적이 축소되어 장착 브라켓 및 인건비 절감으로 이어지고 있습니다. 인버터 단가는 작년에 15% 더 하락했으며, 표준화된 배선 키트를 통해 소프트 비용도 절감되었습니다. 이러한 종합적인 영향으로 전 세계 가구의 60% 이상에 적용되는 주택 전기 요금보다 낮은 수준의 균등화 발전 비용(LCOE)이 실현되어, 옥상 태양광 발전은 고급 옵션에서 일반적인 가정용 가전제품으로 변화하고 있습니다. 효율 향상은 지붕 공간의 유효 이용 기간을 연장하는 결과로 이어지며, 설치 면적이 제한된 도시 지역의 주택에 있어 매우 중요한 이점이 됩니다. JinkoSolar의 56GW 규모 산시성 공장은 대규모 생산이 어떻게 가격을 지속적으로 낮추고 있는지를 여실히 보여주고 있습니다.
‘인플레이션 억제법’형 인센티브의 물결이 미국 이외의 지역으로 확산
미국의 30% 연방 투자 세액 공제는 전 세계적으로 유사한 프로그램을 촉진하는 계기가 되었습니다. 유럽의 ‘REPowerEU’는 재생에너지에 2,100억 유로를 배정했으며, 한편 독일은 지붕형 태양광 발전의 보급을 가속화하기 위해 고정가격 임베디드 제도를 재개하고 태양광 발전 설비에 대한 부가가치세를 폐지했습니다. 일본에서는 현재 축전지와 결합된 태양광 발전 시스템에 대해 1kW당 7만 엔을 지급하고 있으며, 호주 빅토리아주에서는 ‘Solar Homes’ 리베이트 제도를 통해 가구당 1,400호주달러가 지급되고 있습니다. 정책 입안자들은 설비 비용의 하락에 맞추어 이러한 인센티브를 단계적으로 축소하는 체계를 구축하고 있으며, 보조금을 시장 원리에 따른 경제로 점차 전환한다는 미국의 청사진을 참고하고 있습니다. 이러한 정책의 물결이 전 세계적으로 조화를 이루면서, 현재의 설치 대수가 가속화될 뿐만 아니라, 비용 평준화가 달성된 후 보조금에 의존하지 않는 성장을 위한 미래의 여지도 생겨나고 있습니다. 인센티브가 보급됨에 따라 설치 업체들은 검증된 자금 조달 모델과 공급망 모델을 바탕으로 새로운 지역에 진출하여 규모의 경제 효과를 강화함으로써, 이는 추가적인 비용 절감을 이끌어내는 선순환을 만들어내고 있습니다.
금리 환경 변동으로 인한 고객 확보 비용 상승
급격한 금융 긴축으로 인해 30년 만기 태양광 발전 대출 금리는 2022년 4.5%에서 2024년 7.8%로 상승하여, 대출을 통한 시스템 도입 시 소비자에게 제공되던 가치 제안이 훼손되었습니다. 이에 대응해 대출 기관 측은 계약금 최저 기준을 상향 조정하고, 신용 심사 기준을 엄격화하며, 판매 주기를 장기화하는 등의 조치를 취한 결과, 고객 확보 비용은 35% 상승했습니다. 많은 첫 구매자를 포함하는 장기 대출에 의존하는 시장 부문에서는 특히 전기 요금이 비교적 낮은 지역에서 구매가 미뤄졌습니다. 대규모 설치 업체들은 증권화를 통해 낮은 금리를 확보하고 있지만, 중소규모의 계약업체들은 이와 같은 자금 조달 수단이 없어 경쟁의 다양성이 좁아지고 있습니다. 금리 변동이 진정될 때까지는 현금 판매나 리스가 일시적으로 다시 매력적으로 변하면서 제품 구성에 변화가 생기고, 판매업자의 운전 자본에 부담이 가중됩니다.
부문별 분석
2025년에는 단결정 PERC 모듈이 주거용 태양에너지 시장 점유율의 83.32%를 차지했으나, 효율 향상으로 인해 지붕당 에너지 밀도가 높아짐에 따라 N형 TOPCon의 출하량은 2031년까지 연평균 성장률(CAGR) 23.86%를 나타낼 것으로 예측됩니다. 이러한 변화로 인해 설치 면적을 확대하지 않고도 발전량을 늘릴 수 있는 고가 제품용 주택용 태양에너지 시장 규모가 확대될 것입니다.
각 제조업체들은 점점 더 상품화되는 PERC 시장에서 이익률을 지키기 위해 TOPCon으로의 전환을 추진하고 있습니다. 처리 능력 향상과 웨이퍼 수율 개선에 힘입어 단위 비용이 수렴됨에 따라, TOPCon은 PERC와 비슷한 가격 책정이 가능해졌으며, 여기에 1-2%의 효율 향상을 실현함으로써 공간 제약이 있는 도시 지역 주택에서 투자 회수 기간을 대폭 단축할 수 있게 됩니다. JinkoSolar가 달성한 페로브스카이트 탠덤 방식의 33.24%라는 사상 최고 효율 기록은 미래 성장의 길을 명확히 보여주며, TOPCon을 차세대 셀 아키텍처의 주류 플랫폼으로서 확고한 지위에 올려놓았습니다. 박막이나 다결정 같은 대체 기술이 틈새 시장에서의 역할을 계속하고 있는 반면, TOPCon은 현재 프리미엄 시장의 기반이 되어 모듈 제조업체의 장기적인 연구개발 로드맵을 주도하고 있습니다.
지역별 분석
북미는 정교한 자금 조달 수단과 성숙한 설치 업체 네트워크에 힘입어 2025년 전 세계 주거용 태양광 시장 매출의 34.62%를 차지했습니다. 작년에 총액 30억 달러가 넘는 대출 한도를 확보한 것은 지붕형 태양광 발전의 현금 흐름에 대한 기관 투자자들의 신뢰를 보여주는 것이었습니다. 연방 세액 공제 폐지가 임박하고, 순계량제(net metering) 제도 개혁이 확산되는 가운데, 가정의 경우 인센티브가 만료되기 전에 설치를 완료해야 한다는 전략적 시급성이 높아지고 있어, 정책의 불확실성에도 불구하고 단기적인 설치량은 유지될 전망입니다.
아시아태평양은 28.65%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 예측되며, 급속한 도시화, 전기 요금 상승, 적극적인 탈탄소화 목표에 힘입어 해당 지역의 주거용 태양광 시장 규모가 확대될 전망입니다. 중국은 국내 제조업에서의 우위를 활용하여 1선 도시에서 고밀도로 태양광 패널을 설치하고 있는 반면, 인도에서는 접속 규정이 간소화됨에 따라 그동안 관료주의로 인해 가로막혀 있던 주택 부문이 개방되고 있습니다. 일본은 지진에 대한 내성을 강화하기 위해 에너지 저장 시스템과 결합한 옥상 설치를 중시하고 있으며, 정전 시 백업 전원이 되는 하이브리드 시스템에 대해 보조금을 지급하고 있습니다.
유럽의 전망은 계속해서 견조하며, ‘REPowerEU’ 자금이 회원국들의 프로그램에 투입되어 부가가치세(VAT) 철폐와 고정가격임베디드제도(FIT)의 미세 조정이 진행되고 있습니다. 독일의 정책 재검토로 가정용 수요가 회복되고 있으며, 스페인에서는 풍부한 일사량과 규제 안정성이 맞물려 설치가 지속되고 있습니다. 겨울철 일사량 감소에 직면한 북유럽 국가들은 계절형 에너지 저장 솔루션의 조기 도입을 추진하고 있습니다. EU 전역에서 추적성 의무화로 인해 신장산 이외의 폴리실리콘 조달을 증명할 수 있는 공급업체가 유리한 입지를 차지하며, 이는 조달 결정에 영향을 미치고 주택용 태양광 발전 산업을 공급망 다변화로 이끌고 있습니다.
기타 혜택
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
KTH 26.09.04According to Mordor Intelligence, the residential solar energy market size was valued at 0.43 Thousand gigawatt in 2025 and estimated to grow from 0.53 Thousand gigawatt in 2026 to reach 1.45 Thousand gigawatt by 2031, at a CAGR of 22.47% during the forecast period (2026-2031).
This report is Segmented by Technology (Monocrystalline PERC, N-Type TOPCon/HJT, and More), Installation Type (Rooftop-Mounted PV and Building-Integrated Solar Roof Tiles), Grid Type (On-Grid, Off-Grid, and Hybrid), and Geography (North America, Europe, Asia-Pacific, South America, and Middle East and Africa). The Market Sizes and Forecasts are Provided in Terms of Installed Capacity (GW).
Global Residential Solar Energy Market Trends and Insights
Declining Module & BOS Costs
Module prices slid below USD 0.20 per W in 2024 and are tracking toward USD 0.15 per W by 2027, anchored by China's ongoing factory expansions that unlock economies of scale. Coupled with 26.5% production efficiencies now possible in N-type TOPCon lines, higher-power modules shrink array footprints and reduce mounting hardware and labor needs. Inverter unit costs fell another 15% last year, while standardized wiring kits trimmed soft costs. The aggregate impact lowers the levelized cost of electricity beneath residential tariffs that apply to more than 60% of global households, turning rooftop solar from a premium add-on into a mainstream household appliance. Elevated efficiency also prolongs roof-space relevance, a critical advantage for urban homes with limited surface area. JinkoSolar's 56 GW Shanxi facility underscores how large-scale manufacturing continues to compress prices.
IRA-Style Incentive Waves Spreading Beyond the US
The United States' 30% federal investment tax credit catalyzed parallel programs worldwide. Europe's REPowerEU earmarked EUR 210 billion for renewables, while Germany re-introduced feed-in tariffs and scrapped VAT on solar hardware to jump-start rooftop adoption. Japan now offers JPY 70,000 per kW for storage-paired arrays, and Australia's Victoria Solar Homes rebate provides AUD 1,400 per household. Policymakers structure these incentives to phase down in tandem with falling equipment costs, borrowing the US blueprint of gradually converting subsidies into market-based economics. The synchronized policy wave accelerates installation volumes today and creates future headroom for unsubsidized growth once parity is achieved. As incentives spread, installers enter new regions with proven finance and supply-chain models, reinforcing scale benefits that feed back into cost decline.
Volatile Interest-Rate Environment Inflating Customer Acquisition Costs
Rapid monetary tightening lifted 30-year solar-loan coupons from 4.5% in 2022 to 7.8% in 2024, eroding the consumer value proposition for financed systems. Lenders responded by raising down-payment thresholds, tightening credit filters, lengthening sales cycles, and pushing customer acquisition costs up 35%. Market segments reliant on long-tenor loans, including many first-time buyers, deferred purchases, especially in regions where electricity tariffs are moderate. Larger installers secure lower rates via securitizations, but smaller contractors lack similar funding breadth, narrowing competitive diversity. Until rate volatility subsides, cash sales and leases regain temporary attractiveness, altering product mixes and stressing dealer working capital.
Other drivers and restraints analyzed in the detailed report include:
- Spike in Retail Power Prices & Grid-Outage Anxiety
- EV-Charger-Ready Home Energy Ecosystems
- Sudden Net-Metering Policy Roll-Backs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Monocrystalline PERC modules dominated the residential solar energy market share with 83.32% in 2025, but N-type TOPCon shipments are forecast to post a 23.86% CAGR through 2031 as efficiency gains translate into higher roof-level energy density. This shift broadens the residential solar energy market size for premium-priced products that add generation without expanding the array footprint.
Manufacturers pivot to TOPCon to defend margins in an increasingly commoditized PERC landscape. Unit-cost convergence-helped by higher throughput and better wafer yields-allows TOPCon to approach PERC pricing while adding 1-2 percentage points of efficiency to shorten payback periods materially in space-constrained urban dwellings. JinkoSolar's record 33.24% perovskite-tandem result underscores the pathway to future gains and solidifies TOPCon as the mainstream platform for next-generation cell architectures. While thin-film and polycrystalline alternatives persist in niche roles, TOPCon now anchors the premium tier and guides long-run R&D roadmaps for module makers.
Complete Report Scope:
- By Technology
- Monocrystalline PERC
- N-type TOPCon/HJT
- Polycrystalline
- Thin-film (CdTe, CIGS)
- Emerging Perovskite Tandems
- By Installation Type
- Rooftop-mounted PV
- Building-integrated solar roof tiles
- By Grid Type
- On-grid
- Off-grid
- Hybrid (PV + Storage + Grid)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Spain
- Nordic Countries
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Malaysia
- Thailand
- Indonesia
- Vietnam
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
North America retained 34.62% of the global residential solar energy market revenue in 2025, buoyed by sophisticated financing and mature installer networks. Last year, securing loan vehicles totaling over USD 3 billion signaled institutional faith in rooftop cash-flows. Even so, the pending elimination of the federal tax credit and spreading net-metering reforms create strategic urgency for households to install before incentives lapse, sustaining near-term volume despite policy uncertainty.
Asia-Pacific is projected to deliver the fastest 28.65% CAGR, expanding the regional residential solar energy market size through rapid urbanization, rising electricity tariffs, and proactive decarbonization goals. China capitalizes on domestic manufacturing dominance to deploy high-density arrays in tier-one cities, while India's streamlined interconnection rules open residential segments previously hindered by bureaucracy. Japan emphasizes storage-paired rooftops to bolster earthquake resilience, subsidizing hybrid systems that promise backup power during grid interruptions.
Europe's outlook remains resilient as REPowerEU funds cascade into member-state programs that remove VAT and fine-tune feed-in tariffs. Germany's policy reset revived household demand, and Spain's abundant irradiation pairs with regulatory stability to sustain installations. Nordic countries, facing winter irradiance dips, are early adopters of seasonal storage solutions. Across the bloc, traceability mandates elevate suppliers able to verify non-Xinjiang polysilicon sourcing, shaping procurement decisions and nudging the residential solar energy industry toward diversified supply chains.
- Sunrun Inc.
- Tesla Energy
- SunPower Corp.
- Enphase Energy
- SolarEdge Technologies
- Trina Solar
- JinkoSolar
- Canadian Solar
- LONGi Green Energy
- JA Solar
- Hanwha Q Cells
- REC Group
- First Solar
- Panasonic Energy
- SMA Solar Technology
- Fronius International
- ABB Power Conversion
- GoodWe Technologies
- Fronius International
- LG Energy Solution (ESS)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Declining module & BOS costs
- 4.2.2 Inflation Reduction Act-style incentive waves spreading beyond the US
- 4.2.3 Spike in retail power prices & grid-outage anxiety
- 4.2.4 Maturing residential solar loan securitization platforms
- 4.2.5 EV-charger-ready home energy ecosystems
- 4.2.6 Peer-to-peer blockchain energy trading pilots
- 4.3 Market Restraints
- 4.3.1 Volatile interest-rate environment inflating customer acquisition costs
- 4.3.2 Sudden net-metering policy roll-backs (e.g., CA NEM 3.0)
- 4.3.3 Polysilicon-supply ESG scrutiny limiting premium-segment demand
- 4.3.4 Installer labour & permitting bottlenecks in key metros
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Technology
- 5.1.1 Monocrystalline PERC
- 5.1.2 N-type TOPCon/HJT
- 5.1.3 Polycrystalline
- 5.1.4 Thin-film (CdTe, CIGS)
- 5.1.5 Emerging Perovskite Tandems
- 5.2 By Installation Type
- 5.2.1 Rooftop-mounted PV
- 5.2.2 Building-integrated solar roof tiles
- 5.3 By Grid Type
- 5.3.1 On-grid
- 5.3.2 Off-grid
- 5.3.3 Hybrid (PV + Storage + Grid)
- 5.4 By Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 United Kingdom
- 5.4.2.2 Germany
- 5.4.2.3 France
- 5.4.2.4 Spain
- 5.4.2.5 Nordic Countries
- 5.4.2.6 Russia
- 5.4.2.7 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 India
- 5.4.3.3 Japan
- 5.4.3.4 South Korea
- 5.4.3.5 Malaysia
- 5.4.3.6 Thailand
- 5.4.3.7 Indonesia
- 5.4.3.8 Vietnam
- 5.4.3.9 Australia
- 5.4.3.10 Rest of Asia-Pacific
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Colombia
- 5.4.4.4 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 United Arab Emirates
- 5.4.5.2 Saudi Arabia
- 5.4.5.3 South Africa
- 5.4.5.4 Egypt
- 5.4.5.5 Rest of Middle East and Africa
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Sunrun Inc.
- 6.4.2 Tesla Energy
- 6.4.3 SunPower Corp.
- 6.4.4 Enphase Energy
- 6.4.5 SolarEdge Technologies
- 6.4.6 Trina Solar
- 6.4.7 JinkoSolar
- 6.4.8 Canadian Solar
- 6.4.9 LONGi Green Energy
- 6.4.10 JA Solar
- 6.4.11 Hanwha Q Cells
- 6.4.12 REC Group
- 6.4.13 First Solar
- 6.4.14 Panasonic Energy
- 6.4.15 SMA Solar Technology
- 6.4.16 Fronius International
- 6.4.17 ABB Power Conversion
- 6.4.18 GoodWe Technologies
- 6.4.19 Fronius International
- 6.4.20 LG Energy Solution (ESS)
7 Market Opportunities & Future Outlook
- 7.1 White-space & unmet-need assessment