|
시장보고서
상품코드
2120638
차세대 생체인식 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Next Generation Biometric - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
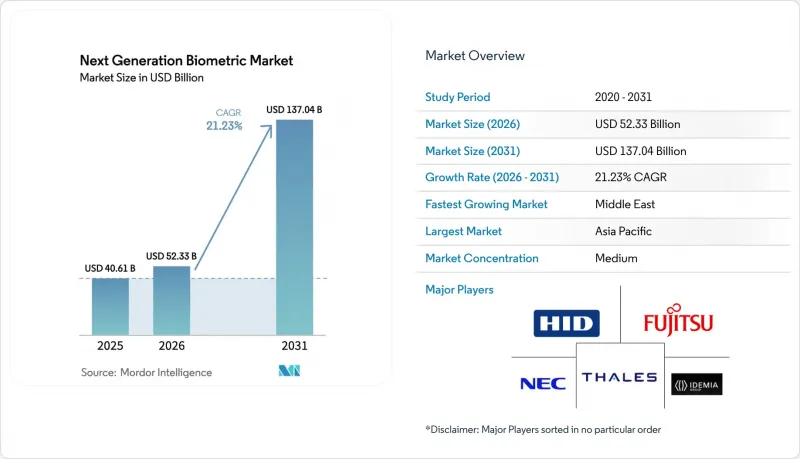
에 의하면, 차세대 생체인식 시장 규모는 2025년에 406억 1,000만 달러, 2026년에 523억 3,000만 달러, 2031년까지 1,370억 4,000만 달러에 이를 것으로 예측되며, 2026-2031년 CAGR 21.23%를 기록할 전망입니다.

본 보고서는 생체 인증 방식(얼굴 인증, 홍채 인증 등), 구성 요소(하드웨어, 소프트웨어, 서비스), 기능(접근 제어, 법의학 등), 최종 사용자 산업(정부, 의료, 소비자 가전 및 홈 보안, 소매 및 전자상거래, 교육 등), 그리고 지역별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
세계 차세대 생체 인식 시장 동향 및 인사이트
정부 주도의 국민 ID 도입
각국의 프로그램에 따라 임의의 디지털 ID가 의무화된 공공 인프라로 변모하고 있으며, 이로 인해 벤더는 IT 지출의 주기적인 변동 영향을 덜 받게 되었습니다. 인도에서는 2025년에 얼굴 인식을 기반으로 한 ‘Aadhaar’ 인증을 민간 기업으로도 확대하여, 종이 서류가 필요 없는 핀테크 서비스 이용 등록을 가능하게 했습니다. 유럽연합(EU)은 2026년까지 모든 시민이 상호 운용 가능한 생체 인증 지갑을 이용할 수 있도록 하는 것을 목표로 하고 있으며, 정보 유출 시의 책임을 각국 정부에서 인증된 지갑 제공업체로 이전하고 있습니다. 나이지리아와 케냐도 다자간 자금 지원을 바탕으로 유사한 길을 걷고 있으며, 이로 인해 지문 및 홍채 센서에 대한 확실한 수요가 창출되고 있습니다. 이러한 대량 조달로 인해 공급업체의 투자 회수 기간이 단축되고, 차세대 생체 인증 시장 전체가 활성화되고 있습니다.
스마트폰에 생체 인증 통합
모바일 기기는 기업의 기대에도 영향을 미치는 새로운 성능 기준을 수립하고 있습니다. 삼성의 ‘갤럭시 S25’에 탑재된 초음파 센서는 오거부율 1% 미만을 달성하여 EMVCo의 결제 기준을 충족합니다. 퀄컴의 대형 센서 ‘3D Sonic Max’는 두 손가락 인증을 가능하게 하여 고액 거래를 타겟으로 하고 있습니다. 애플의 Face ID는 모든 처리를 Secure Enclave 내에서 수행함으로써 GDPR(EU 개인정보보호규정)의 데이터 최소화 규칙을 준수하고 있습니다. 소비자들이 1년에 수천 번이나 스마트폰 잠금을 해제하는 가운데, 은행 및 의료 등 관련 업계도 이러한 원활한 사용자 경험을 따라잡아야 할 필요성이 대두되면서 차세대 생체 인증 시장 전반에 걸친 도입이 가속화되고 있습니다.
개인정보 보호 및 시민의 자유에 대한 우려
GDPR(EU 개인정보보호규정)에서 ‘특별 범주’를 취급할 때는 명시적인 동의와 엄격한 보안 조치가 요구되며, Clearview AI 사례에서 볼 수 있듯이 위반 시 수백만 유로에 달하는 벌금이 부과될 수 있습니다. 현재 EU의 AI 법에 따라 대부분의 실시간 공공장소에서의 얼굴 스캔이 금지되어 있으며, 캘리포니아주 주민들은 필수적이지 않은 생체 인증 이용을 거부할 수 있습니다. 시민권 단체들은 소수 집단에 미치는 불균형적인 영향을 지속적으로 지적하고 있으며, 이는 시 차원의 금지 조치로 이어지고 있습니다. 그 결과, 공급업체는 국가별로 서로 다른 소프트웨어 빌드를 유지해야 하며, 이로 인해 규정 준수 비용이 증가하고 차세대 생체 인식 시장의 확산이 지연되고 있습니다.
부문 분석
지문 인식 시스템은 오랜 기간 쌓아온 탄탄한 기반과 저렴한 센서 가격 덕분에 2025년 차세대 생체 인식 시장 점유율의 39.26%를 차지했습니다. 그러나 정맥 인증은 비접촉식 인식이 가능하고 스푸핑 위험이 거의 제로에 가깝기 때문에 연평균 성장률(CAGR) 22.83%를 기록하며, 이미 자리 잡은 지문 인증 시장 점유율을 서서히 잠식할 태세를 갖추고 있습니다. 일본 은행 업계에서 후지쯔의 ‘PalmSecure’ 도입 사례와 히타치의 병원 도입 사례는 실생활에서 이 기술의 성장세를 여실히 보여주고 있습니다. 얼굴 인증은 여행 업계나 스마트폰 분야에서 여전히 널리 보급되어 있지만, 홍채 인증은 국방 및 난민 관리에 중점을 두고 있으며, 그 낮은 오인식률이 높은 비용을 정당화하고 있습니다. 손바닥 지문, 보행, 음성, 행동 분석 각 시스템은 각각 틈새 시장의 요구를 충족시키고 있으며, 각 기술의 강점을 융합하고 약점을 보완하는 멀티모달 플랫폼이 등장하고 있습니다. 기업들이 시스템 업그레이드를 검토하는 가운데, 다층적 보안에 대한 신뢰가 높아지고 있음을 반영하여, 멀티모달 솔루션을 기반으로 한 차세대 생체 인증 시장 규모는 확대될 것으로 예측됩니다.
삼성이 특허를 취득한 2세대 초음파식 손바닥 지문 센서는 향후 융합을 예고하며, 단일 제스처로 위생과 정확성 두 가지 요건을 모두 충족할 수 있게 해줍니다. 음성 인식의 도입은 생체 감지 기능과 결합되지 않는 한 딥페이크의 위험으로 인해 제약을 받고 있습니다. 한편, BioCatch와 같은 기업이 제공하는 행동 생체 인식 기술은 사용자 세션 중에 지속적인 인증을 수행하여 금융 용도에서의 부정 사용을 줄이고 있습니다. 이러한 발전이 결합되면서, 자본이 기존의 단일 모드 리더에서 소프트웨어 정의 오케스트레이션 계층으로 재분배되고 있으며, 이러한 진화로 인해 차세대 생체 인식 시장에서는 하드웨어 이익률보다 서비스 수익이 더 중요시되고 있습니다.
2025년에도 하드웨어는 여전히 매출의 63.78%를 차지했지만, 50달러 미만의 지문 모듈로 인한 가격 압박으로 인해 이익률은 하락하고 있습니다. 현재 각 벤더들은 알고리즘 업데이트, 규정 준수 보고, 생체 인식 기능 강화 등을 연평균 21.77%의 성장률을 보이는 클라우드 구독 서비스에 통합하고 있습니다. IDEMIA의 신원 확인용 ‘거래 기반 과금형 API’는 과거 막대한 설비 투자를 주저했던 고객들의 지연된 지출을 흡수하고 있습니다. 동시에, 차세대 생체 인증 시장의 하드웨어 규모는 전자 게이트 및 국민 ID 키오스크의 센서 정기 업데이트에 의해 뒷받침되고 있어, 안정적이지만 낮은 수익률의 하한선이 확보되고 있습니다.
각 시스템 통합사업자들은 접근 제어, 결제, 전자 여권 인증을 통합된 대시보드에 통합함으로써 부가가치를 창출하고 있습니다. 고객이 호환되지 않는 리더기를 개별적으로 관리하는 대신 단일 스택으로 표준화할 경우, 소프트웨어 라이선스 수익이 증가합니다. 퀄컴의 프리미엄 3D Sonic Max 센서는 더 넓은 감지 범위와 기기 내 처리에 초점을 맞춘 하드웨어 차별화 전략을 두드러지게 하고 있습니다. 그러나 대부분공급업체는 차세대 생체 인식 시장에서 평생 가치(LTV)를 확대하기 위한 가장 명확한 경로로 서비스를 통한 지속적 수익을 보고 있습니다.
지역별 분석
아시아태평양은 중국 전역에 퍼져 있는 감시 카메라와 인도의 Aadhaar 플랫폼을 견인력으로 삼아 2025년 매출의 36.84%를 차지했습니다. 2025년 인도가 얼굴 인증을 민간 부문으로 확대하기로 결정함에 따라 핀테크 및 원격 의료 채널이 열리면서 현지 수요가 가속화되고 있습니다. 중국에서는 사회 신용 프로파일과 연동된 멀티모달 검문소 설치가 진행되고 있는 반면, 일본에서는 주요 공항에 NEC의 생체 인증 전자 게이트가 도입되었습니다. 한국에서는 30만 원을 초과하는 모바일 거래에 대해 생체 인증을 통한 확인이 의무화되어 있어, 이로 인해 스마트폰용 리더기의 보급이 촉진되고 있습니다. 호주에서는 입국자의 거의 전부를 ‘SmartGate’를 통해 처리하고 있어, 대규모 자동 출입국 관리의 실례를 보여주고 있습니다. 이러한 동향들이 맞물려 아시아태평양은 차세대 생체 인증 시장에서 가장 큰 기여를 하는 지역으로서의 위상을 유지하고 있습니다.
중동은 더욱 급속한 성장 궤도에 올라 있으며, 2031년까지 연평균 성장률(CAGR)은 22.19%로 예측됩니다. ‘UAE Pass’는 현재 5,000건 이상의 공공 및 민간 디지털 서비스를 지원하고 있으며, 사우디아라비아는 2030년까지 디지털 ID 보급률을 70%로 높이는 것을 목표로 하고 있습니다. 카타르는 처리 능력 향상을 이유로 월드컵 종료 후에도 홍채 인증 기반 공항 시스템을 유지하고 있으며, 이스라엘은 400만 명 이상의 국민에게 생체 인증 여권을 발급하고 있습니다. 이러한 국가 주도의 노력은 세계 및 지역 벤더들에게 확실한 수주원이 되고 있으며, 그 결과 대형 시스템 통합사업자들이 그동안 간과해 왔던 지역에서 차세대 생체 인증 시장 규모를 확대시키고 있습니다.
북미와 유럽에서는 규제가 엄격해지고 있지만, 정책의 명확성이라는 이점도 누리고 있습니다. EU의 ‘디지털 ID 지갑’에서는 2026년까지 국경을 넘는 인증이 의무화될 예정이며, 개인정보 보호를 둘러싼 논쟁이 계속되는 가운데서도 예산 배정이 확보될 전망입니다. 독일 연방정보보안청은 현재 조달 과정의 불확실성을 완화하기 위한 기술 지침을 공표했습니다. 미국에서는 세관·국경수비국이 얼굴 인증을 통한 출국 게이트를 32개 공항으로 확대하여 연간 1억 명 이상의 승객을 스캔하고 있습니다. 남미와 아프리카 국가들은 아직 도입 초기 단계에 있지만, 나이지리아와 케냐의 생체 인식 신분증 프로그램, 그리고 브라질과 아르헨티나의 시범 사업은 차세대 생체 인식 시장이 궁극적으로 신흥 경제국 전체로 확대될 것임을 시사하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the next generation biometric market size is projected to be USD 40.61 billion in 2025, USD 52.33 billion in 2026, and reach USD 137.04 billion by 2031, growing at a CAGR of 21.23% from 2026 to 2031.
This report is Segmented by Biometric Modality (Face Recognition, Iris Recognition, and More), Component (Hardware, Software, Services), Function (Access Control, Forensics, and More), End-User Industry (Government, Healthcare, Consumer Electronics and Home Security, Retail and E-Commerce, Education, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Next Generation Biometric Market Trends and Insights
Government-Mandated National ID Rollouts
National programs are transforming optional digital IDs into mandatory public infrastructure that buffers vendors from cyclical IT spending. India expanded face-based Aadhaar authentication to private entities in 2025, enabling fintech onboarding without the need for paper documents. The European Union aims to have interoperable biometric wallets for all citizens by 2026, shifting liability for breaches from states to certified wallet providers. Nigeria and Kenya are following similar paths, backed by multilateral funding, which creates guaranteed demand for fingerprint and iris sensors. These high-volume procurements shorten vendor payback periods and lift the overall next generation biometric market.
Integration of Biometrics in Smartphones
Mobile devices are setting new performance baselines that ripple into enterprise expectations. Samsung's Galaxy S25 ultrasonic sensor achieves a false reject rate of less than 1% and meets EMVCo payment standards. Qualcomm's larger 3D Sonic Max allows two-finger verification, targeting high-value transactions. Apple's Face ID keeps all processing within its Secure Enclave, aligning with GDPR data-minimization rules. As consumers unlock phones thousands of times a year, sectors such as banking and healthcare must match that frictionless experience, accelerating adoption across the next generation biometric market.
Privacy and Civil-Liberty Concerns
Special-category status under the GDPR requires explicit consent and strict security measures, leading to multimillion-euro fines for non-compliance, as seen in the Clearview AI case. The EU AI Act now bans most real-time public face scans, and California residents can opt out of non-essential biometric use. Civil-rights groups continue to highlight disproportionate impact on minorities, prompting city-level bans. Vendors must therefore maintain country-specific software builds, which raises compliance costs and slows rollouts in the next generation biometric market.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in Contactless 3D Vein Imaging
- Expansion of E-Passport Programs
- Algorithmic Bias Driving Stricter Regulation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Fingerprint systems accounted for 39.26% of the next generation biometric market share in 2025, benefiting from long-established bases and low sensor prices. However, vein recognition is charting a 22.83% CAGR thanks to contactless capture and near-zero spoofing risk, positioning it to chip away at the entrenched modality. Fujitsu's PalmSecure rollouts in Japanese banking and Hitachi's hospital deployments illustrate real-world momentum. Face recognition remains ubiquitous in travel and smartphones, while iris recognition stays focused on defense and refugee management, where its low false-match rate justifies the higher costs. Palm-print, gait, voice, and behavioral systems each fill niche needs, and multimodal platforms are emerging to blend strengths and mask weaknesses. As enterprises evaluate upgrades, the next generation biometric market size for multimodal solutions is expected to widen, reflecting growing confidence in layered security.
Second-generation ultrasonic palm-print sensors, patented by Samsung, hint at a future convergence, allowing a single gesture to satisfy both hygiene and accuracy requirements. Voice recognition adoption is throttled by deepfake risks unless paired with liveness checks. Meanwhile, behavioral biometrics from firms such as BioCatch supply continuous authentication during a user session, reducing fraud in financial applications. Collectively, these advances are reallocating capital from legacy single-mode readers toward software-defined orchestration layers, an evolution that favors service revenue over hardware margins inside the next generation biometric market.
Hardware still accounted for 63.78% of revenue in 2025; however, pricing pressure from sub-USD 50 fingerprint modules has diluted margins. Vendors now package algorithm updates, compliance reporting, and liveness-detection enhancements into cloud subscriptions that grow at a rate of 21.77% annually. IDEMIA's pay-per-transaction API for identity verification captures deferred spend from customers who once balked at large capital layouts. At the same time, the next generation biometric market size for hardware is sustained by mandatory sensor refreshes in e-gates and national ID kiosks, ensuring a stable but lower-margin revenue floor.
System integrators are extracting value by stitching together access control, payments, and e-passport verification into unified dashboards. Software license income increases when clients opt to standardize on a single stack rather than managing disparate readers. Qualcomm's premium 3D Sonic Max sensors underline a hardware differentiation strategy focused on larger capture zones and on-device processing. Yet, most vendors view service annuities as the clearest path to expanding lifetime value within the next generation biometric market.
Complete Report Scope:
- By Biometric Modality
- Face Recognition
- Fingerprint Recognition
- Iris Recognition
- Palm-print Recognition
- Voice Recognition
- Vein Recognition
- Gait and Behavioral Biometrics
- Multimodal Biometrics
- By Component
- Hardware
- Software
- Services
- By Function
- Access Control
- Identification and Verification
- Payments and Transactions
- Surveillance and Monitoring
- Time and Attendance
- Forensics
- Other Functions
- By End-user Industry
- Government
- Defense and Public Safety
- Travel and Immigration
- Banking and Financial Services
- Healthcare
- Consumer Electronics and Home Security
- Retail and E-commerce
- Education
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific contributed 36.84% of 2025 revenue, anchored by China's ubiquitous surveillance cameras and India's Aadhaar platform. India's 2025 decision to extend face authentication to the private sector opened fintech and telemedicine channels that accelerate local demand. China continues installing multimodal checkpoints linked to social-credit profiles, while Japan relies on NEC's biometric e-gates across major airports. South Korea mandates biometric confirmation for mobile transactions exceeding KRW 300,000, thereby bolstering smartphone reader adoption. Australia processes almost all arrivals through SmartGate, showcasing automated border control at scale. Together, these developments maintain Asia-Pacific as the largest contributor to the next generation biometric market.
The Middle East is on a faster trajectory, with a 22.19% CAGR predicted through 2031. The UAE Pass now underpins more than 5,000 public and private digital services, and Saudi Arabia aims for 70% digital ID coverage by 2030. Qatar retained its iris-based airport system after the World Cup due to throughput gains, and Israel has issued biometric passports to more than 4 million citizens. These state-backed schemes provide firm order books for global and regional vendors, thereby expanding the next generation biometric market size in a geography that large integrators have historically overlooked.
North America and Europe face tighter regulation yet benefit from policy clarity. The EU Digital Identity Wallet will make cross-border credentialing mandatory by 2026, ensuring budget allocation even amid ongoing privacy debates. Germany's Federal Office for Information Security now publishes technical guidelines aimed at reducing procurement uncertainty. In the United States, Customs and Border Protection has expanded facial-matching exit gates to 32 airports, scanning more than 100 million passengers annually. South American and African nations are still in the early stages of their journeys, but Nigeria's and Kenya's biometric ID programs, as well as Brazil's and Argentina's pilots, suggest that the next generation biometric market will eventually expand across emerging economies.
- IDEMIA Identity & Security France SAS
- NEC Corporation
- Thales SA
- Fujitsu Limited
- HID Global Corporation
- Fingerprint Cards AB
- Synaptics Incorporated
- Suprema Inc.
- Apple Inc.
- Samsung Electronics Co., Ltd.
- Qualcomm Incorporated
- Gemalto N.V.
- BioCatch Ltd.
- Aware, Inc.
- Cognitec Systems GmbH
- DERMALOG Identification Systems GmbH
- Vision-Box, S.A.
- Precise Biometrics AB
- IDEX Biometrics ASA
- Innovatrics, s.r.o.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion Of E-Passport Programs
- 4.2.2 Integration Of Biometrics In Smartphones
- 4.2.3 Government-Mandated National ID Rollouts
- 4.2.4 Advancements In Contactless 3D Vein Imaging
- 4.2.5 Rise Of Decentralized Blockchain-Based Digital Identity
- 4.2.6 Multimodal Biometrics For Remote Workforce Management
- 4.3 Market Restraints
- 4.3.1 Privacy And Civil-Liberty Concerns
- 4.3.2 High Upfront System Costs
- 4.3.3 Algorithmic Bias Driving Stricter Regulation
- 4.3.4 Supply-Chain Shortages Of Near-IR Sensors
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Biometric Modality
- 5.1.1 Face Recognition
- 5.1.2 Fingerprint Recognition
- 5.1.3 Iris Recognition
- 5.1.4 Palm-print Recognition
- 5.1.5 Voice Recognition
- 5.1.6 Vein Recognition
- 5.1.7 Gait and Behavioral Biometrics
- 5.1.8 Multimodal Biometrics
- 5.2 By Component
- 5.2.1 Hardware
- 5.2.2 Software
- 5.2.3 Services
- 5.3 By Function
- 5.3.1 Access Control
- 5.3.2 Identification and Verification
- 5.3.3 Payments and Transactions
- 5.3.4 Surveillance and Monitoring
- 5.3.5 Time and Attendance
- 5.3.6 Forensics
- 5.3.7 Other Functions
- 5.4 By End-user Industry
- 5.4.1 Government
- 5.4.2 Defense and Public Safety
- 5.4.3 Travel and Immigration
- 5.4.4 Banking and Financial Services
- 5.4.5 Healthcare
- 5.4.6 Consumer Electronics and Home Security
- 5.4.7 Retail and E-commerce
- 5.4.8 Education
- 5.4.9 Other End-user Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 IDEMIA Identity & Security France SAS
- 6.4.2 NEC Corporation
- 6.4.3 Thales SA
- 6.4.4 Fujitsu Limited
- 6.4.5 HID Global Corporation
- 6.4.6 Fingerprint Cards AB
- 6.4.7 Synaptics Incorporated
- 6.4.8 Suprema Inc.
- 6.4.9 Apple Inc.
- 6.4.10 Samsung Electronics Co., Ltd.
- 6.4.11 Qualcomm Incorporated
- 6.4.12 Gemalto N.V.
- 6.4.13 BioCatch Ltd.
- 6.4.14 Aware, Inc.
- 6.4.15 Cognitec Systems GmbH
- 6.4.16 DERMALOG Identification Systems GmbH
- 6.4.17 Vision-Box, S.A.
- 6.4.18 Precise Biometrics AB
- 6.4.19 IDEX Biometrics ASA
- 6.4.20 Innovatrics, s.r.o.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment