|
시장보고서
상품코드
2121287
블리스터 포장 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Blister Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 따르면 블리스터 포장 시장 규모는 2025년에 262억 8,000만 달러로 평가되며, 2026년 273억 8,000만 달러에서 2031년까지 335억 9,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 4.18%가 될 전망입니다.
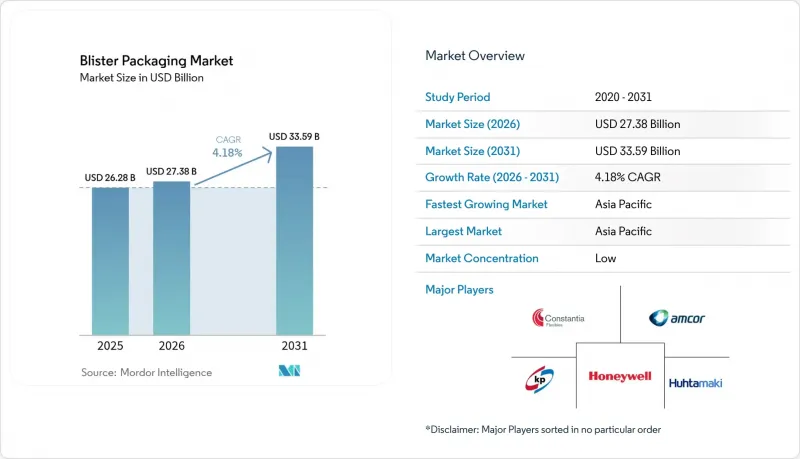
본 보고서는 공정(열성형, 냉간 성형), 소재(플라스틱 필름, 알루미늄, 종이 및 판지), 제품 유형(카드형/페이스 씰형 블리스터, 클램쉘형 블리스터, 트랩형·풀 카드형 블리스터, 기타), 최종사용자 산업(의약품, 뉴트라슈티컬·영양 보조 식품, 기타), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 블리스터 포장 시장의 동향 및 인사이트
고령 인구 증가 및 만성 질환 유병률 상승
2030년까지 전 세계 60세 이상 고령 인구는 56% 급증할 것으로 예측되며, 복약 순응도를 높이는 동시에 무단 개봉 방지 기능을 갖춘 사용하기 쉬운 블리스터 팩에 대한 수요가 증가하고 있습니다. 큰 글자, 색상 구분, 개봉하기 쉬운 설계와 같은 고령자용 디자인은 Drug Plastics Group과 같은 컨버터에 의해 상품화되고 있으며, 이 회사의 ‘Pop &Click’ 마개는 필요한 손의 힘을 약 4분의 1로 줄여줍니다. 당뇨병이나 심혈관질환 등의 만성 질환은 다회분 포장 채택을 더욱 촉진하고 있으며, 복잡한 복약 계획에 대해 명확한 시각적 단서를 제공하는 동시에, 블리스터 전문 제조업체의 고가 제품 판매를 뒷받침하고 있습니다.
단회 투여용 포장 및 복약 순응도 지원 포장에 대한 수요
병원, 약국, 재택의료 제공자들은 보험 급여를 복약 순응도 지표와 연계하는 경향이 강해지고 있어, 블리스터 기반 1회 투여 팩의 역할이 커지고 있습니다. Parata의 자동화 장비는 전자 의료 기록 플랫폼과 직접 연동되어 조제 오류를 줄이는 동시에 재포장 작업을 간소화하고 있습니다. 구강 분해형 OTC 제제에 대해 1회 투여 용기를 의무화하겠다는 FDA의 제안은, 1회 투여의 안전상 이점에 대한 규제 당국의 지지를 뒷받침하고 있습니다. 제약 브랜드들도 차별화를 꾀하기 위해 1회 투여용 블리스터를 활용하고 있으며, 브랜드 인지도 제고와 병 포장으로는 구현할 수 없는 위변조 방지 기능을 결합하고 있습니다.
변동이 심한 PVC·알루미늄 가격
2025년 중국의 PVC 수입 관세가 1%에서 5.5%로 급등함에 따라, 다운스트림 가공업체의 수지 비용이 상승했고, 정책 변경에 대한 취약성이 부각되었습니다. 인도의 가공업체들은 PVC 원료의 60%를 해외에서 조달하고 있어 여전히 위험에 노출되어 있으며, 헤지 및 후방 통합이 위험 관리의 핵심이 되고 있습니다. 알루미늄 포일 가격도 에너지 시장의 변동에 영향을 받아, 다년 계약을 체결할 수 있는 규모를 갖추지 못한 중소 블리스터 제조사들에게는 부담이 되고 있습니다.
부문 분석
2025년, 열성형은 전 세계 매출의 63.75%를 차지했으며, 제약 기업들이 낮은 금형 비용, 빠른 라인 속도, 다양한 필름 기판과의 호환성을 선호함에 따라 연간 5.54%의 성장이 전망됩니다. Brown Machine의 ‘쿼드 시리즈’ 열성형기는 현재 시간당 최대 25만 개의 뚜껑을 생산할 수 있는 한편, 에너지 사용량을 약 4분의 1로 줄여주어, 이를 통해 수탁 포장 업체에 생산성 향상을 가져다주며 블리스터 포장 시장의 성장세를 뒷받침하고 있습니다. 소규모 연구실도 GEA가 도입한 모듈식 기계를 통해 이 기술을 이용할 수 있게 되어, 공급업체 기반이 대형 다국적 기업 이외로도 확대되고 있습니다.
콜드폼 호일은 시장 점유율은 적지만, 습기나 빛에 민감한 분자에는 필수적입니다. 안정성 검사에서 수증기 투과율이 거의 제로여야 하는 경우, 제약 제조업체는 종종 알루미늄-알루미늄 구조를 지정합니다. 바이오의약품과 고효능 활성 성분이 보급됨에 따라 콜드폼의 도입 기반은 확대되고 있으며, 차단 성능을 저해하지 않으면서 무게를 줄이는 더 얇은 호일 및 하이브리드 라미네이트에 대한 연구 개발이 활발해지고 있습니다. 이러한 발전들이 맞물려 기술적 선택의 폭이 넓어짐에 따라, 블리스터 포장 시장은 대량 생산되는 제네릭 의약품과 틈새 전문 의약품 모두를 아우르는 범용성이 높은 플랫폼으로서의 입지를 공고히 하고 있습니다.
PVC, PET, PP를 중심으로 한 플라스틱 필름은 성숙한 공급망과 뛰어난 열 성형성 덕분에 2025년에는 블리스터 포장 매출의 67.52%를 차지했습니다. 그러나 화석 유래 소재에 대한 규제가 강화됨에 따라 종이 기반 솔루션이 시장 점유율을 빠르게 확대하고 있으며, 2031년까지 연평균 성장률(CAGR)은 7.02%를 기록할 전망입니다. TekniPlex는 현재 재생 소재를 30% 함유한 투명하고 재활용 가능한 중간 차단성 PET 블리스터를 제공하고 있으며, 이는 컨버터가 약전 규정을 준수하면서도 순환型 사회를 위한 노력을 추진하고 있음을 보여줍니다.
Rohrer의 ‘EcoVolve-30’과 같은 판지 블리스터는 섬유와 기능성 코팅을 결합하여 생산 라인의 성형 온도를 견디고 습기에 강한 정제를 보호합니다. 습기에 대한 민감성으로 인해 광범위한 대체는 제한되지만, 브랜드 소유주들은 비타민제, 영양 보충제, 유통 기한이 짧은 SKU에 종이 블리스터를 채택하여 환경에 대한 배려를 강조하고 있습니다. 앞으로 재료 과학의 발전에 따라, 섬유와 폴리머의 하이브리드 라미네이트가 더 높은 차단성이 필요한 카테고리에서도 채택될 것으로 예상됩니다. 이를 통해 블리스터 포장 시장의 규모 확대가 더욱 가속화될 뿐만 아니라, 재활용 소재 함유율에 관한 규제 요건도 충족하게 될 것입니다.
지역별 분석
아시아태평양은 2025년 매출의 40.95%를 차지하며 1위를 기록했고, 중국과 인도가 의약품 유효 성분(API) 생산을 확대하고 유럽 및 미국의 품질 기준을 준수함에 따라 연평균 성장률(CAGR) 7.29%로 다른 모든 지역을 앞지를 것으로 예상됩니다. WuXi STA의 새로운 타이싱(Taixing) API 공장과 계획 중인 싱가포르 내 확장 사업은 이 지역 내 제조 거점 확충을 보여주는 좋은 예이며, 기준을 준수하는 블리스터 포장 라인에 대한 현지 수요를 직접적으로 끌어올리고 있습니다. 중국이 수입 PVC에 대한 관세를 5.5%로 인상한 것은 국내 필름 압출 성형을 더욱 촉진하고, 동아시아 블리스터 포장 시장을 뒷받침하는 공급망의 현지화를 강화하고 있습니다.
북미는 여전히 기술적 지표 역할을 하고 있습니다. FDA의 엄격한 일련번호 부여 및 위조 방지 규제로 인해 스마트 형태의 프리미엄 마진이 유지되는 한편, 바이오의약품의 충전 및 포장 수요를 예상하여 기계 설비에 대한 투자가 확대되고 있습니다. PMMI는 2027년까지 포장기계 매출이 사상 최고치를 기록할 것으로 전망하고 있으며, 그중에서도 식음료 부문을 능가하는 성장이 예상되는 의약품 용도가 주도적인 역할을 할 것으로 보입니다. Amcor의 Berry Global 인수를 통해 연질 포장 및 경질 포장 역량이 단일 플랫폼으로 통합됨에 따라, 소규모 북미 컨버터들이 따라잡기 어려운 규모와 수직 통합이 확보될 것입니다.
유럽에서는 가장 엄격한 지속가능성 관련 법규가 적용되고 있습니다. 규정 2025/40에 따르면 2030년까지 PET 포장의 재활용 가능성과 30%의 재활용 소재 함유가 의무화되어, 순환 경제에 부합하는 설계에 대한 투자가 촉진되고 있습니다. TekniPlex가 전시한 투명하고 재활용 가능한 중간 차단성 블리스터는 EMA의 엄격한 차단 사양을 충족하면서 규정 준수 요건을 충족할 수 있는 길을 제시하고 있습니다. 임상 검사용 포장도 EU 규정 536/2014를 준수하고 있으며, 이에 따라 Catalent는 일본 시가 공장에 고속 블리스터 라인을 도입했습니다. 이 라인은 지역 간 임상 검사에 대응하고 있어, 규정 준수에 따른 수요가 전 세계적인 성격을 띠고 있음을 입증하고 있습니다. 그 결과, 소재 선택의 폭이 변화하고 있음에도 불구하고 유럽 내 블리스터 포장 시장 점유율은 견조한 모습을 유지하고 있습니다.
기타 혜택
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.03According to Mordor Intelligence, the blister packaging market size was valued at USD 26.28 billion in 2025 and estimated to grow from USD 27.38 billion in 2026 to reach USD 33.59 billion by 2031, at a CAGR of 4.18% during the forecast period (2026-2031).
This report is Segmented by Process (Thermoforming, Cold Forming), Material (Plastic Films, Aluminium, Paper and Paperboard), Product Type (Carded/Face-Seal Blisters, Clamshell Blisters, Trapped and Full-Card Blisters, and More), End-User Industry (Pharmaceuticals, Nutraceuticals and Dietary Supplements, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Blister Packaging Market Trends and Insights
Growing Geriatric Population and Chronic-Disease Prevalence
The global cohort aged 60 and above will surge 56% by 2030, intensifying demand for user-friendly blister packs that improve medication adherence while offering tamper evidence. Senior-centric designs-larger print, color coding, and low opening force-are being commercialized by converters such as Drug Plastics Group, whose Pop & Click closure reduces required hand pressure by roughly a quarter. Chronic conditions like diabetes and cardiovascular disease further amplify multi-dose pack adoption, enabling clear visual cues for complex regimes and reinforcing premium price realization for blister specialists.
Demand for Unit-Dose and Patient-Adherence Packs
Hospitals, pharmacies, and home-health providers increasingly link reimbursement to adherence metrics, elevating the role of blister-based unit-dose packs. Automated equipment from Parata now integrates directly with electronic health-record platforms, cutting dispensing errors while simplifying repack operations. The FDA's proposal to require single-unit containers for orally disintegrating OTC forms underscores regulatory endorsement of unit-dose safety benefits. Pharmaceutical brands also leverage unit-dose blisters for differentiation, combining brand visibility with tamper-evidence that bottles cannot replicate.
Volatile PVC and Aluminium Prices
China's jump in PVC import tariffs from 1% to 5.5% in 2025 lifted resin costs for downstream converters, spotlighting vulnerability to policy shifts. Indian converters remain exposed since 60% of their PVC feedstock is sourced abroad, making hedging and backward integration central to risk management. Aluminium foil prices also swing with energy markets, straining smaller blister firms that lack the scale to lock in multi-year contracts.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Tamper-Evident Formats
- Smart Blister Packs with NFC/QR for Track-and-Trace
- Tightening PVC Disposal/Recycling Legislation
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Thermoforming commanded 63.75% of global revenues in 2025 and will grow 5.54% a year as drug makers favor its low tooling cost, fast line speeds, and compatibility with diverse film substrates. Brown Machine's Quad-Series thermoformers now deliver up to 250,000 lids per hour while trimming energy use by roughly one-quarter, giving contract packers productivity gains that sustain the blister packaging market's momentum. Smaller laboratories gain access through modular machines introduced by GEA, broadening supplier bases beyond large multinationals.
Cold-form foil, though a minority share, is indispensable for moisture- or light-sensitive molecules. Drug makers often specify aluminium-aluminium structures when stability studies demand near-zero water vapor transmission. As biologics and high-potency actives proliferate, cold form's installed base expands, intensifying R&D into thinner foils and hybrid lamination that cut weight without compromising barrier. Together, these advances widen the technology palette, reinforcing the blister packaging market as a versatile platform for both mass-production generics and niche specialty drugs.
Plastic films, led by PVC, PET, and PP, accounted for 67.52% of blister revenues in 2025 thanks to mature supply chains and easy thermoformability. Yet heightened scrutiny of fossil-based materials is spurring rapid incremental gains for paper-based solutions, which log a 7.02% CAGR through 2031. TekniPlex now offers transparent recyclable mid-barrier PET blisters containing 30% recycled content, illustrating how converters preserve pharmacopoeial compliance while advancing circularity.
Paperboard entrants such as Rohrer's EcoVolve-30 use fiber plus functional coatings to withstand line forming temperatures and protect moisture-tolerant tablets. Although moisture sensitivity limits broad substitution, brand owners deploy paper variants in vitamins, nutraceuticals, and short shelf-life SKUs, bolstering eco-credentials. Over time, material science breakthroughs are expected to let hybrid fiber-polymer laminates secure higher-barrier categories, reinforcing the blister packaging market size trajectory and aligning with regulatory recycled-content mandates.
Complete Report Scope:
- By Process
- Thermoforming
- Cold Forming
- By Material
- Plastic Films (PVC, PET, PP, PE, rPET, COP, others)
- Aluminium (ALU-ALU, PTP foil)
- Paper and Paperboard
- By Product Type
- Carded / Face-Seal Blisters
- Clamshell Blisters
- Trapped and Full-Card Blisters
- Child-Resistant / Senior-Friendly Packs
- By End-User Industry
- Pharmaceuticals
- Nutraceuticals and Dietary Supplements
- Consumer Electronics and Hardware
- Personal Care and Cosmetics
- Other End-user Industry
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific led with 40.95% of 2025 revenue and will outpace all regions at 7.29% CAGR as China and India scale active-pharmaceutical-ingredient output and align with Western quality standards. WuXi STA's new Taixing API site and proposed Singapore expansion exemplify regional manufacturing build-out, directly lifting local demand for compliant blister lines. China's tariff hike on imported PVC to 5.5% further encourages domestic film extrusion, reinforcing supply-chain localization that underpins the blister packaging market in East Asia.
North America remains a technological bellwether. Stringent FDA serialization plus tamper-evidence rules sustain premium margins for intelligent formats, while machinery capex expands in anticipation of biologic fill-finish demand. PMMI projects packaging-machinery sales will hit record highs by 2027, with pharmaceutical applications outperforming food and beverage. Amcor's Berry Global acquisition consolidates flexible and rigid capabilities inside a single platform, ensuring scale and vertical reach that smaller North American converters will find hard to match.
Europe confronts the most aggressive sustainability legislation. Regulation 2025/40 enforces recyclability and 30% recycled content in PET packs by 2030, directing investment into circular-ready designs. TekniPlex's showcase of transparent recyclable mid-barrier blisters demonstrates compliance pathways that still satisfy stringent EMA barrier specifications. Clinical-trial packs also adapt to EU 536/2014, prompting Catalent to equip its Shiga, Japan, site with high-speed blister lines that serve pan-regional studies and underscore the global nature of compliance-driven demand. Consequently, the blister packaging market share in Europe remains resilient even as material choices evolve.
- Amcor plc
- WestRock Company
- Constantia Flexibles GmbH
- Klockner Pentaplast Group
- Sonoco Products Company
- DuPont de Nemours, Inc.
- Honeywell International Inc.
- Tekni-Plex, Inc.
- Dow Inc.
- Uflex Ltd.
- Huhtamaki Oyj
- Winpak Ltd.
- Bilcare Ltd.
- Bemis Company LLC (Amcor)
- Lotte Aluminium Co., Ltd.
- Toyo Aluminium K.K.
- Pharma Packaging Solutions
- R-Pharm Germany GmbH
- FormPaks Ltd.
- Zhejiang Hualian Pharmaceutical Co.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing geriatric population and chronic-disease prevalence
- 4.2.2 Demand for unit-dose and patient-adherence packs
- 4.2.3 Regulatory push for tamper-evident formats
- 4.2.4 Smart blister packs with NFC / QR for track-and-trace
- 4.2.5 Personalized-medicine small-batch blister lines
- 4.2.6 PVC-to-PE retrofit demand driven by sustainability
- 4.3 Market Restraints
- 4.3.1 Volatile PVC and aluminium prices
- 4.3.2 Tightening PVC disposal / recycling legislation
- 4.3.3 PVDC-resin supply bottlenecks
- 4.3.4 OTC stick-pack and sachet substitution
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Process
- 5.1.1 Thermoforming
- 5.1.2 Cold Forming
- 5.2 By Material
- 5.2.1 Plastic Films (PVC, PET, PP, PE, rPET, COP, others)
- 5.2.2 Aluminium (ALU-ALU, PTP foil)
- 5.2.3 Paper and Paperboard
- 5.3 By Product Type
- 5.3.1 Carded / Face-Seal Blisters
- 5.3.2 Clamshell Blisters
- 5.3.3 Trapped and Full-Card Blisters
- 5.3.4 Child-Resistant / Senior-Friendly Packs
- 5.4 By End-User Industry
- 5.4.1 Pharmaceuticals
- 5.4.2 Nutraceuticals and Dietary Supplements
- 5.4.3 Consumer Electronics and Hardware
- 5.4.4 Personal Care and Cosmetics
- 5.4.5 Other End-user Industry
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia and New Zealand
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Nigeria
- 5.5.4.2.3 Egypt
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 WestRock Company
- 6.4.3 Constantia Flexibles GmbH
- 6.4.4 Klockner Pentaplast Group
- 6.4.5 Sonoco Products Company
- 6.4.6 DuPont de Nemours, Inc.
- 6.4.7 Honeywell International Inc.
- 6.4.8 Tekni-Plex, Inc.
- 6.4.9 Dow Inc.
- 6.4.10 Uflex Ltd.
- 6.4.11 Huhtamaki Oyj
- 6.4.12 Winpak Ltd.
- 6.4.13 Bilcare Ltd.
- 6.4.14 Bemis Company LLC (Amcor)
- 6.4.15 Lotte Aluminium Co., Ltd.
- 6.4.16 Toyo Aluminium K.K.
- 6.4.17 Pharma Packaging Solutions
- 6.4.18 R-Pharm Germany GmbH
- 6.4.19 FormPaks Ltd.
- 6.4.20 Zhejiang Hualian Pharmaceutical Co.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment