|
시장보고서
상품코드
2125321
의약품 블리스터 포장 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Pharmaceutical Blister Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
에 의하면, 2026년 의약품 블리스터 포장 시장 규모는 249억 7,000만 달러로 추정되고, 2025년 233억 1,000만 달러에서 성장하여 2031년에는 351억 7,000만 달러에 이를 것으로 예측됩니다.
2026-2031년 연평균 성장률(CAGR)은 7.10%를 나타낼 전망입니다.
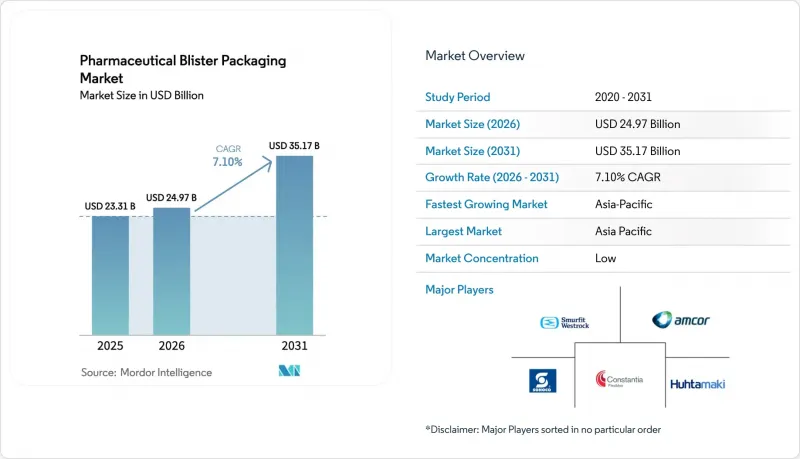
본 보고서는 소재별(플라스틱, 종이 및 판지, 알루미늄 포일), 기술별(냉간 성형, 열 밀봉/열 수축, 열 성형), 용도별(정제, 캡슐 등), 최종 사용자별(브랜드 의약품/제네릭 의약품 제조업체 등), 지역별(북미, 유럽, 아시아태평양, 중동 및 아프리카, 남미)로 분류되어 있습니다.
세계의 의약품 블리스터 포장 시장 동향 및 인사이트
단회 투여용 복약 순응도 팩 수요 증가
규제 당국은 1회 투여 형식을 투약 오류를 줄이는 효과적인 방법으로 간주하고 있으며, FDA가 제안한 규칙안에 따르면 시판되는 구강 내 분해 정제 및 필름은 1회 투여 포장 형태로만 출하해야 할 의무가 부과됩니다. 병원 및 소매점의 약사들도 시각적인 투여 기준이 고령자의 복약 누락을 줄인다는 사실을 확인하고 있습니다. 보험사들도 재입원 위험 감소를 환영하고 있으며, 이것이 보험 급여 인센티브의 기반이 되고 있습니다. 이에 대응하여 위탁 포장 업체들은 하나의 블리스터 카드에 1일 분량의 투약량을 모두 담을 수 있는 다제품 대응 블리스터 라인을 추가하고 있습니다. 이러한 효과는 북미에서 가장 먼저 나타나고 있지만, 전자 처방전 플랫폼에 복약 순응도 데이터가 통합됨에 따라 유럽에서도 유사한 움직임이 나타나고 있습니다.
재활용 가능한 고차단성 플라스틱의 채택 확대
EU의 ‘포장 및 포장 폐기물 규정’에 따르면, 2030년 이후 시장에 출시되는 모든 의료용 포장은 재활용 가능한 설계로 제작되어야 합니다. TekniPlex와 같은 공급업체들은 현재 방습성을 저해하지 않으면서 30%의 소비 후 재생 수지를 함유한 중간 차단성 블리스터 필름을 상용화하고 있습니다. Borealis사의 ‘Bornewables’ 등급은 재생 가능한 원료로 제조되어, 탄소 발자국 감축을 목표로 하는 제조업체에 원산지가 관리된 폴리머 옵션을 제공합니다. 일본의 가공업체들은 호일 스크랩을 회수하여 펠릿으로 재용해하는 폐쇄형 루프 시스템을 도입하고 있으며, 이를 통해 버진 소재를 사용할 때와 비교해 CO₂ 배출량을 약 20% 줄이고 있습니다.
알루미늄·폴리머 원료 가격 변동
알루미늄 포일은 블리스터 포장의 대표적인 차단재이지만, 지정학적 관세 및 중국의 수출 정책 전환에 따른 가격 급등에 직면해 있습니다. 유럽의 알루미늄 포일 제조업체들은 2024년 9개월간의 생산량이 약 72만 4천 톤에 달했다고 보고하고 있지만, 에너지 가격 급등으로 인해 공급은 여전히 핍박하고 있습니다. 수지 제조업체들도 나프타 가격 급등분을 PVC 및 PET 등급 가격에 전가하고 있습니다. 브랜드 소유주들은 동남아시아 및 라틴아메리카로 조달처를 다각화하는 한편, 차단 성능을 저해하지 않으면서 알루미늄 포일의 두께를 줄일 수 있는 폴리프로필렌계 라미네이트에 대한 시험을 진행하고 있습니다.
부문 분석
성숙한 PVC-PVDC 밸류체인과 검증된 열성형 특성에 힘입고 있습니다. 플라스틱 제약용 블리스터 포장 시장 규모는 낮은 성형 온도와 예측 가능한 밀봉 강도를 중시하는 대량 생산 제네릭 의약품과 연동되어 있습니다. 그러나 브랜드 소유주들이 가정 쓰레기로서의 재활용 가능성이나 Scope 3 배출량 감축을 요구함에 따라, 종이 기반 구조가 탄력을 받고 있습니다. 얇은 폴리머 층 또는 알루미늄 층으로 코팅된 판지 라미네이트는 현재 9개월의 보관 기간 성능에 근접하고 있으며, 그 용도는 비타민제에서 처방전이 필요한 소화기 계통 의약품으로 확대되고 있습니다.
알루미늄·플라스틱 재질의 냉간 성형용 호일에 대한 수요는 깊은 드로잉 캐비티가 습기에 민감한 화합물을 보호하기 때문에 여전히 견조합니다. 그러나 각 변환 업체들이 더 적은 양의 금속으로 동등한 차단 성능을 발휘하는 나노층 코팅을 채택함에 따라, 호일의 두께는 얇아지는 추세입니다. Ecobliss사의 콜드 씰 카드는 압력으로 작동하는 접착제를 사용하여 가열 공정이 필요 없게 되어, 포장실의 에너지 소비를 줄일 수 있음을 보여줍니다. TekniPlex사의 PCR(재활용 플라스틱)을 30% 함유한 블리스터 필름은 수지 재활용의 방향성을 보여주고 있으며, 약사가 육안 검사에 선호하는 투명성을 유지하고 있습니다.
2025년, 열성형은 의약품 블리스터 포장 시장 점유율의 72.45%를 차지했습니다. 이는 높은 라인 속도와 육안 확인이 가능한 투명한 캐비티를 제공하기 때문입니다. 폼-필-씰(FFS) 라인은 블록버스터급 정제의 생산량에 부응하기 위해 분당 600팩을 지속적으로 처리하고 있습니다. 그러나 습기에 민감한 API(유효 성분)의 존재로 인해 제조업체들은 수증기 투과율이 거의 제로에 가까운 알루미늄 포일을 사용하는 콜드 성형으로 전환해야 할 압박을 받고 있습니다. 원자재 비용 상승에도 불구하고, 전문 제네릭 의약품 및 희귀질환 치료제 생산량이 증가함에 따라 콜드 성형 라인용 의약품 블리스터 포장 시장 규모는 확대되고 있습니다.
현재 콜드 성형 장비 공급업체들은 서보 구동 인덱서를 통합하고 있으며, 이를 통해 알루미늄 포일의 사용 효율이 향상되어 스크랩을 최대 15%까지 줄이고 있습니다. Aptar CSP Technologies는 추가 소포를 사용하지 않고 가수분해를 방지하는 내장형 건조제 채널에 대한 지역적 수요에 부응하기 위해 유럽에서 Active Blister 생산을 확대했습니다. 연속 생산을 주창하는 이들은 정제가 타블렛 성형 공정을 마치고 중량 검사를 거쳐 몇 분 이내에 블리스터 밀봉 공정에 도달하는 ‘분말에서 포장까지’의 일관 생산 라인을 추진하고 있으며, 이를 통해 홀드 타임 검증을 최소화하고 있습니다.
지역별 분석
아시아태평양은 2025년에 전 세계 매출의 33.97%를 차지하며 1위를 차지했으며, 2031년까지 연평균 성장률(CAGR) 8.87%를 나타낼 것으로 보입니다. 인도, 중국, 싱가포르 정부는 자동화 포장 라인에 대해 세액 공제 조치를 시행하고 있는 반면, 현지 CDMO 기업들은 유럽의 제네릭 의약품 공급 계약을 수주하고 있습니다. 일본공급업체들은 ‘인터펙스 도쿄’에서 투명 배리어 필름과 AI 검사에 초점을 맞추어, 디지털 도구가 불량률을 어떻게 낮추는지 밝혔습니다. PIC/S GMP와의 지역적 조화를 통해 국경을 초월한 유통이 가속화되고 있으며, 다국적 기업들은 단일 패키지를 여러 아세안 시장에서 검증할 수 있게 되었습니다.
북미는 고부가가치 바이오의약품 파이프라인과 스마트 어드히어런스 팩의 조기 도입을 통해 2위 자리를 차지하고 있습니다. 또한 미국은 공급망을 단축하고 지정학적 위험을 헤지하는 리쇼어링 움직임의 혜택도 받고 있습니다. 알루미늄 관세 재도입으로 인해 각 컨버터 기업들은 국내 호일 압연 능력을 확보하거나 폴리머 기반 뚜껑 소재로 전환함으로써 수입 가격 변동에 따른 위험을 완화하고 있습니다. 캐나다 시설에서는 재생 가능 전력을 도입하여, 공공 보험사로부터 지지를 얻을 수 있는 ‘탄소 중립’ 포장이라는 슬로건을 내세울 수 있게 되었습니다. 유럽은 엄격한 품질 기준과 지속 가능한 소재에 대한 투자를 통해 여전히 큰 시장 점유율을 유지하고 있습니다. TekniPlex사의 모데나 신공장에서는 중간 수준의 차단성을 가진 PCR 필름이 추가되었으며, Faller Packaging사는 전단지 수요에 대응하기 위해 독일 내에서 접이식 카톤 생산 공간을 확대되고 있습니다. 이 지역의 순환 경제에 관한 지침에 따라, 파란색 쓰레기통 수거 제도의 대상이 되는 단일 소재 블리스터 팩의 시범 도입이 진행되고 있습니다. 동유럽의 위탁 포장 업체들은 EU의 ‘자격 있는 자(Qualified Person)’의 승인을 필요로 하는 중소규모 혁신 기업들을 위해 비용 부담을 줄여주고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJYAccording to Mordor Intelligence, pharmaceutical blister packaging market size in 2026 is estimated at USD 24.97 billion, growing from 2025 value of USD 23.31 billion with 2031 projections showing USD 35.17 billion, growing at 7.10% CAGR over 2026-2031.
This report is Segmented by Material (Plastic, Paper and Paperboard, and Aluminum Foil), Technology (Cold Form, Heat-Seal / Heat-Shrink, and Thermoforming), Application (Tablets, Capsules, and More), End-User (Branded / Generic Pharma Manufacturers, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, and South America).
Global Pharmaceutical Blister Packaging Market Trends and Insights
Rise in demand for unit-dose adherence packs
Regulators see unit-dose formats as an effective way to lower dosing errors, so proposed FDA rules would require over-the-counter orally disintegrating tablets and films to ship only in single-unit packaging. Hospital and retail pharmacists confirm that visual dose cues reduce skipped administrations among seniors. Payers also welcome lower readmission risk, which anchors reimbursement incentives. Contract packers respond by adding multi-product blister lines that let one card hold an entire daily regimen. The effect is quickest in North America, but Europe follows as e-prescription platforms integrate adherence data.
Growing adoption of recyclable high-barrier plastics
The EU Packaging and Packaging Waste Regulation mandates that all healthcare packs placed on the market after 2030 must be designed for recycling. Suppliers such as TekniPlex now commercialize mid-barrier blister films containing 30% post-consumer resin without sacrificing moisture protection. Borealis' Bornewables grades, produced from renewable feedstock, give origin-controlled polymer options to manufacturers seeking carbon-footprint cuts. Japanese converters add closed-loop systems that collect foil scrap and re-smelt it into pellets, cutting CO2 emissions nearly 20% versus virgin routes.
Volatility in aluminum and polymer feed-stock prices
Aluminum foil is the classic blister barrier but faces price spikes linked to geopolitical tariffs and Chinese export policy shifts. Europe's foil mills reported almost 724 thousand tonnes of nine-month output in 2024, yet supply still tightened after energy-price shocks. Resin makers also pass higher naphtha costs into PVC and PET grades. Brand owners diversify sourcing toward Southeast Asia and Latin America and test polypropylene-based laminates that cut foil gauge without hurting barrier performance.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of chronic-disease oral therapies worldwide
- Aging population boosting OTC solid-dose demand
- Heightened scrutiny on novel-film extractables and leachables
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
supported by mature PVC-PVDC supply chains and proven thermoforming behavior. The pharmaceutical blister packaging market size for plastics aligns with high-volume generic production that values low forming temperatures and predictable seal integrity. Yet paper-based structures are gaining momentum because brand owners want curbside recyclability and lower Scope 3 emissions. Paperboard laminates coated with thin polymer or aluminum layers now approach nine-month shelf-life performance, expanding their use beyond vitamins into prescription gastroenterology drugs.
Demand for aluminum-plastic cold-form foil remains solid because deep-draw cavities shield moisture-sensitive compounds. However, foil gauges are trending lower as converters add nanolayer coatings that deliver equal barrier with less metal. Cold-seal cards from Ecobliss illustrate how pressure-activated adhesive eliminates heat while cutting energy consumption in pack rooms. TekniPlex's 30% PCR blister films demonstrate the direction of resin circularity and keep clarity that pharmacists prefer for visual inspection.
Thermoforming owned 72.45% of the pharmaceutical blister packaging market share in 2025 because it offers high line speeds and clear cavities that support visual confirmation. Form-fill-seal lines routinely cross 600 packs per minute, matching blockbuster tablet volumes. Even so, moisture-sensitive APIs push manufacturers toward cold-forming where aluminum foil delivers near-zero water vapor transmission rates. The pharmaceutical blister packaging market size for cold-form lines grows as specialty generics and orphan-drug volumes climb, despite higher material costs.
Cold-form equipment vendors now integrate servo-driven indexers that improve foil usage, trimming scrap by up to 15%. Aptar CSP Technologies expanded its Active Blister production into Europe to meet regional demand for built-in desiccant channels that prevent hydrolysis without extra sachets. Continuous-manufacturing advocates link powder-to-pack trains where tablets exit compression, pass through weight checks, and reach blister sealing within minutes, minimizing hold-time validation.
Complete Report Scope:
- By Material
- Plastic
- Aluminum Foil
- Paper and Paperboard
- By Technology
- Thermoforming
- Cold-form
- Heat-seal / Heat-shrink
- By Application
- Tablets
- Capsules
- Oral Thin Films and Lozenges
- Diagnostic Kits and Others
- By End-User
- Branded / Generic Pharma Manufacturers
- Contract Development and Manufacturing Organizations (CDMOs)
- Contract Packaging Organizations (CPOs)
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific led with 33.97% of global revenue in 2025 and shows a 8.87% CAGR through 2031. Governments in India, China, and Singapore offer tax credits for automated packaging lines, while local CDMOs win supply contracts for Europe's generics. Japanese suppliers spotlight transparent barrier films and AI inspection at Interphex Tokyo, revealing how digital tools shrink defect rates. Regional harmonization with PIC/S GMP accelerates cross-border distribution, so multinationals can validate a single pack across several ASEAN markets.
North America ranks second due to high-value biologic pipelines and the early rollout of smart adherence packs. The United States also benefits from reshoring moves that shorten supply chains and hedge geopolitical risk. Aluminum tariff reinstatements push converters to secure domestic foil rolling capacity or switch to polymer-based lidding, limiting exposure to import price swings. Canadian facilities integrate renewable electricity, enabling carbon-neutral pack claims that resonate with public payers. Europe maintains significant share thanks to strict quality norms and investment in sustainable materials. TekniPlex's new Modena plant adds mid-barrier PCR film, while Faller Packaging expands folding-carton space in Germany to handle leaflet demand. The region's circular-economy directives drive trials of mono-material blisters that qualify for blue-bin collection schemes. Eastern European contract packers provide cost relief for small and mid-sized innovators seeking EU Qualified Person release.
- Amcor plc
- Smurfit Westrock
- Constantia Flexibles
- Sonoco Products Company
- Huhtamaki Oyj
- Tekni-Plex Inc.
- ACG Pharmapack
- Aptar CSP Technologies
- Klockner Pentaplast
- Perlen Packaging
- Honeywell International (Aclar Films)
- Bilcare Research
- Bemis Healthcare (now Amcor Flexibles)
- Uhlmann Packaging Systems
- IMA Group
- Syntegon Technology
- Marchesini Group
- Romaco Group
- PharmaWorks (ProMach)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rise in demand for unit-dose adherence packs
- 4.2.2 Growing adoption of recyclable high-barrier plastics
- 4.2.3 Expansion of chronic-disease oral therapies worldwide
- 4.2.4 Aging population driving OTC solid-dose demand
- 4.2.5 Emergence of smart, sensor-enabled "digital blister" packs
- 4.2.6 Continuous-manufacturing lines integrating inline blistering
- 4.3 Market Restraints
- 4.3.1 Regulatory bans/taxes on single-use plastics
- 4.3.2 Volatility in aluminum and polymer feed-stock prices
- 4.3.3 Heightened scrutiny on novel-film extractables and leachables
- 4.3.4 Geopolitical disruption of aluminum-foil supply chains
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Sustainability and Recycling Trends
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Plastic
- 5.1.2 Aluminum Foil
- 5.1.3 Paper and Paperboard
- 5.2 By Technology
- 5.2.1 Thermoforming
- 5.2.2 Cold-form
- 5.2.3 Heat-seal / Heat-shrink
- 5.3 By Application
- 5.3.1 Tablets
- 5.3.2 Capsules
- 5.3.3 Oral Thin Films and Lozenges
- 5.3.4 Diagnostic Kits and Others
- 5.4 By End-User
- 5.4.1 Branded / Generic Pharma Manufacturers
- 5.4.2 Contract Development and Manufacturing Organizations (CDMOs)
- 5.4.3 Contract Packaging Organizations (CPOs)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Russia
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia and New Zealand
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 United Arab Emirates
- 5.5.4.1.2 Saudi Arabia
- 5.5.4.1.3 Turkey
- 5.5.4.1.4 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Nigeria
- 5.5.4.2.3 Egypt
- 5.5.4.2.4 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 Smurfit Westrock
- 6.4.3 Constantia Flexibles
- 6.4.4 Sonoco Products Company
- 6.4.5 Huhtamaki Oyj
- 6.4.6 Tekni-Plex Inc.
- 6.4.7 ACG Pharmapack
- 6.4.8 Aptar CSP Technologies
- 6.4.9 Klockner Pentaplast
- 6.4.10 Perlen Packaging
- 6.4.11 Honeywell International (Aclar Films)
- 6.4.12 Bilcare Research
- 6.4.13 Bemis Healthcare (now Amcor Flexibles)
- 6.4.14 Uhlmann Packaging Systems
- 6.4.15 IMA Group
- 6.4.16 Syntegon Technology
- 6.4.17 Marchesini Group
- 6.4.18 Romaco Group
- 6.4.19 PharmaWorks (ProMach)
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment