|
시장보고서
상품코드
2121379
벽면 마감재 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Wall Covering - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
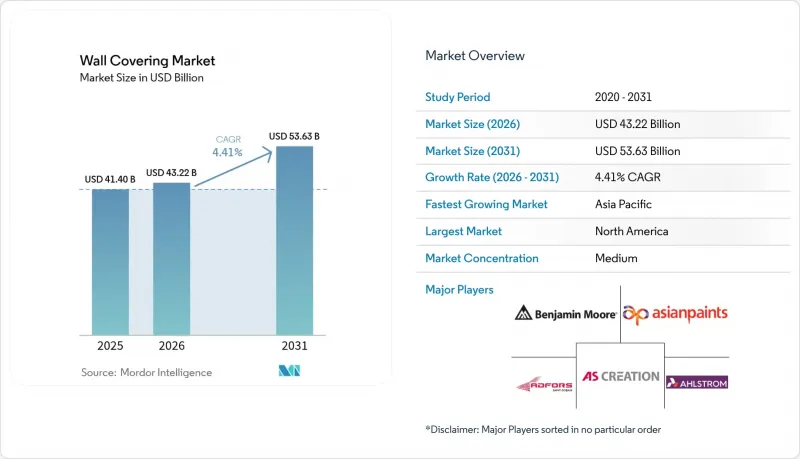
에 의하면, 벽면 마감재 시장 규모는 2025년에 414억 달러로 평가되었고, 2026년 432억 2,000만 달러에서 2031년까지 536억 3,000만 달러에 이를 것으로 예측되며, 예측 기간(2026년-2031년) CAGR은 4.41%를 기록할 전망입니다.
본 보고서는 소재별(종이 계열, 천·섬유 계열, 목재 계열 등), 제품 유형별(벽 패널, 벽지, 타일 등),최종 이용 산업별(호텔·리조트, 의료, 소매, 기업 사무실 등), 유통 채널별(전문점, 프랜차이즈 매장 등), 지역별(북미, 남미 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
전 세계 벽장식재 시장 동향 및 인사이트
급속한 도시 재생 주기가 상업 수요를 견인
사무실 소유주와 호텔 운영사는 공실 기간을 단축하고 진화하는 업무 공간 기준에 부합하기 위해 인테리어 개보수를 앞당겨 진행하고 있습니다. 가동 중단 시간을 최소화하면서 방음 성능을 높이는 모듈식 벽 시스템이 선호되는 사양으로 자리 잡고 있습니다. 쇼 인더스트리즈(Show Industries)와 PPG의 통합형 바닥재에 관한 제휴는 공급업체들이 리모델링 범위를 더 폭넓게 담당하려는 움직임을 보여줍니다. 탈케트(Tarkett)가 조안 카너 여성·소아 병원에 35,000 m2의 비닐 바닥재를 시공한 사례는 신속한 의료시설 프로젝트에서 규모의 경제를 보여줍니다. 이러한 동향은 신속한 시공, 단계적 증설, 원스톱 자재 조달에 대한 수요를 높이고 있으며, 이 모든 요소가 벽면 마감재 시장을 견인하고 있습니다.
비닐 안감의 필 앤 스틱 제품 부상이 주택 시장을 변화시키고 있습니다.
비닐 뒷면이 있는 필 앤 스틱(Peel & Stick) 제품은 시공 시간을 몇 분으로 단축하고 접착제를 불필요하게 함으로써, 임차인들까지 유력한 구매층으로 변화시키고 있습니다. ‘Tempaper’, ‘RoomMates’, ‘Astek’과 같은 브랜드들은 시공이 복잡하다는 이미지를 불식시키는 인플루언서 대상 컬렉션을 선보였습니다. Drytac사의 2024년판 ‘PVC 프리·페이퍼 프리 스무스’는 소비자의 사용 편의성을 해치지 않으면서도 지속가능성에 대한 관심에 부응하고 있습니다. 온라인에서 화제가 된 ‘시공 전·시공 후’ 동영상은 큰 마케팅 효과를 가져왔으며, 필 앤 스틱 제품을 벽지 시장에서 전략적인 발판으로 확고히 자리매김하게 했습니다.
PVC 및 석유화학 원자재 가격 변동이 이익률을 압박
에틸렌과 염화비닐 가격의 급등으로 인해 비닐 제품의 원가 곡선은 예측 불가능한 상황에 놓여 있습니다. 올비아(Orbia)가 2025년 초에 발표한 원가 합리화 방안은 각 제조업체가 간접비 절감 및 제품 포트폴리오 재검토를 통해 원자재 가격 변동에 대처하고 있음을 보여줍니다. 아시아의 PVC 현물 시장은 더욱 혼란에 빠지고 있으며, 수출 지향적인 가공업체들은 환율 및 운임의 급격한 변동에 따른 충격을 받고 있습니다. 바이오 라미네이트로의 전환은 리스크 헤지 수단이 되지만, 생산 능력 확대에는 여전히 막대한 자본이 필요하여 벽지 시장의 단기적인 완화는 지연되고 있습니다.
부문 분석
비닐은 내수성, 인쇄의 범용성 및 저렴한 시공 비용을 강점으로 2025년에는 벽면 마감재 시장 점유율의 37.78%를 차지했습니다. 목재 부문의 연평균 성장률(CAGR) 6.17%는 바이오필릭 디자인 및 친환경 라벨로의 전환을 여실히 보여주고 있으며, 코르크, 대나무, 엔지니어드 우드 베니어는 상업시설의 사양 결정권자들을 사로잡는 엄격한 저VOC 기준을 충족하고 있습니다. 비닐 공급업체들은 바이오 소재가 벽면 마감재 시장에 진입함에 따라 재활용 프로그램과 초저배출 가소제로 대응하며 입지를 유지하고자 노력하고 있습니다.
생산 규모가 경쟁의 속도를 결정하고 있습니다. IZODEKOR사의 3D 패널 연간 생산량 75만 m²는 혁신 지향적인 기업의 풍부한 자본력을 여실히 보여줍니다. Kirkby Design사가 2025년에 출시할 재생 면 제품은 직물의 질감과 재생 소재를 융합하여, 부티크 호텔 및 고급 주택 시장을 겨냥한 패브릭 벽면 마감재의 대안으로서 입지를 확고히 하고 있습니다. 비닐의 기존 설치 기반과 강화되는 환경 기준 간의 대립이 2031년까지 벽장식재 시장에서 소재 점유율의 변동을 좌우할 것입니다.
2025년, 벽지는 벽면 마감 시장 규모의 38.95%를 차지했으며, 다양한 패턴과 내구성에 대한 요구를 충족시키는 비닐, 부직포, 직물 등의 기질이 사용되었습니다. 한편, 벽 패널은 음향 제어 기능과 시공 시간을 단축하는 신속한 클립식 설치 방식을 겸비하고 있어 연평균 성장률(CAGR) 5.28%로 다른 모든 형태를 능가하는 성장이 예상됩니다.
오픈 플랜 사무실이나 학교에서는 소음 저감에 대한 수요가 높아지고 있어, 뉴욕 사운드프루핑(New York Soundproofing)과 같은 제조업체들은 디자인성을 중시한 음향 제품 라인 확충을 서두르고 있습니다. 아미코 아키텍처럴(Amico Architectural)이 담당한 메드트로닉스(Medtronic)의 의료시설 인테리어 공사는 모듈식 패널을 통해 장기간의 휴업 없이도 대규모 공사를 신속하게 진행할 수 있음을 입증했습니다. 이러한 추세에 따라 벽 패널은 벽면 마감재 시장에서 틈새 시장 제품에서 주류로 자리매김하고 있습니다.
지역별 분석
북미는 견조한 상업시설 리모델링 수요, 광범위한 유통 네트워크, 그리고 선진적인 에너지 및 실내 공기질 관련 규제를 배경으로 2025년에 지역별 최대 매출을 기록했습니다. 미국에서는 기업의 사무실 재배치 및 호텔·리조트 업계의 로비 개보수 지출이 프리미엄 가격대를 지탱하고 있는 반면, 캐나다는 의료 및 교육 분야의 시설 개보수 수혜를 받고 있습니다. 멕시코에서는 쇼핑몰 및 리조트 시설 건설 계획을 통해 벽면 마감재 시장에 저-중가대의 안정적인 수요를 창출하고 있습니다.
아시아태평양은 중국의 인프라 투자 급증, 인도의 중산층 주택 확대, 그리고 동남아시아의 호스피탈리티 회랑 성장에 힘입어 세계 최고 수준인 연평균 성장률(CAGR) 7.86%를 달성할 것으로 예측됩니다. 저렴한 가격의 필 앤 스틱(peel & stick) 방식 벽지는 도시 지역의 첫 주택 구매자들 사이에서 인기를 끌고 있는 반면, 성숙한 고급 시장에서는 일본과 호주의 디자이너들이 웰빙 목표를 달성하기 위해 바이오 벽장식재를 지정하고 있습니다. 규제 조화와 모듈식 흡음 패널에 대한 선호도 증가로 인해, 벽면 마감재 시장은 해당 지역의 A급 오피스 건설 주기에 더욱 깊이 침투하고 있습니다.
유럽에서는 지속가능성을 원동력으로 하는 성장 궤도를 유지하고 있습니다. 독일과 프랑스에서는 EPD(환경 제품 선언) 및 순환 경제 관련 규제가 강화됨에 따라 PVC가 포함되지 않은 라미네이트 소재의 채택이 앞서고 있습니다. 영국의 호텔 브랜드는 2-3년마다 인테리어를 새롭게 단장하고 있어 안정적인 리모델링 수요를 창출하고 있습니다. 이탈리아와 스페인은 디자인 노하우와 소량 디지털 인쇄 능력을 제공합니다. 남미에서는 브라질과 아르헨티나의 복합 시설을 중심으로 수요가 싹트기 시작하고 있는 반면, 중동 및 아프리카에서는 UAE의 레저 허브와 ‘사우디 비전 2030’에 기반한 공공 부문 투자를 중심으로 성장이 집중되고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.08According to Mordor Intelligence, the wall covering market size was valued at USD 41.40 billion in 2025 and estimated to grow from USD 43.22 billion in 2026 to reach USD 53.63 billion by 2031, at a CAGR of 4.41% during the forecast period (2026-2031).
This report is Segmented by Material (Paper-Based, Fabric/Textile, Wood-Based, and More), Product Type (Wall Panel, Wallpaper, Tile, and More), End-Use Industry (Hospitality, Healthcare, Retail, Corporate Offices, and More), Distribution Channel (Specialty Store, Franchise Store, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Wall Covering Market Trends and Insights
Rapid Urban Refurbishment Cycles Drive Commercial Demand
Office landlords and hotel operators are front-loading interior upgrades to shorten vacancy periods and conform to evolving workspace standards. Modular wall systems that minimize downtime while boosting acoustics have become preferred specifications. Shaw Industries' pact with PPG for integrated flooring demonstrates supplier moves to own more of the renovation scope. Tarkett's 35,000 m2 vinyl installation at Joan Kirner Women's and Children's Hospital signals scale benefits in fast-track healthcare projects. These dynamics reinforce a premium on rapid installation, phased build-outs, and one-stop material sourcing, all of which propel the wall covering market.
Rise of Vinyl-Backed Peel-and-Stick Solutions Transforms Residential Market
Vinyl-backed peel-and-stick products trim install time to minutes and eliminate adhesives, turning renters into viable purchasers. Brands such as Tempaper, RoomMates, and Astek promoted influencer-ready collections that remove perceived complexity. Drytac's 2024 PVC-free Paper Fleece Smooth iteration keeps pace with sustainability rhetoric without compromising consumer ease. Viral "before-and-after" clips deliver outsized marketing returns, cementing peel-and-stick as a strategic foothold in the wall covering market.
Volatility in PVC and Petrochemical Feedstock Prices Pressures Margins
Spiking ethylene and chloride values make vinyl cost curves unpredictable. Orbia's early-2025 cost rationalization shows manufacturers countering raw-material swings through overhead cuts and portfolio shifts. Asian PVC spot markets add extra turbulence, exposing export-oriented converters to exchange-rate and freight shocks. Substitution toward bio-based laminates offers a hedge, but scaling capacity remains capital intensive, slowing short-term relief in the wall covering market.
Other drivers and restraints analyzed in the detailed report include:
- Commercial Demand for Modular Acoustic Wall Panels Accelerates
- Growth of DIY Decor Influencers on Social Media Reshapes Consumer Behavior
- High Landfill Cost of Demolition Waste Adds Disposal Burdens
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Vinyl contributed 37.78% wall covering market share in 2025 on the strength of water resistance, print versatility, and modest install costs. The wood category's 6.17% CAGR underscores a pivot toward biophilic design and eco labels, with cork, bamboo, and engineered timber veneers meeting stringent low-VOC limits that attract commercial specifiers. Vinyl suppliers counter with recycling programs and ultralow-emission plasticizers, seeking to retain position as bio-based materials bite into the wall covering market.
Production scale sets the competitive pace. IZODEKOR's 750,000 m2 annual output of 3-D panels highlights capital depth among innovation-minded players. Kirkby Design's 2025 recycled-cotton launch fuses textile feel with reclaimed content, positioning fabric-wall alternatives for boutique hotels and premium residential niches. The tug-of-war between vinyl's installed base and rising eco criteria will define material share shifts within the wall covering market through 2031.
Wallpaper accounted for 38.95% of the wall covering market size in 2025, spanning vinyl, non-woven, and fabric backings that suit diverse pattern and durability needs. Wall panels, however, are projected to outpace all other formats at a 5.28% CAGR because they marry acoustic control with rapid clip-on installation that compresses labor hours.
Open-plan offices and schools intensify the call for noise mitigation, pushing producers like New York Soundproofing to amplify design-forward acoustic lines. Amico Architectural's Medtronics health-care fitout underscores how modular panels accelerate large-footprint jobs without extended shutdowns. These dynamics lift wall panels from niche to mainstream status inside the wall covering market.
Complete Report Scope:
- By Material
- Paper-Based
- Fabric/Textile
- Wood-Based
- Vinyl
- Other Materials
- By Product Type
- Wall Panel
- Wallpaper
- Vinyl Wallpaper
- Non-woven Wallpaper
- Paper-based Wallpaper
- Fabric Wallpaper
- Other Wallpaper Types
- Tile
- Metal Wall Covering
- Other Product Types
- By End-use Industry
- Hospitality
- Healthcare
- Retail
- Corporate Offices
- Education
- Domestic Housing
- Industrial Facilities
- Other End-use Industries
- By Distribution Channel
- Specialty Store
- Franchise store
- E-commerce
- Other Distribution Channels
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Spain
- Italy
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America recorded the largest regional revenue in 2025 on the back of robust commercial remodel demand, deep distribution networks, and progressive energy and indoor-air codes. United States spending on corporate re-stacking and hospitality lobbies sustains premium price points, while Canada benefits from institutional upgrades in healthcare and education. Mexico adds steady low-to-mid-grade volume to the wall covering market through shopping-mall and resort pipelines.
Asia-Pacific is projected to deliver a 7.86% CAGR, the fastest worldwide, powered by China's infrastructure surge, India's expanding middle-class housing, and Southeast Asian hospitality corridor growth. Affordable peel-and-stick wallpaper gains traction among first-time urban homeowners, while Japanese and Australian designers specify bio-based wall coverings to meet wellness objectives in mature high-end markets. Regulatory harmonization and rising preference for modular acoustic panels push the wall covering market deeper into the region's grade-A office buildout cycle.
Europe maintains a sustainability-driven trajectory. Germany and France head adoption of PVC-free laminates under tightened EPD and circular-economy rules. United Kingdom hotel brands re-skin interiors every two to three years, channeling consistent retrofit flow. Italy and Spain contribute design know-how and small-batch digital-print capacity. South America shows incipient demand focused on Brazilian and Argentine mixed-use complexes, whereas the Middle East and Africa cluster growth around UAE leisure hubs and Saudi Vision 2030 public-sector investments.
- Saint-Gobain Adfors SA
- Ahlstrom-Munksjo Oyj
- AS Creation Tapeten AG
- Asian Paints Limited
- Benjamin Moore & Co.
- Brewster Home Fashions LLC
- York Wallcoverings, Inc.
- J. Josephson Inc.
- Walker Greenbank PLC
- Grandeco Wallfashion Group NV
- Graham & Brown Ltd.
- F. Schumacher & Co. LLC
- Rasch GmbH & Co. KG
- Mohawk Industries, Inc.
- Armstrong World Industries, Inc.
- 3M Company
- Ceramiche Caesar S.p.A.
- Shaw Industries Group, Inc.
- Interface, Inc.
- Kingfisher plc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rapid urban refurbishment cycles
- 4.2.2 Rise of vinyl-backed peel-and-stick solutions
- 4.2.3 Commercial demand for modular acoustic wall panels
- 4.2.4 Growth of DIY decor influencers on social media
- 4.2.5 Green-certified bio-based substrates
- 4.2.6 Post-pandemic commercial interior upgrades
- 4.3 Market Restraints
- 4.3.1 Volatility in PVC and petrochemical feedstock prices
- 4.3.2 High landfill cost of demolition waste
- 4.3.3 Fire-code compliance hurdles for composite panels
- 4.3.4 In-house digital printing eroding third-party demand
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 The Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Paper-Based
- 5.1.2 Fabric/Textile
- 5.1.3 Wood-Based
- 5.1.4 Vinyl
- 5.1.5 Other Materials
- 5.2 By Product Type
- 5.2.1 Wall Panel
- 5.2.2 Wallpaper
- 5.2.2.1 Vinyl Wallpaper
- 5.2.2.2 Non-woven Wallpaper
- 5.2.2.3 Paper-based Wallpaper
- 5.2.2.4 Fabric Wallpaper
- 5.2.2.5 Other Wallpaper Types
- 5.2.3 Tile
- 5.2.4 Metal Wall Covering
- 5.2.5 Other Product Types
- 5.3 By End-use Industry
- 5.3.1 Hospitality
- 5.3.2 Healthcare
- 5.3.3 Retail
- 5.3.4 Corporate Offices
- 5.3.5 Education
- 5.3.6 Domestic Housing
- 5.3.7 Industrial Facilities
- 5.3.8 Other End-use Industries
- 5.4 By Distribution Channel
- 5.4.1 Specialty Store
- 5.4.2 Franchise store
- 5.4.3 E-commerce
- 5.4.4 Other Distribution Channels
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 Australia
- 5.5.4.5 South Korea
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Kenya
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Saint-Gobain Adfors SA
- 6.4.2 Ahlstrom-Munksjo Oyj
- 6.4.3 AS Creation Tapeten AG
- 6.4.4 Asian Paints Limited
- 6.4.5 Benjamin Moore & Co.
- 6.4.6 Brewster Home Fashions LLC
- 6.4.7 York Wallcoverings, Inc.
- 6.4.8 J. Josephson Inc.
- 6.4.9 Walker Greenbank PLC
- 6.4.10 Grandeco Wallfashion Group NV
- 6.4.11 Graham & Brown Ltd.
- 6.4.12 F. Schumacher & Co. LLC
- 6.4.13 Rasch GmbH & Co. KG
- 6.4.14 Mohawk Industries, Inc.
- 6.4.15 Armstrong World Industries, Inc.
- 6.4.16 3M Company
- 6.4.17 Ceramiche Caesar S.p.A.
- 6.4.18 Shaw Industries Group, Inc.
- 6.4.19 Interface, Inc.
- 6.4.20 Kingfisher plc
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment