

|
시장보고서
상품코드
2121413
전기 인클로저 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Electrical Enclosures - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
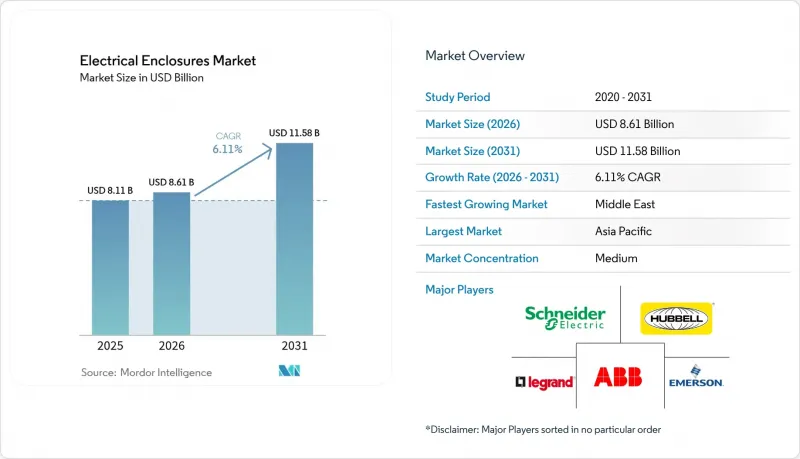
에 의하면, 전기 인클루저 시장 규모는 2025년 81억 1,000만 달러에서 2026년에는 86억 1,000만 달러로 확대되어 2031년까지 115억 8,000만 달러에 이를 것으로 예상되고 있어 2026-2031년 CAGR 6.11%를 기록할 전망입니다.
본 보고서는 재질(금속 및 비금속), 설치 형태(벽걸이형, 폴 설치형), 폼 팩터(소형(10L 미만), 컴팩트(10-50L), 기타), 최종 사용자 산업(석유 및 가스, 산업 제조·로봇 공학, 운송, 데이터센터·통신, 식음료, 제약, 기타) 및 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 전기 인클로저 시장 동향 및 인사이트
재생에너지 도입 확대
유틸리티 규모의 태양광 발전 및 해상 풍력 발전 프로젝트에서는 부식성 분무, 자외선 및 25년에 걸친 온도 변동을 견딜 수 있는 IP65 이상의 컴바이너 박스, 인버터 하우징 및 변압기 키오스크가 지정됩니다. 북해의 풍력 발전소에서는 스테인리스 스틸 316L이 주류를 이루는 반면, 아라비아 반도의 50℃에 달하는 혹서 조건에서는 패시브 고무가 적용된 분체 도장 알루미늄이 장비를 보호하고 있습니다. 태양광 발전 어레이와 함께 설치되는 배터리 에너지 저장 시스템에는 화재 시험 요건이 추가되어 있으며, 자금 조달 가능성을 확보하기 위해서는 UL 9540A 인증이 필수입니다. 재생에너지 발전 용량은 소수의 집중형 발전소가 아닌 수천 개의 소규모 설치 장소에 분산되어 도입되므로, 물류 담당자는 소형이고 다양한 인클로저 SKU의 적시 납품을 조정해야 하며, 기존의 수주 생산형 공장에는 모듈식 생산 도입이 시급합니다.
산업 자동화 및 인더스트리 4.0의 확대
독일이 2024년에 시행하는 20억 유로(22억 6,000만 달러) 규모의 지원 프로그램을 통해 자금을 조달받는 공장 디지털화 프로그램에서는 셀당 5-20대의 캐비닛이 필요한 센서 네트워크가 지원 대상에 포함됩니다. 중국과 멕시코의 자동차 생산 라인에서는 서보 드라이브로부터의 전자기 간섭을 방지하는 IP65 규격의 스테인리스 스틸 케이스 내에 협동 로봇용 컨트롤러가 설치되어 있습니다. 식품 가공 업체에서는 FDA 위생 기준을 준수하는 경사 지붕과 연속 경첩을 갖춘 설계가 선호됩니다. 한편, 제약 업계의 클린룸에서는 무균 구역을 침해하지 않고 육안 검사를 수행할 수 있도록 폴리카보네이트 재질의 창이 지정되어 있습니다. 운영 기술(OT)과 정보 기술(IT)의 통합이 진행됨에 따라, NEMA TS-2 및 IEC 62443을 준수하는 잠금 장치, 변조 감지 센서,침입 경보 장치가 데이터센터에서 공장 현장으로 이동하고 있으며, 이로 인해 전기 인클로저 시장은 사이버 보안의 중요한 이해관계자로서의 입지를 공고히 하고 있습니다.
원자재 가격 변동
2024년, 런던 금속 거래소(LME)의 알루미늄 선물 가격은 연중 10%의 변동폭을 보였으며, 8-12%의 순 스프레드로 사업을 영위하는 인클로저 제조업체의 이익률을 압박했습니다. 중국에서는 고로 가동 제한과 예상치 못한 철광석 공급 중단이 겹치면서 냉연강판 가격이 급등했고, 고정 가격 구매 주문에 묶여 있던 제조업체들은 계약 재협상을 해야 하거나 손실을 입는 상황에 처했습니다. 니켈 및 몰리브덴 가격에 연동되는 스테인리스 스틸 할증 요금이 15-20% 급등하면서, 해상 풍력 발전용 변전소 수주가 정체되었습니다. 현재 구매자들은 입찰서에 상품 지수 조항을 포함시키고 있으나, 이로 인한 행정적 부담이 전기 인클로저 업계의 조달 및 수요 예측을 복잡하게 만들고 있습니다.
부문별 분석
2025년, 전기 인클로저 시장 점유율의 63.78%를 금속 유닛이 차지했습니다. 이는 냉간 압연 강판의 가격 경쟁력과 전주 상단용 장비에서 알루미늄이 갖는 경량화 이점을 반영한 결과입니다. 비금속 캐비닛은 해상 풍력 발전,연안 변전소, 화학 플랜트 분야에서 ASTM B117 염수 분무 시험을 3,000시간 실시해도 녹이 발생하지 않는 유리섬유 강화 폴리에스터로의 전환이 진행됨에 따라, 2031년까지 연평균 6.57%의 성장이 예상됩니다. 폴리카보네이트 재질의 덮개는 기술자가 무균 경계를 훼손하지 않고 육안 확인을 수행해야 하는 클린룸에서 주류를 이루고 있습니다.
하이브리드 설계도 증가하고 있습니다. 폴리카보네이트 재질의 문과 알루미늄 재질의 백플레이트를 갖춘 강철 프레임은 비용, 접지, 내식성 간의 균형을 맞추고 있습니다. 스테인리스 스틸 316L은 NEMA 4X 및 IP66을 준수하고 산 및 염소에 의한 부식에도 견디기 때문에 여전히 위험 구역에서 주로 사용되고 있습니다. 한편, 에폭시 코팅이 적용된 탄소강은 실내 용도의 주력 제품으로 남아 있지만, 복합재료의 비용이 낮아지고 난연성 등급이 UL 94 V-0에 도달함에 따라 공장에서도 기존 금속 소재에 대한 투자를 재검토하는 움직임이 나타나고 있습니다. 이처럼 전기 인클로저 시장은 환경 및 수명 주기 경제성에 부합하는 복합 소재를 활용한 솔루션으로 전환되고 있습니다.
벽걸이형 박스는 2025년 출하 대수의 43.67%를 차지하며, 수직 공간을 효율적으로 활용할 수 있는 제어실 및 기계실의 기반이 되고 있습니다. 통신 사업자가 수만 기의 5G 스몰 셀을 추가함에 따라, 전주 설치형 설계는 2031년까지 6.88% 확대될 것으로 예측됩니다. 각 스몰 셀에는 정류기, 스플라이스 트레이, 백업 배터리용 IP65 규격의 인클로저가 필요합니다. 또한, 배전 사업자는 가공 송전선상의 자동 재폐로기 및 고장 표시기를 개조하여 지방 지역의 정전 시간을 40% 줄이고 있습니다.
패드 설치형 및 지하 설치형 유닛은 도시 경관 및 공공 안전 관련 규제를 준수하며, 변압기를 시야에서 가리는 동시에 토양의 습기 및 설치류의 침입을 방지합니다. 바닥 설치형 캐비닛은 케이블 설치 깊이가 중요한 중공업 분야의 모터 센터나 서버실에서 계속해서 사용되고 있습니다. 발전, 감지 및 연산 능력의 외부 이전으로 인해, 전기 인클로저 시장은 바람과 낙뢰를 견뎌야 하는 더 소형이고 내결함성이 높은 전신주 상단 쉘로 전환되고 있지만, 공조가 되는 실내 환경에서는 벽걸이형이 계속해서 사용될 것입니다.
지역별 분석
아시아태평양은 2025년 매출의 35.67%를 차지했습니다. 이는 중국의 5,200억 위안(730억 달러) 규모의 송전망 투자에 힘입은 것으로, 이를 통해 180만 대의 스마트 계량기와 1만 2,000대의 자동 피더 스위치가 도입되었으며, 이들 모두는 방진 하우징 내에 설치되어 있습니다. 인도에서는 3,000억 루피(36억 달러)의 개보수 자금을 통해 몬순철의 물보라에도 견딜 수 있는 변조 방지형 폴리카보네이트 재질의 계량기 박스가 도입되고 있습니다. 일본과 한국에서는 원자력 및 석탄 화력 발전소의 제어 장치를 규모 7의 지진을 견딜 수 있는 내진 사양 캐비닛으로 개조하고 있습니다. 동남아시아 싱가포르의 데이터센터 승인 용량은 2024년에 400 MW에 달할 것으로 예상되며, 이는 후면 도어식 열교환기가 장착된 랙 인클로저 약 1만 8,000대에 해당합니다. 이처럼 전기 인클로저 시장은 해당 지역의 에너지 및 디지털 인프라 확충 추세를 반영하고 있습니다.
중동은 2031년까지 7.13%의 성장이 예상됩니다. 사우디아라비아의 NEOM 프로젝트만 해도, 모래가 섞인 기온 50℃의 환경에 적합한 인버터 및 변압기용 인클로저 약 8만 대가 필요합니다. UAE의 바라카 발전소에서는 아크 방산 기능을 갖춘 스테인리스 스틸 캐비닛 12,000기가 지정되어 원자력 프로젝트에 대한 높은 기준이 설정되었습니다. 카타르의 노스필드 LNG 확장 프로젝트에서는 존 1용으로 방폭형 쉘 5,000기가 발주되었습니다. 페르시아만 전역에서 사막 환경에 대한 내성이 스테인리스 스틸 또는 분체 도장 알루미늄 제품에 대한 투자를 견인하고 있으며, 이는 전기 인클로저 시장의 평균 수주액을 끌어올리고 있습니다.
북미와 유럽을 합치면 전 세계 매출의 약 45%를 차지합니다. 미국의 ‘그리드 레질리언스(Grid Resilience)’ 프로그램은 산불 및 허리케인의 영향을 완화하기 위해 솔리드 스테이트 냉각 장치가 장착된 NEMA 3R 실외용 캐비닛에 자금을 지원하고 있습니다. 유럽의 ‘에너지 전환(Energiewende)’ 정책에 따라, 해상 풍력 발전을 위한 IP67 규격의 해저 정션 및 컨버터 하우징에 18억 유로(20억 3,000만 달러)가 투입되고 있습니다. 이러한 성숙한 지역에서는 교체 주기가 길어지고 있지만, 아크 플래시 및 사이버 보안에 관한 기준이 강화됨에 따라 개보수 공사는 꾸준한 속도로 진행되고 있습니다. 그 결과, 성장세는 둔화되고 있지만 사양의 복잡성으로 인해 전기 인클로저 시장의 기존 공급업체들은 건실한 이익률을 유지하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the electrical enclosures market size is expected to increase from USD 8.11 billion in 2025 to USD 8.61 billion in 2026 and reach USD 11.58 billion by 2031, growing at a CAGR of 6.11% over 2026-2031.
This report is Segmented by Material (Metallic, and Non-Metallic), Mounting Type (Wall-Mounted, Pole-Mounted), Form Factor (Small (Below 10 L), Compact (10-50 L), and More), End-User Industry (Oil and Gas, Industrial Manufacturing and Robotics, Transportation, Data Centres and Telecom, Food and Beverage, Pharmaceuticals, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Electrical Enclosures Market Trends and Insights
Accelerating Renewable-Energy Build-Out
Utility-scale solar and offshore wind projects specify IP65 or higher combiner boxes, inverter housings, and transformer kiosks that withstand corrosive spray, ultraviolet radiation, and temperature swings for 25 years. Stainless-steel 316L dominates North Sea farms, while powder-coated aluminum with passive louvers protects equipment in the Arabian Peninsula's 50 °C heat. Battery-energy-storage systems co-located with solar arrays add a fire-test layer, as UL 9540A certification becomes non-negotiable for bankability. Because renewable capacity is deployed across thousands of micro-sites rather than a few centralized stations, logisticians must orchestrate just-in-time deliveries of smaller, varied enclosure SKUs, pressuring traditional build-to-order plants to embrace modular production.
Industrial Automation and Industry 4.0 Expansion
Factory digitalization programs funded by Germany's EUR 2 billion (USD 2.26 billion) 2024 grant scheme subsidize sensor networks that each consume five to twenty cabinets per cell. Automotive lines in China and Mexico mount collaborative-robot controllers inside IP65 stainless enclosures that prevent electromagnetic interference from servo drives. Food processors prefer sloped-roof, continuous-hinge designs that comply with FDA sanitary codes, while pharmaceutical clean rooms specify polycarbonate windows to enable visual checks without breaching sterile zones. As operational technology integrates with information technology, NEMA TS-2 and IEC 62443 locks, tamper sensors, and intrusion alarms migrate from data centers to plant floors, cementing the electrical enclosures market as a cybersecurity stakeholder.
Raw-Material Price Volatility
London Metal Exchange aluminum contracts fluctuated 10% intra-year during 2024, eroding margins for enclosure makers that operate on 8-12% net spreads. Chinese cold-rolled steel soared when blast-furnace curbs coincided with unexpected iron-ore outages, forcing contract renegotiations or losses for fabricators tied to fixed-price purchase orders. Stainless-steel surcharges linked to nickel and molybdenum spiked 15-20%, stalling offshore wind substation awards. Buyers now write commodity-index clauses into tenders, but the administrative burden complicates procurement and forecasting in the electrical enclosures industry.
Other drivers and restraints analyzed in the detailed report include:
- Grid-Modernization and Substation Retrofits
- Stricter Global Safety and Ingress-Protection Codes
- Cyber-Attack Risk in Connected Enclosures
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Metallic units accounted for 63.78% of the electrical enclosures market share in 2025, reflecting cold-rolled steel's price advantage and aluminum's weight savings for pole-top gear. Non-metallic cabinets are expected to grow 6.57% annually through 2031 as offshore wind, coastal substations, and chemical plants shift toward fiberglass-reinforced polyester, which shows no rust after 3,000 hours of ASTM B117 salt spray testing. Polycarbonate lids dominate clean rooms where technicians need visual confirmation without breaking the sterile boundary.
Hybrid designs are multiplying: steel frames with polycarbonate doors or aluminum backplates balance cost, grounding, and corrosion resistance. Stainless-steel 316L still owns hazardous zones, meeting NEMA 4X and IP66 while resisting acid and chlorine attack. Meanwhile, carbon steel with epoxy coatings remains the indoor workhorse, but as composite costs fall and flame-retardant ratings reach UL 94 V-0, even factories are questioning legacy metal spend. The electrical enclosures market thus moves toward a mixed-material toolkit tailored to the environment and lifecycle economics.
Wall-mounted boxes delivered 43.67% of 2025 shipments, anchoring control rooms and machine cells where vertical real estate is cheap. Pole-mounted designs are forecast to expand 6.88% through 2031 as telecom operators add tens of thousands of 5G small cells, each requiring IP65-rated housings for rectifiers, splice trays, and backup batteries. Distribution utilities also retrofit auto-reclosers and fault indicators on overhead feeders, cutting rural outage minutes by 40%.
Pad-mounted and underground units serve urban aesthetics and public-safety rules, hiding transformers out of view while resisting soil moisture and rodent ingress. Floor-standing cabinets remain in heavy-industry motor centers and server rooms where cable depth matters. The outward shift in generation, sensing, and compute power is pushing the electrical enclosures market toward smaller, resilient pole-top shells that must withstand wind and lightning, while wall-mounts will persist in climatized interiors.
Complete Report Scope:
- By Material
- Metallic
- Non-Metallic
- By Mounting Type
- Wall-Mounted
- Floor-Mounted / Free-Standing
- Underground / Pad-Mounted
- Pole-Mounted
- By Form Factor
- Small (Below 10 L)
- Compact (10-50 L)
- Free-Size / Full-Size (Above 50 L)
- Modular / Configurable Systems
- By End-User Industry
- Energy and Power
- Oil and Gas
- Industrial Manufacturing and Robotics
- Metals and Mining
- Transportation
- Data Centres and Telecom
- Food and Beverage
- Pharmaceuticals
- By Geography
- North America
- United States
- Canada
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia Pacific generated 35.67% of 2025 revenue, buoyed by China's CNY 520 billion (USD 73 billion) grid spend that deployed 1.8 million smart meters and 12,000 automated feeder switches, all nestled inside dust-tight housings. India's INR 300 billion (USD 3.6 billion) revamp funds tamper-proof polycarbonate meter boxes resilient against monsoon splash. Japan and South Korea retrofit nuclear and coal controls into seismic-rated cabinets that sustain magnitude-7 shocks. Southeast Asian data-center approvals in Singapore reached 400 MW in 2024, translating to roughly 18,000 rack enclosures with rear-door heat exchangers. The electrical enclosures market thus tracks the region's dual energy and digital build-out.
The Middle East is projected to grow 7.13% through 2031. Saudi Arabia's NEOM program alone will need about 80,000 inverter and transformer housings suited for 50 °C air laden with sand. The UAE's Barakah plant specified 12,000 stainless cabinets with arc venting, setting a high bar for nuclear projects. Qatar's North Field LNG expansion ordered 5,000 explosion-proof shells for Zone 1. Across the Persian Gulf, desert resilience drives stainless or powder-coated aluminum spend, stretching average order values in the electrical enclosures market.
North America and Europe together hold roughly 45% of global sales. The U.S. Grid Resilience program finances NEMA 3R outdoor cabinets with solid-state coolers to mitigate the impacts of wildfires and hurricanes. Europe's Energiewende funnels EUR 1.8 billion (USD 2.03 billion) into IP67 subsea junction and converter housings for offshore wind. Replacement cycles lengthen in these mature zones, but stricter arc-flash and cybersecurity standards sustain a steady retrofit cadence. Consequently, while growth moderates, specification complexity keeps margins healthy for established vendors in the electrical enclosures market.
- Schneider Electric SE
- ABB Ltd.
- Eaton Corporation plc
- nVent Electric plc
- Rittal GmbH and Co. KG
- Emerson Electric Company
- Hubbell Incorporated
- Pentair plc
- Legrand SA
- Hammond Manufacturing Ltd.
- AZZ Inc.
- Scott Fetzer Company
- Allied Moulded Products Inc.
- Fibox Oy Ab
- Eldon Holding AB
- Siemens AG
- General Electric Company
- Saginaw Control and Engineering
- BOXCO Co. Ltd.
- Nitto Kogyo Corp.
- Socomec Group SA
- Bison ProFab Inc.
- Integra Enclosures Inc.
- Austin Electrical Enclosures
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerating Renewable-Energy Build-Out
- 4.2.2 Industrial Automation and Industry 4.0 Expansion
- 4.2.3 Grid-Modernization and Substation Retrofits
- 4.2.4 Stricter Global Safety and Ingress-Protection Codes
- 4.2.5 Outdoor 5G Small-Cell Rollout Needing IP-Rated Housings
- 4.2.6 Smart IoT-Enabled Enclosures for Predictive Maintenance
- 4.3 Market Restraints
- 4.3.1 Raw-Material Price Volatility (Steel, Aluminium)
- 4.3.2 Seal-Integrity and Thermal-Management Failures
- 4.3.3 Cyber-Attack Risk in Connected Enclosures
- 4.3.4 Skilled-Labour Shortage for Custom Fabrication
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitute Products
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material
- 5.1.1 Metallic
- 5.1.2 Non-Metallic
- 5.2 By Mounting Type
- 5.2.1 Wall-Mounted
- 5.2.2 Floor-Mounted / Free-Standing
- 5.2.3 Underground / Pad-Mounted
- 5.2.4 Pole-Mounted
- 5.3 By Form Factor
- 5.3.1 Small (Below 10 L)
- 5.3.2 Compact (10-50 L)
- 5.3.3 Free-Size / Full-Size (Above 50 L)
- 5.3.4 Modular / Configurable Systems
- 5.4 By End-User Industry
- 5.4.1 Energy and Power
- 5.4.2 Oil and Gas
- 5.4.3 Industrial Manufacturing and Robotics
- 5.4.4 Metals and Mining
- 5.4.5 Transportation
- 5.4.6 Data Centres and Telecom
- 5.4.7 Food and Beverage
- 5.4.8 Pharmaceuticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Schneider Electric SE
- 6.4.2 ABB Ltd.
- 6.4.3 Eaton Corporation plc
- 6.4.4 nVent Electric plc
- 6.4.5 Rittal GmbH and Co. KG
- 6.4.6 Emerson Electric Company
- 6.4.7 Hubbell Incorporated
- 6.4.8 Pentair plc
- 6.4.9 Legrand SA
- 6.4.10 Hammond Manufacturing Ltd.
- 6.4.11 AZZ Inc.
- 6.4.12 Scott Fetzer Company
- 6.4.13 Allied Moulded Products Inc.
- 6.4.14 Fibox Oy Ab
- 6.4.15 Eldon Holding AB
- 6.4.16 Siemens AG
- 6.4.17 General Electric Company
- 6.4.18 Saginaw Control and Engineering
- 6.4.19 BOXCO Co. Ltd.
- 6.4.20 Nitto Kogyo Corp.
- 6.4.21 Socomec Group SA
- 6.4.22 Bison ProFab Inc.
- 6.4.23 Integra Enclosures Inc.
- 6.4.24 Austin Electrical Enclosures
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


