|
시장보고서
상품코드
2121418
유럽의 바이오플라스틱 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Bioplastics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
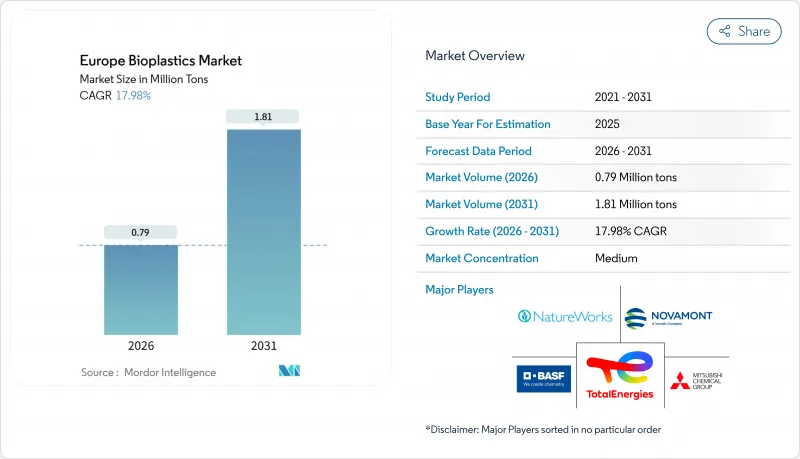
에 의하면, 유럽의 바이오플라스틱 시장 규모는 2026년에 79만 톤으로 추정되며, 예측 기간(2026-2031년)에 CAGR 17.98%로 성장을 지속하여 2031년까지 181만 톤에 이를 전망입니다.
본 보고서는 유형(바이오 생분해성 소재 및 바이오 비생분해성 소재), 원료(사탕수수/사탕무,옥수수 등), 가공 기술(압출 성형, 사출 성형 등), 용도(연포장, 경질 포장, 자동차 등), 지역(독일, 영국, 이탈리아 등)별로 분류되어 있습니다. 시장 예측은 수량(톤) 단위로 제시되어 있습니다.
유럽의 바이오플라스틱 시장 동향 및 인사이트
EU 일회용 플라스틱 지침이 퇴비화 가능한 제품의 보급을 가속화
2024년 7월에 시행된 이 지침은 폴리스티렌으로 만든 식품 용기, 컵, 수저를 금지하고, EN 13432를 준수하는 제품으로의 즉각적인 전환을 의무화하고 있습니다. 프랑스는 AGEC법을 통해 이 규정을 확대하여, 2025년부터는 푸드서비스용 포장재로 퇴비화 가능하거나 재사용 가능한 제품 사용을 의무화할 예정이므로, 패스트푸드점에서는 현재 산업 시설에서 90일 이내에 분해되는 PBAT와 전분 혼합 소재를 지정하고 있습니다. 이탈리아의 360곳 인증 퇴비화 시설은 음식물 쓰레기와 바이오플라스틱 포장을 동시에 수거하는 원활한 순환 시스템을 구축하고 있으며, 독일의 지자체도 민관 협력을 통해 이 모델을 모방하고 있습니다. 전분 수지와 PBAT 공중합체가 전환의 주류가 된 이유는 그 용융 유동 지수가 폴리스티렌과 일치하기 때문에 가공 업체가 기존의 열성형 라인을 계속 사용할 수 있기 때문입니다. 동유럽은 뒤처져 있어 지자체 수거율이 28%에 그치고 있기 때문에 각 브랜드는 서유럽용으로는 이중 규격의 퇴비화 가능한 포장재를, 동유럽용으로는 재활용 가능한 바이오 PE를 사용하고 있습니다.
포장 및 섬유 분야에서 브랜드 소유자의 지속가능성 노력
소비재 업계의 주요 기업들은 조달 계약에 바이오 소재 함유율에 관한 조항을 포함하고 있으며, 비용 프리미엄도 계약서에 명시되게 되었습니다. 다논은 2025년에 4만 5,000톤의 바이오 PET를 확보하기 위해 현물 가격의 PET보다 1,200만 유로를 추가로 지불했다고 밝혔습니다. 의류 업계에서는 H&M과 인디텍스가 나일론 6,6에 비해 ‘크래들-투-게이트’ 단계의 탄소 배출량을 30% 감축하는 PLA 섬유의 시범 도입을 추진하고 있는 반면,프록터 앤 갬블은 2025년 초, 식기 세제 ‘페어리’용으로 바이오 PE 병을 출시했습니다. 이러한 장기 계약은 수요를 안정시키고, 과거 대출 기관으로부터 위험도가 높다고 평가받았던 생산 능력 확장을 정당화하는 역할을 합니다. 그 결과, 유럽의 바이오플라스틱 시장은 지속적인 가격 지지 효과를 받고 있습니다.
산업용 퇴비화 처리 능력 부족
EU 지역 내 지자체 중 인증을 받은 시설을 운영하는 곳은 불과 42%에 불과하며, 해당 플랜트들은 이미 가동률이 78%에 달하고 있어 2028년까지 예상되는 34만 톤의 퇴비화 가능 폐기물 급증에 대응할 수 있는 잉여 처리 능력은 거의 남아 있지 않습니다. 마드리드의 유일한 퇴비화 시설은 시내 처리량을 모두 처리할 수 없어, 초과분은 매립지로 보내지지만, 그곳의 혐기성 환경에서는 분해가 정체되고 맙니다. 독일에서는 인증 취득에 ‘58℃·10일간’이라는 기준이 의무화되어 있어, 이 기준을 충족하지 못하는 소규모 지방 시설에서는 잔류 필름을 둘러싼 분쟁이 발생하고 있습니다. 프랑스는 신규 시설에 3억 유로를 책정했으나, 허가 절차 및 건물 건설은 2028년까지 완료되지 않을 전망입니다.
부문 분석
2025년 시점에서 바이오 생분해성 플라스틱은 유럽의 바이오플라스틱 시장의 59.81%를 차지하고 있으며, 2031년까지 연평균 성장률(CAGR) 22.59%를 기록할 전망입니다. 전분 혼합물은 PLA보다 15% 저렴한 비용으로, 완충재나 쇼핑백에 사용되고 있습니다. PLA는 투명성이 요구되는 경질 클램쉘 용기나 3D 프린팅 분야에서 프리미엄 시장 점유율을 차지하고 있습니다. PHA 시장 점유율은 현재 3% 미만에 그치고 있지만, 그리스에서 폐유를 원료로 하는 새로운 생산 시설이 가동됨에 따라 2029년까지 PBAT와 동등한 경제성을 실현할 수 있을 것으로 전망됩니다. PBAT, PBS, PCL은 유연성이 요구되는 용도에서 여전히 중요하며, EN 13432 규격을 충족하기 위해 전분과 혼합되어 사용됩니다.
2025년에도 바이오 유래의 비생분해성 소재는 상당한 시장 점유율을 차지하고 있었습니다. 바이오 PET는 코카콜라 등의 음료 브랜드로부터 지지를 받고 있으며, 해당 기업은 2025년에 바이오 함유율 30%인 병이 전체의 22%를 차지했다고 보고했습니다. 바이오 PE는 가정용 케어 브랜드가 생산 라인을 변경하지 않고도 소재를 전환할 수 있게 해 주며, 검증 주기가 긴 자동차 연료 탱크나 세제 병 분야에서 이점을 제공합니다. 아르케마(Arkema)사의 피마자유 유래 PA11은 40%의 가격 프리미엄이 있음에도 불구하고, 고마모 부품 시장에서 입지를 유지하고 있습니다.
2025년에는 사탕수수와 사탕무가 원료의 44.77%를 공급했으나, 셀룰로오스계 및 목재 폐기물은 연평균 성장률(CAGR) 22.42%로 이를 능가할 전망입니다. 2025년 옥수수 가격은 톤당 평균 245유로이며, 바이오에탄올 수요로 인해 상승 추세가 지속되고 있습니다. 카사바와 감자의 재배 면적 확대는 여전히 제한적입니다. 대조적으로, 제재소 잔여물을 효소 가수분해하여 당을 생산하는 비용은 톤당 180-210유로로, 옥수수 유래 포도당보다 15% 저렴합니다. CO₂와 수소를 이용한 가스 발효 기술은 에보닉(Evonik)사의 파일럿 사업 지원과 2,500만 유로 규모의 혁신 기금으로부터 보조금을 받고 있으며, 2027년에는 5,000톤 생산을 목표로 하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the Europe bioplastics market size is estimated at 0.79 million tons in 2026, and is expected to reach 1.81 million tons by 2031, at a CAGR of 17.98% during the forecast period (2026-2031).
This report is Segmented by Type (Bio-Based Biodegradables and Bio-Based Non-Biodegradables), Feedstock (Sugarcane/Beet, Corn, and More), Processing Technology (Extrusion, Injection Molding, and More), Application (Flexible Packaging, Rigid Packaging, Automotive, and More), and Geography (Germany, United Kingdom, Italy, and More). Market Forecasts are Provided in Terms of Volume (Tons).
Europe Bioplastics Market Trends and Insights
EU Single-Use Plastics Directive Accelerates Compostable Uptake
The directive that took effect in July 2024 prohibits polystyrene food containers, cups, and cutlery, forcing immediate substitution with EN 13432-compliant items. France extended this rule through the AGEC law and will require compostable or reusable food-service packaging in 2025, so quick-service outlets now specify PBAT-starch blends that degrade within 90 days in industrial facilities. Italy's 360 certified composters create a seamless loop for co-collecting food scraps and bioplastic packaging, a model that German municipalities replicate through public-private deals. Starch resins and PBAT copolymers dominate the switch because their melt-flow index matches polystyrene, allowing converters to keep legacy thermoforming lines. Eastern Europe lags, with only 28% municipal coverage, so brands use dual-spec compostable packaging for the West and recyclable bio-PE for the East.
Brand-Owner Sustainability Commitments in Packaging and Textiles
Consumer-goods leaders embed bio-content clauses in procurement, and cost premiums are now written into contracts. Danone disclosed that it paid EUR 12 million above spot PET to secure 45,000 tons of bio-PET in 2025. In apparel, H&M and Inditex pilot PLA fibers that cut cradle-to-gate carbon by 30% versus nylon 6,6, while Procter & Gamble released bio-PE bottles for Fairy dish soap in early 2025. These long agreements stabilize demand and justify capacity expansions that lenders once viewed as risky. As a result, the Europe bioplastics market receives durable price support.
Limited Industrial-Composting Capacity
Only 42% of municipalities across the bloc run certified facilities, and those plants already operate at 78% utilization, leaving little spare capacity for the expected 340,000-ton surge in compostable waste by 2028. Madrid's single composter cannot handle city volumes, so overflow swings to landfill, where anaerobic settings stall degradation. Germany enforces a 58 °C, 10-day rule for certification, a hurdle that small rural sites miss, sparking disputes over residual films. Though France earmarked EUR 300 million for new sites, permits, and buildings will not finish until 2028.
Other drivers and restraints analyzed in the detailed report include:
- Corporate Net-Zero Targets Favor Bio-Content Substitution
- Lignocellulosic Sugar Integration by Pulp Mills
- High EU Energy Prices Inflate Extrusion and Conversion Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Bio-based biodegradables held 59.81% of the Europe bioplastics market in 2025 and will post a 22.59% CAGR to 2031. Starch blends serve loose-fill and shopping bags at a cost of 15% below PLA. PLA commands the premium slice in rigid clamshells and 3D printing, where clarity matters. PHA stays below 3% share for now, yet new waste-oil capacity in Greece signals that economics can equal PBAT by 2029. PBAT, PBS, and PCL remain critical for flexibility, blended with starch to meet EN 13432.
Bio-based non-biodegradables also held a considerable market share in 2025. Bio-PET appeals to beverage brands such as Coca-Cola, which reported 22% of bottles with 30% bio-content in 2025. Bio-PE lets home-care brands shift without line changes, a gain in automotive fuel tanks and detergent bottles with long validation cycles. Arkema's PA11 from castor oil keeps a foothold in high-abrasion parts despite a 40% price premium.
Sugarcane/sugar beet supplied 44.77% of inputs in 2025, but cellulosic and wood waste will outpace at 22.42% CAGR. Corn prices averaged EUR 245 per ton in 2025 and continue upward due to bioethanol demand. Cassava and potato acreage expansion remains limited. By contrast, enzymatic hydrolysis of sawmill residue delivers sugars at EUR 180-210 per ton, 15% under corn glucose. Gas fermentation using CO2 and hydrogen has pilot backing from Evonik and a EUR 25 million Innovation Fund grant, targeting 5,000 tons in 2027.
Complete Report Scope:
- By Type
- Bio-based Biodegradables
- Starch-based
- Polylactic Acid (PLA)
- Polyhydroxyalkanoates (PHA)
- Polyesters (PBS, PBAT, PCL)
- Other Bio-based Biodegradables
- Bio-based Non-biodegradables
- Bio Polyethylene Terephthalate (PET)
- Bio Polyethylene
- Bio Polyamides
- Bio Polytrimethylene Terephthalate
- Other Bio-based Non-biodegradables
- Bio-based Biodegradables
- By Feedstock
- Sugarcane / Sugar Beet
- Corn
- Cassava and Potato
- Cellulosic and Wood Waste
- Others (Algae and Microbial Oil)
- By Processing Technology
- Extrusion
- Injection Molding
- Blow Molding
- 3D Printing
- Others (Thermoforming, etc.)
- By Application
- Flexible Packaging
- Rigid Packaging
- Automotive and Assembly Operations
- Agriculture and Horticulture
- Construction
- Textiles
- Electrical and Electronics
- Other Applications
- By Country
- Germany
- United Kingdom
- Italy
- France
- Netherlands
- Spain
- Nordic
- Rest of Europe
List of Companies Covered in this Report:
- Arkema
- BASF
- BIO ON SpA
- Biome Bioplastics
- BIOTEC Biologische Naturverpackungen GmbH & Co. KG.
- Eni S.p.A. (Novamont)
- Evonik Industries AG
- FKuR
- FUTERRO
- Green Dot Bioplastics Inc
- Innovia Films
- Lactips
- Minima
- Mitsubishi Chemical Group Corporation
- NatureWorks LLC
- Plantic
- Rodenburg Biopolymers
- RWDC Industries
- Sulapac Oy
- TORAY INDUSTRIES, INC.
- TotalEnergies (Total Corbion)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EU Single-Use Plastics Directive accelerates compostable uptake
- 4.2.2 Brand-owner sustainability commitments in packaging and textiles
- 4.2.3 Corporate net-zero targets favour bio-content substitution
- 4.2.4 Lignocellulosic sugar integration by EU pulp mills enables on-site PLA/PHA
- 4.2.5 CBAM cost on fossil polymer imports boosts EU bioplastics economics
- 4.3 Market Restraints
- 4.3.1 Limited industrial-composting capacity
- 4.3.2 High EU energy prices inflate extrusion and conversion costs
- 4.3.3 Feedstock competition from RED-III advanced-biofuel mandates
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Type
- 5.1.1 Bio-based Biodegradables
- 5.1.1.1 Starch-based
- 5.1.1.2 Polylactic Acid (PLA)
- 5.1.1.3 Polyhydroxyalkanoates (PHA)
- 5.1.1.4 Polyesters (PBS, PBAT, PCL)
- 5.1.1.5 Other Bio-based Biodegradables
- 5.1.2 Bio-based Non-biodegradables
- 5.1.2.1 Bio Polyethylene Terephthalate (PET)
- 5.1.2.2 Bio Polyethylene
- 5.1.2.3 Bio Polyamides
- 5.1.2.4 Bio Polytrimethylene Terephthalate
- 5.1.2.5 Other Bio-based Non-biodegradables
- 5.1.1 Bio-based Biodegradables
- 5.2 By Feedstock
- 5.2.1 Sugarcane / Sugar Beet
- 5.2.2 Corn
- 5.2.3 Cassava and Potato
- 5.2.4 Cellulosic and Wood Waste
- 5.2.5 Others (Algae and Microbial Oil)
- 5.3 By Processing Technology
- 5.3.1 Extrusion
- 5.3.2 Injection Molding
- 5.3.3 Blow Molding
- 5.3.4 3D Printing
- 5.3.5 Others (Thermoforming, etc.)
- 5.4 By Application
- 5.4.1 Flexible Packaging
- 5.4.2 Rigid Packaging
- 5.4.3 Automotive and Assembly Operations
- 5.4.4 Agriculture and Horticulture
- 5.4.5 Construction
- 5.4.6 Textiles
- 5.4.7 Electrical and Electronics
- 5.4.8 Other Applications
- 5.5 By Country
- 5.5.1 Germany
- 5.5.2 United Kingdom
- 5.5.3 Italy
- 5.5.4 France
- 5.5.5 Netherlands
- 5.5.6 Spain
- 5.5.7 Nordic
- 5.5.8 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, Recent Developments)}
- 6.4.1 Arkema
- 6.4.2 BASF
- 6.4.3 BIO ON SpA
- 6.4.4 Biome Bioplastics
- 6.4.5 BIOTEC Biologische Naturverpackungen GmbH & Co. KG.
- 6.4.6 Eni S.p.A. (Novamont)
- 6.4.7 Evonik Industries AG
- 6.4.8 FKuR
- 6.4.9 FUTERRO
- 6.4.10 Green Dot Bioplastics Inc
- 6.4.11 Innovia Films
- 6.4.12 Lactips
- 6.4.13 Minima
- 6.4.14 Mitsubishi Chemical Group Corporation
- 6.4.15 NatureWorks LLC
- 6.4.16 Plantic
- 6.4.17 Rodenburg Biopolymers
- 6.4.18 RWDC Industries
- 6.4.19 Sulapac Oy
- 6.4.20 TORAY INDUSTRIES, INC.
- 6.4.21 TotalEnergies (Total Corbion)
7 Market Opportunities and Future Outlook
- 7.1 EU Circular Economy and Green Deal Strategies
- 7.2 White-space and Unmet-need Assessment