|
시장보고서
상품코드
2121511
부식 방지 코팅 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Anti-Corrosion Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
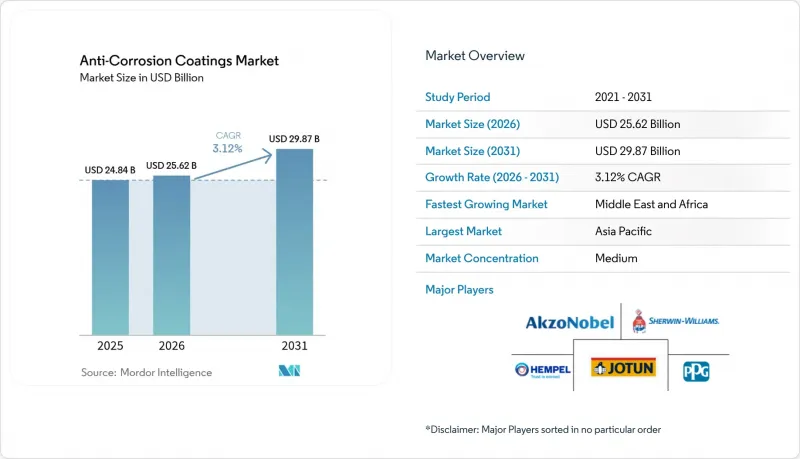
부식 방지 코팅 시장 규모는 2025년에 248억 4,000만 달러로 평가되며, 2026년 256억 2,000만 달러에서 2031년까지 298억 7,000만 달러에 달할 것으로 예측되며, 예측 기간(2026-2031년) 동안 CAGR은 3.12%가 될 전망입니다.
본 보고서는 수지 유형(에폭시, 폴리에스테르, 폴리우레탄 등), 기술(수성, 용제형, 분체, UV 경화형), 최종사용자 산업(석유·가스,선박, 전력, 인프라, 산업, 항공우주·방위 등) 및 지역(아시아태평양, 북미, 유럽, 남미, 중동 및 아프리카)별로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
세계 부식 방지 코팅 시장의 동향 및 인사이트
미국, 유럽연합 및 일본의 인프라 갱신 슈퍼사이클
이 세 개의 성숙한 경제권에서 교량, 터널, 철도 자산은 일제히 노후화가 진행되고 있습니다. 미국은 도로 및 교량에 1,100억 달러를 배정하고 있으며, 각 주 교통국은 현재 철골 구조물에 대해 SSPC-Paint 36을 준수하는 3층 도장 에폭시·폴리우레탄계 도료 시스템의 채택을 의무화하고 있습니다. 일본 국토교통성은 2025년, 국내 73만 기의 교량 중 63%가 준공 50년을 넘었다고 보고하며, 2030년까지 부식 방지를 위해 5조 3,000억 엔(350억 달러)을 투자할 방침을 밝혔습니다. 한편, 독일만 해도 28억 유로 규모의 계획에 따라 4,000개의 아우토반 교량 개보수 작업이 진행되고 있습니다. 강구조물의 재도장 주기는 15-25년이며, 규격 제정 기관이 ISO 12944-C5-M 준수를 의무화하고 있기 때문에 이처럼 일제히 투입되는 예산은 부식 방지 코팅 시장에 견고한 버팀목이 되고 있습니다.
해상 풍력발전소의 도장 수요 급증
2025년 말까지 해상 풍력발전 설비 용량은 75GW에 달할 전망이며, 모든 모노파일, 트랜지션 피스, 해상 변전소에는 아연·에폭시·폴리실록산 기반의 다층 보호가 요구되고 있습니다. 오르스테드(Orsted)사의 2.9GW 규모 ‘혼시 3(Hornsea 3)’ 프로젝트에서는 10,000시간의 염수 분무 시험을 거쳐 승인된, 수명 25년의 도료가 필요합니다. 미국에서는 2024년에 경매에 부쳐진 대서양의 6개 임대 구역에서 2032년까지 약 18만 톤의 코팅이 필요할 것으로 전망됩니다. 해상 풍력발전 설비 제조와 관련된 DNV 인증을 취득한 전 세계 조선소는 20곳 미만이므로, 코팅 사양은 엄격하게 관리되고 있으며, 부식 방지 코팅 시장은 30-40%의 가격 프리미엄이 붙는 고품질 화학 조성의 제품으로 전환되고 있습니다.
세계 VOC/이소시아네이트 노출 상한선 강화
지침 2020/1149에 따라 0.1%를 초과하는 디이소시아네이트를 취급하는 유럽의 모든 근로자는 인증 교육 이수가 의무화되어 있으며, 이로 인해 시설당 5,000-1만 5,000유로의 규정 준수 비용이 발생합니다. 유럽화학제품청(ECHA)은 2029년까지 6µg NCO/m³이라는 기준치를 시행할 예정이며, 이는 기존 기준보다 약 10배 더 엄격한 수준입니다. 미국도 이에 발맞춰 OSHA(직업안전보건청)가 5µg NCO/m³의 제한치를 제안하고 있습니다. 이러한 규제는 용제형 폴리우레탄 제품 라인에 타격을 주는 한편, 구매자들을 수성 분산액으로 유도하는 요인이 되고 있지만, 4-6시간의 건조 시간은 제조 현장의 생산성을 저해하는 요인이 되고 있습니다.
부문 분석
2025년, 에폭시계 시스템은 부식 방지 코팅 시장의 38.98%를 차지했으며, 강재에 대한 밀착성과 음극 방식과의 적합성이 두드러집니다. 정유소, 파이프라인 사업자 및 해상 플랫폼이 탱크 라이닝과 스플래시 존 배리어를 갱신함에 따라, 에폭시계 부식 방지 코팅 시장의 규모는 꾸준히 확대될 것으로 예측됩니다. 폴리우레탄 수요는 육상 풍력발전 타워의 타워 본체, 태양광발전 프레임 및 파사드용 강재에서 자외선 안정성과 색상 유지력이 요구됨에 따라 연평균 성장률(CAGR) 3.81%라는 비교적 빠른 속도로 증가하고 있습니다.
알키드 수지 및 폴리에스테르 수지는 비용 중심의 틈새 시장에서 여전히 입지를 유지하고 있지만, 그 성장률은 전체 부식 방지 코팅 시장보다 낮습니다. 에폭시계 프라이머와 폴리우레탄계 탑코트를 결합한 하이브리드 시스템은 카테고리 간의 경계를 모호하게 만들고 있으며, 가속 풍화 시험을 통해 가교 호환성을 입증한 공급업체에 이익을 가져다주고 있습니다. 2024년부터 2025년까지 액소노벨이 취득한 14건의 특허에서 주목받고 있는 자가 복구형 및 부식 감지형 안료는 유지보수 주기를 25년 이상으로 연장할 수 있는 차세대 화학 기술을 시사하며, 방식 도료 업계에서 프리미엄 위상을 강화하는 요소입니다.
지역별 분석
2025년, 아시아태평양은 부식 방지 도료 시장 매출의 46.72%를 차지했습니다. 이는 중국 내 일일 총 생산량 240만 배럴 규모의 8개 신규 정유소와 인도의 연안 파이프라인 개보수 사업에 힘입은 결과입니다. 동남아시아의 사업자들이 18,000km에 달하는 해저 파이프라인을 확장하고, 일본 당국이 교량의 수명 연장을 위한 개보수에 5조 3,000억 엔을 투입함에 따라, 해당 지역의 방식 도료 시장 규모는 더욱 확대되고 있습니다.
북미에서는 1,100억 달러 규모의 미국 교량 예산이 SSPC 인증 3층 도장 시스템에 대한 수요를 견인하고 있는 반면, 캐나다의 오일샌드 사업으로 인해 고온용 에폭시-페놀계 도료의 수주가 견조한 추세를 보이고 있습니다. 유럽의 20% 시장 점유율은 북해 해상 풍력발전 프로젝트와 아우토반 교량 교체 사업이 뒷받침하고 있으며, 이들 모두 ISO 12944-C5-M 규격의 도료를 지정하고 있어 가격 상승을 부추기고 있습니다.
중동 및 아프리카는 연평균 성장률(CAGR) 3.41%로 가장 빠르게 성장하고 있는 지역입니다. 사우디 아람코의 120억 달러 규모 마르잔 및 베리 확장 프로젝트, ADNOC의 사워 가스 메가 프로젝트, 그리고 걸프 지역의 해수 담수화 플랜트가 맞물려, 황화수소 및 염수에 대한 노출 기준을 충족할 수 있는 공급업체들에게 안정적인 수주량을 확보해 주고 있습니다. 라틴아메리카 및 남아시아는 이에 비해 뒤처져 있지만, 페트로브라스의 프레솔트층 관련 유지보수 및 인도의 항만 건설에 따른 간헐적인 수요 급증이 예상됩니다. 이러한 다양한 상황으로 인해 부식 방지 도료 시장은 지리적으로 분산된 상태를 유지하고 있으며, 단일 수요 거점에 대한 과도한 의존을 억제하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 소개
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSM 26.09.07According to Mordor Intelligence, the anti-Corrosion coatings market size was valued at USD 24.84 billion in 2025 and is estimated to grow from USD 25.62 billion in 2026 to reach USD 29.87 billion by 2031, at a CAGR of 3.12% during the forecast period (2026-2031).
This report is Segmented by Resin Type (Epoxy, Polyester, Polyurethane, and More), Technology (Water-Borne, Solvent-Borne, Powder, and UV-Cured), End-User Industry (Oil and Gas, Marine, Power, Infrastructure, Industrial, Aerospace and Defense, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Anti-Corrosion Coatings Market Trends and Insights
Infrastructure-Renewal Super-Cycle in US, European Union and Japan
Bridge, tunnel, and rail assets are aging in lockstep across three mature economies. The United States has earmarked USD 110 billion for roads and bridges; state transportation agencies now require three-coat epoxy-polyurethane systems that meet SSPC-Paint 36 for steel structures. Japan's Ministry of Land, Infrastructure, Transport and Tourism reported in 2025 that 63% of the nation's 730,000 bridges exceed 50 years of age, unlocking JPY 5.3 trillion (USD 35 billion) for corrosion remediation through 2030. Meanwhile, Germany alone is replacing 4,000 Autobahn bridges under an EUR 2.8 billion initiative. These synchronized budgets create a durable floor for the Anti-Corrosion Coatings market, as steel recoating cycles last 15-25 years and specification bodies insist on ISO 12944-C5-M compliance.
Offshore Wind-Farm Coating Boom
Installed offshore-wind capacity reached 75 GW by late 2025, and every monopile, transition piece, and offshore substation demands multi-layer zinc-epoxy-polysiloxane protection. Orsted's 2.9 GW Hornsea Three project requires 25-year service-life coatings approved after 10,000-hour salt-spray testing. On the US side, six Atlantic lease areas auctioned in 2024 will need roughly 180,000 tons of coatings through 2032. Because fewer than 20 global yards hold DNV certification for offshore-wind fabrication, coating specifications are tightly controlled, pushing the Anti-Corrosion Coatings market toward premium chemistries that command 30-40% price premiums.
Global VOC / Isocyanate Exposure Caps Tightening
Directive 2020/1149 compels every European worker handling >0.1% diisocyanate to complete certified training, adding EUR 5,000-15,000 per facility in compliance costs. The European Chemicals Agency will enforce a 6 µg NCO/m3 limit by 2029, roughly 10 times stricter than prior levels. The United States is following with a proposed OSHA 5 µg NCO/m3 limit. These caps penalize solvent polyurethane lines and nudge buyers toward water-borne dispersions, though 4-6 hour dry times hamper throughput in fabrication shops.
Other drivers and restraints analyzed in the detailed report include:
- Offshore Pipeline Life-Extension Spend in Asia-Pacific
- IMO CII Rules Driving More Frequent Hull Recoating
- Epoxy Raw-Material Price Spikes (Bis-A, ECH)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Epoxy systems represented 38.98% of the Anti-Corrosion Coatings market share in 2025, underscoring the chemistry's adhesion to steel and compatibility with cathodic-protection schemes. The Anti-Corrosion Coatings market size attributable to epoxy is projected to climb at a steady clip as refiners, pipeline operators, and offshore platforms renew tank linings and splash-zone barriers. Polyurethane demand is rising faster, expanding 3.81% CAGR, because onshore wind towers, solar frames, and facade steel require UV stability and color retention.
Alkyd and polyester resins persist in cost-sensitive niches, yet their growth trails the overall Anti-Corrosion Coatings market. Hybrid epoxy-primer plus polyurethane topcoat systems are blurring category lines, rewarding suppliers that validate cross-link compatibility through accelerated weathering. Self-healing and corrosion-sensing pigments, highlighted by 14 Akzo Nobel patents in 2024-25, point to next-generation chemistries that could elongate maintenance intervals beyond 25 years, strengthening premium positions within the Anti-Corrosion Coatings industry.
Complete Report Scope:
- By Resin Type
- Epoxy
- Alkyds
- Polyester
- Polyurethane
- Vinyl Ester
- Other Resin Types
- By Technology
- Water-borne
- Solvent-borne
- Powder
- UV-cured
- By End-user Industry
- Oil and Gas
- Marine
- Power
- Infrastructure
- Industrial
- Aerospace and Defense
- Transportation
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Nigeria
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 46.72% of the Anti-Corrosion Coatings market revenue in 2025, backed by China's eight new refineries totaling 2.4 million b/d and India's coastal pipeline rehabilitation initiatives. The Anti-Corrosion Coatings market size in the region swells further as Southeast Asian operators extend 18,000 km of subsea lines and Japanese authorities funnel JPY 5.3 trillion into bridge lifeline upgrades.
In North America, the USD 110 billion US bridge budget is channeling demand for SSPC-certified three-coat systems, while Canada's oil sands keep high-temperature epoxy-phenolic orders consistent. Europe's 20% share rides on North Sea offshore wind and Autobahn bridge replacements, both specifying ISO 12944-C5-M coatings that drive premium pricing.
The Middle East & Africa is the fastest rising geography at 3.41% CAGR. Saudi Aramco's USD 12 billion Marjan and Berri expansions, ADNOC's sour-gas megaproject, and Gulf desalination plants collectively ensure steady throughput for suppliers able to meet hydrogen-sulfide and brine-exposure criteria. Latin America and South Asia trail but offer episodic surges tied to Petrobras pre-salt maintenance and Indian port construction. This mosaic keeps the Anti-Corrosion Coatings market geographically diversified, limiting overreliance on a single demand hub.
- Akzo Nobel N.V.
- Axalta Coating Systems, LLC
- BASF
- Beckers Group
- Berger Paints India
- Carboline
- Chugoku Marine Paints, Ltd.
- H.B. Fuller Company
- Hempel A/S
- Jotun
- Kansai Paint Co., Ltd.
- Nippon Paint Holdings Co., Ltd.
- PPG Industries, Inc.
- RPM International Inc.
- Sika AG
- Teknos Group
- The Sherwin-Williams Company
- Tikkurila
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure-renewal super-cycle in US, European Union and Japan
- 4.2.2 Offshore wind-farm coating boom
- 4.2.3 Offshore pipeline life-extension spend in Asia-Pacific
- 4.2.4 IMO CII rules driving more frequent hull recoating
- 4.2.5 CUI-driven specification upgrades at LNG terminals
- 4.3 Market Restraints
- 4.3.1 Global VOC / isocyanate exposure caps tightening
- 4.3.2 Epoxy raw-material price spikes (Bis-A, ECH)
- 4.3.3 Deferred CAPEX in oil-&-gas downturn cycles
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Resin Type
- 5.1.1 Epoxy
- 5.1.2 Alkyds
- 5.1.3 Polyester
- 5.1.4 Polyurethane
- 5.1.5 Vinyl Ester
- 5.1.6 Other Resin Types
- 5.2 By Technology
- 5.2.1 Water-borne
- 5.2.2 Solvent-borne
- 5.2.3 Powder
- 5.2.4 UV-cured
- 5.3 By End-user Industry
- 5.3.1 Oil and Gas
- 5.3.2 Marine
- 5.3.3 Power
- 5.3.4 Infrastructure
- 5.3.5 Industrial
- 5.3.6 Aerospace and Defense
- 5.3.7 Transportation
- 5.3.8 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Spain
- 5.4.3.5 Italy
- 5.4.3.6 NORDIC Countries
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 United Arab Emirates
- 5.4.5.3 South Africa
- 5.4.5.4 Nigeria
- 5.4.5.5 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Axalta Coating Systems, LLC
- 6.4.3 BASF
- 6.4.4 Beckers Group
- 6.4.5 Berger Paints India
- 6.4.6 Carboline
- 6.4.7 Chugoku Marine Paints, Ltd.
- 6.4.8 H.B. Fuller Company
- 6.4.9 Hempel A/S
- 6.4.10 Jotun
- 6.4.11 Kansai Paint Co., Ltd.
- 6.4.12 Nippon Paint Holdings Co., Ltd.
- 6.4.13 PPG Industries, Inc.
- 6.4.14 RPM International Inc.
- 6.4.15 Sika AG
- 6.4.16 Teknos Group
- 6.4.17 The Sherwin-Williams Company
- 6.4.18 Tikkurila
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment