

|
시장보고서
상품코드
2121634
치과용 소모품 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Global Dental Consumables - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
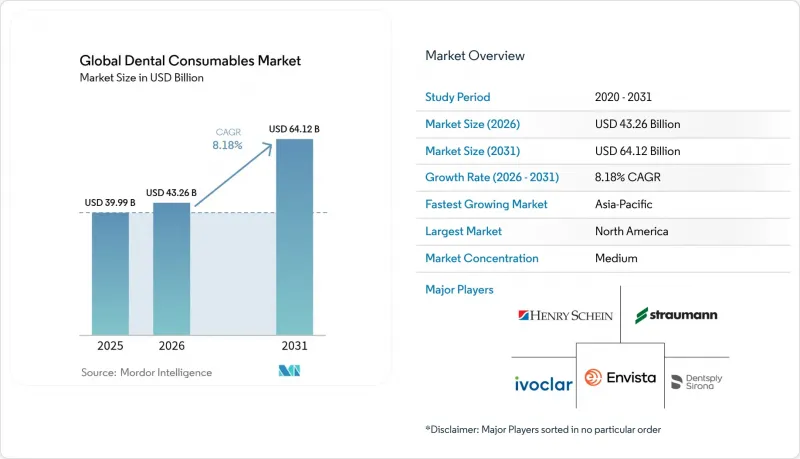
에 의하면, 치과용 소모품 시장 규모는 2025년에 399억 9,000만 달러로 평가되었고, 2026년 432억 6,000만 달러에서 2031년까지 641억 2,000만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 8.18%를 기록할 전망입니다.
본 보고서는 제품 유형(얼라이너 및 교정 장치, 마취제 등), 치료법(수복 치료, 보철 치료 등), 판매 채널(오프라인(B2B 및 B2C) 및 온라인), 최종 사용자(치과, 치과 병원 등), 지역(북미, 유럽, 아시아태평양 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계 치과용 소모품 시장 동향 및 인사이트
당일 CAD/CAM 보철물에 대한 수요 증가
미국 치과 진료소의 절반 이상이 이미 구강 내 스캐너를 도입하고 있으며, 이로 인해 치료 주기가 단축되고 고급 수복 재료의 적용 범위가 확대되고 있습니다. 체어사이드 밀링과 클라우드 설계 서비스를 결합함으로써 치과 기공소의 간접비가 절감되고 수익성이 향상됩니다. AI가 탑재된 설계 모듈을 통해 복잡한 마진 및 접촉면 조정이 자동화되어 체어타임이 더욱 단축됩니다. 2024년에는 도입률이 18% 가속화되고, 2025년에는 스캐너와의 통합으로 이미지 정밀도가 향상될 전망이므로, 이에 따라 재료 처리량도 증가할 것으로 예측됩니다. 스캐너, 밀링 장비 및 검증된 재료 블록을 세트로 제공할 수 있는 공급업체들은 DSO(치과 서비스 조직)와의 장기 계약을 확보해 나가고 있습니다.
고령화 진행에 따라 보철 치료 증가
65세 이상 성인은 가장 빠르게 증가하고 있는 환자층입니다. 일본에서는 이미 임플란트 지지형 오버덴처에 대한 전문적인 보험 환급 경로가 마련되어 있으며, EU의 ‘실버 이코노미’ 프로그램에서는 고령자 치과 의료에 자금이 배정되고 있습니다. 디지털 의치 워크플로는 내원 부담을 줄여주어, 이동에 제약이 있는 고령층의 수용도를 높이고 있습니다. 재료 공급업체들은 구강 건조증이 생기기 쉬운 환자를 위해 경량 폴리머 베이스나 내충격성이 높은 아크릴 수지를 상품화하고 있습니다.
심미 치과에 대한 보험 환급은 제한적
심미용 베니어, 미백, 잇몸 성형술은 여전히 주로 본인 부담으로 이루어지고 있습니다. 메디케어는 2025년에 특정 의학적 근거에 기반한 치과 치료에 대한 적용 범위를 확대할 예정이지만, 선택적 심미 치과 치료에 대한 급여는 여전히 제한적입니다. 이로 인해 시장은 양극화되어 고급 부문은 유지되는 반면, 총 판매량은 제한되고 있습니다. 각 제조업체는 가격과 광택 유지력의 균형을 고려한 단계별 복합 레진 제품 라인을 제공함으로써 이러한 상황에 대응하고 있습니다.
부문 분석
2025년 기준, 치과 임플란트는 치과용 소모품 시장 점유율의 18.10%를 차지했습니다. 성공률이 높은 생체활성 코팅과 디지털 수술 계획 덕분에 적응증이 연한 뼈 상태까지 확대되고 있습니다. 개인보호구(PPE) 부문의 치과용 소모품 시장 규모는 2031년까지 연평균 성장률(CAGR) 9.74%로 확대될 것으로 예상되며, 특히 아시아태평양의 고령층에 의해 주도되고 있습니다. 이 부문의 급속한 성장은 ASTM 인증을 받은 호흡용 보호구와 오토클레이브 처리 가능한 아이실드 착용을 의무화하는 감염 관리 프로토콜에 의해 더욱 가속화되고 있습니다.
보철 하위 부문은 지르코니아 및 리튬 디실리케이트 크라운을 1시간 이내에 제작하는 CAD/CAM 워크플로우의 혜택을 받고 있습니다. 범용 본딩제는 여러 에칭 기법에 대응함으로써 재고 관리를 효율화하고 있습니다. 인산칼슘 과립 등의 재생 재료는 치조골 증대술의 보급에 따라 수요가 확대되고 있습니다. 한편, 봉합사나 버는 성숙한 시장이지만, 시술자의 피로를 줄여주는 인체공학에 기반한 핸들 재설계로 인해 소폭의 성장이 예상됩니다.
2025년에는 가이드 수술 및 즉시 하중을 통해 풀 아치 수복이 체어사이드에서 이루어지게 됨에 따라, 보철 시술은 치과용 소모품 시장의 27.35%를 차지할 전망입니다. 클리어 얼라이너에 힘입은 교정치과는 9.42%라는 가장 높은 성장률을 기록하고 있습니다. 클라우드 기반 계획 소프트웨어와 원내 3D 프린팅을 통한 얼라이너는 사이클 타임을 단축하고, 치료 건수를 증가시키고 있습니다.
보철 치과 분야에서는 불소나 칼슘 이온을 방출하는 생체활성 복합레진을 이용한 저침습적 치질 형성이 채택되어 보철물의 수명을 연장하고 있습니다. 치근관 치료 분야에서는 생체 세라믹 실러나 시술 시간을 단축하는 왕복 운동 파일과 같은 혁신적인 기술이 도입되고 있습니다. 치주학 분야에서는 새로운 부착을 촉진하는 재생막이나 법랑질 매트릭스 유도체가 활용되고 있습니다. 심미 치과 치료는 본인 부담 치료 증가, 소셜 미디어를 통한 노출 확대, 원격 상담의 편의성 향상 등으로 인해 그 기세가 더욱 거세지고 있습니다.
지역별 분석
2025년, 북미는 전 세계 매출의 42.95%를 차지했습니다. 임플란트 치료나 투명 교정기 사례는 고가 대에서 제공되고 있지만, 보험사의 예방 치과 급여 확대에 따라 실런트나 불소 바니시의 사용량이 증가하고 있습니다. FDA 510(k)에 기반한 규제 명확화로 제품 출시가 가속화되고 있습니다. 그러나 치과의사 수 증가에 따른 경쟁 심화로 인해 일반 상품 분야의 가격 민감도가 높아질 가능성이 있습니다.
아시아태평양은 도시 중산층의 확대와 인바운드 치과 관광에 힘입어 2031년까지 연평균 성장률(CAGR) 9.22%를 나타낼 것으로 예측됩니다. 인도와 태국 정부는 지방 진료소를 정비하기 위해 민관 협력을 추진하고 있습니다. 현지 제조업체들은 비용 경쟁력이 있는 스캐너와 임플란트 시스템을 제공하는 동시에, 재료 인증 분야에서 세계 대기업과 제휴함으로써 공급망을 단축하고 수입 관세에 대한 대책을 마련하고 있습니다.
유럽은 견실한 보험 환급 제도와 엄격한 제품 품질 기준에 힘입어 8.14%라는 안정적인 연평균 성장률(CAGR)을 유지하고 있습니다. 독일의 정밀 공학 기반은 고강도 세라믹 생산을 뒷받침하고 있는 반면, 영국에서는 국민보건서비스(NHS)의 현대화 자금을 통해 디지털 치과의 도입이 가속화되고 있습니다. 중동 및 아프리카 및 남미에서는 민간 보험 보급률 향상과 공공 구강 보건 캠페인을 통해 접근성이 확대되어, 각각 7.52% 및 7.63%의 연평균 성장률(CAGR)을 기록하고 있습니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the dental consumables market size was valued at USD 39.99 billion in 2025 and estimated to grow from USD 43.26 billion in 2026 to reach USD 64.12 billion by 2031, at a CAGR of 8.18% during the forecast period (2026-2031).
This report is Segmented by Product Type (Aligners & Braces, Anesthetics, and More), Treatment Modality (Restorative, Prosthodontic, and More), Distribution Channel (Offline [B2B and B2C] and Online), End-User (Dental Clinics, Dental Hospitals and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Dental Consumables Market Trends and Insights
Rising demand for same-day CAD/CAM prosthetics
More than half of U.S. dental practices already employ intraoral scanners, shortening treatment cycles and expanding indications for premium restorative materials. Chairside milling paired with cloud design services lowers laboratory overhead and lifts profitability. AI-enabled design modules automate complex margin and contact adjustments, further reducing chairtime. Adoption accelerated by 18% in 2024, and with scanner integration set to improve imaging precision in 2025, material throughput is expected to rise in tandem. Suppliers capable of bundling scanners, mills, and validated material blocks are securing long-term contracts with DSOs.
Elderly population expansion increasing prosthodontic procedures
Adults aged 65 plus represent the fastest-growing patient cohort. Japan already allocates specialized reimbursement pathways for implant-supported overdentures, and the EU's Silver Economy program earmarks funds for geriatric dental care. Digital denture workflows reduce appointment burden, improving acceptance among seniors with mobility constraints. Material suppliers are commercializing lightweight polymer bases and high-impact acrylics tailored to xerostomia-prone patients.
Limited insurance reimbursement for cosmetic dentistry
Aesthetic veneers, bleaching, and gingival contouring remain predominantly self-pay. While Medicare will extend coverage to certain medically-linked dental procedures in 2025, elective cosmetic benefits remain constrained. This bifurcates the market, sustaining luxury segments yet limiting total unit volumes. Manufacturers counteract by offering tiered composite lines that balance price and polish retention.
Other drivers and restraints analyzed in the detailed report include:
- Growth of dental service organizations (DSOs) driving bulk procurement
- Shift toward bioactive and regenerative implant materials
- Skills gap in chair-side CAD/CAM workflows
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Dental implants accounted for 18.10% of the dental consumables market share in 2025. High-success bioactive coatings and digital surgical planning expand indications into softer bone situations. The dental consumables market size for personal protective wear is forecast to climb at 9.74% CAGR to 2031, notably buoyed by Asia Pacific's geriatric cohorts. The segment's sharp trajectory is further propelled by infection-control protocols that demand ASTM-certified respirators and autoclavable eye shields.
The prosthetics sub-segment benefits from CAD/CAM workflows that fabricate zirconia and lithium-disilicate crowns in under one hour. Universal bonding agents streamline inventory by covering multiple etching strategies. Regenerative materials such as calcium-phosphate granules grow in tandem with ridge-augmentation procedures. Meanwhile, sutures and burs, although mature, enjoy marginal gains from ergonomic handle redesigns that reduce operator fatigue.
Prosthodontic procedures accounted for 27.35% share of the dental consumables market in 2025 as full-arch rehabilitation moves chairside through guided surgery and immediate loading. Orthodontics, driven by clear aligners, records the highest modality growth of 9.42%; cloud-planning software and in-house 3-D printed aligners reduce cycle time and boost case starts.
Restorative dentistry embraces minimally invasive preps using bioactive composites that release fluoride and calcium ions, prolonging restoration life. Endodontics innovates with bioceramic sealers and reciprocation-motion files that cut procedure time. Periodontics integrates regenerative membranes and enamel-matrix derivatives that encourage new attachment. Cosmetic procedures, although self-funded, gain momentum via social media exposure and rising tele-consultation convenience.
Complete Report Scope:
- By Product Type
- Aligners & Braces
- Anesthetics
- Bonding Agents & Adhesives
- Dental Burs
- Dental Implants
- Dental Splints
- Dental Sutures
- Hemostats
- Personal Protective Wear
- Prosthetics
- Regenerative Materials
- Restorative Materials
- Other Product Types
- By Treatment Modality
- Restorative
- Prosthodontic
- Endodontic
- Periodontic
- Orthodontic
- Cosmetic / Aesthetic
- Others
- By Distribution Channel
- Offline
- B2B
- B2C
- Online
- Offline
- By End-User
- Dental Clinics
- Dental Hospitals
- DSO / Group Practices
- Other End-Users
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 42.95% of global revenue in 2025. Implant therapy and clear-aligner cases command premium pricing, while insurers expand preventive benefits that lift sealant and fluoride varnish volumes. Regulatory clarity under FDA 510(k) accelerates product launches; however competition among a growing dentist workforce may intensify price sensitivity in commodity segments.
Asia Pacific is projected to grow at 9.22% CAGR through 2031, buoyed by urban middle-class expansion and inbound dental tourism. Governments in India and Thailand endorse public-private partnerships to equip rural clinics. Local manufacturers capitalize by offering cost-competitive scanners and implant systems while partnering with global majors for material validation, shortening supply chains and countering import tariffs.
Europe maintains steady 8.14% CAGR supported by robust reimbursement frameworks and rigorous product-quality standards. Germany's precision-engineering base nurtures high-strength ceramic production, while the United Kingdom accelerates digital dentistry adoption via NHS modernization funds. The Middle East & Africa and South America post 7.52% and 7.63% CAGRs respectively as private insurance penetration and public oral-health campaigns broaden access.
- Coltene Holding
- Dentsply Sirona
- Envista Holdings
- GC Corporation
- Henry Schein
- Hu-Friedy Mfg Co. LLC
- Ivoclar Vivadent
- Jeil Medical
- Kuraray Noritake Dental
- Nakanishi
- Osstem Implant
- Patterson Companies
- Septodont
- Shofu Inc.
- Solventum Corporation
- Straumann Group
- Thommen Medical
- Ultradent Products
- Young Innovations
- Ziacom Medical
- ZimVie
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand for same-day CAD/CAM prosthetics
- 4.2.2 Elderly population expansion increasing prosthodontic procedures
- 4.2.3 Growth of dental service organisations (DSOs) driving bulk procurement
- 4.2.4 Rapid adoption of clear-aligner orthodontics
- 4.2.5 Shift toward bio-active and regenerative implant materials
- 4.2.6 Preventive-oral care campaigns boosting sealant consumption
- 4.3 Market Restraints
- 4.3.1 Limited insurance reimbursement for cosmetic dentistry
- 4.3.2 Skills gap in chair-side CAD/CAM workflows
- 4.3.3 Volatile resin and precious-metal prices
- 4.3.4 Regulatory delays for novel bio-ceramic approvals
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Outlook
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Aligners & Braces
- 5.1.2 Anesthetics
- 5.1.3 Bonding Agents & Adhesives
- 5.1.4 Dental Burs
- 5.1.5 Dental Implants
- 5.1.6 Dental Splints
- 5.1.7 Dental Sutures
- 5.1.8 Hemostats
- 5.1.9 Personal Protective Wear
- 5.1.10 Prosthetics
- 5.1.11 Regenerative Materials
- 5.1.12 Restorative Materials
- 5.1.13 Other Product Types
- 5.2 By Treatment Modality
- 5.2.1 Restorative
- 5.2.2 Prosthodontic
- 5.2.3 Endodontic
- 5.2.4 Periodontic
- 5.2.5 Orthodontic
- 5.2.6 Cosmetic / Aesthetic
- 5.2.7 Others
- 5.3 By Distribution Channel
- 5.3.1 Offline
- 5.3.1.1 B2B
- 5.3.1.2 B2C
- 5.3.2 Online
- 5.3.1 Offline
- 5.4 By End-User
- 5.4.1 Dental Clinics
- 5.4.2 Dental Hospitals
- 5.4.3 DSO / Group Practices
- 5.4.4 Other End-Users
- 5.5 By Geography (Value)
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Product Portfolio Analysis
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.4.1 Coltene Holding AG
- 6.4.2 Dentsply Sirona
- 6.4.3 Envista Holdings
- 6.4.4 GC Corporation
- 6.4.5 Henry Schein Inc.
- 6.4.6 Hu-Friedy Mfg Co. LLC
- 6.4.7 Ivoclar Vivadent AG
- 6.4.8 Jeil Medical Corporation
- 6.4.9 Kuraray Noritake Dental
- 6.4.10 Nakanishi Inc.
- 6.4.11 Osstem Implant Co. Ltd
- 6.4.12 Patterson Companies Inc.
- 6.4.13 Septodont Holding
- 6.4.14 Shofu Inc.
- 6.4.15 Solventum Corporation
- 6.4.16 Straumann Group
- 6.4.17 Thommen Medical AG
- 6.4.18 Ultradent Products Inc.
- 6.4.19 Young Innovations Inc.
- 6.4.20 Ziacom Medical
- 6.4.21 ZimVie Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment


