

|
시장보고서
상품코드
2121720
남미의 농약 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)South America Agrochemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
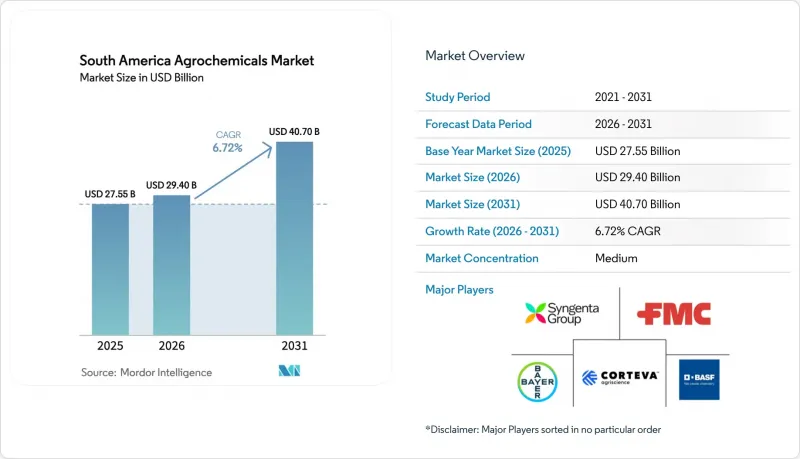
에 의하면, 남미의 농약 시장 규모는 2025년에 275억 5,000만 달러로 평가되었고, 2026년에는 294억 달러에 이를 것으로 추정되고 있습니다.
또한 2031년까지 407억 달러로 성장하여, 예측 기간(2026-2031년) 동안 연평균 성장률(CAGR) 6.72%를 기록하며 확대될 것으로 전망됩니다.
본 보고서는 제품 유형별(비료, 작물 보호용 화학물질, 첨가제 등), 작물 유형별(곡물, 유지종자 및 콩류 등), 국가별(브라질, 아르헨티나 등)로 분류되어 있습니다. 시장 예측은 금액(달러)으로 표시되어 있습니다.
남미의 농약 시장 동향 및 인사이트
대두 재배 면적 확대
브라질에서는 2024-2025년 시즌에 4,620만 헥타르의 대두가 재배되어 전년 대비 3.8% 증가했습니다. 또한, 아르헨티나에서는 2025년에 1,680만 헥타르에 달하며, 이전 가뭄으로 인한 감산에서 회복했습니다. 재배 면적 확대에 따라 제초제 사용량도 증가하고 있습니다. 이는 헥타르당 글리포세이트, 잔효성 발아 전 제초제, 번다운제 등을 2-3회 연속으로 살포하기 때문입니다. 비료 수요도 꾸준히 증가하고 있습니다. 브라질 대두 재배에서 NPK의 평균 사용량은 2020년 헥타르당 168kg에서 2025년에는 185kg으로 증가했습니다. 대두와 옥수수의 이모작 모델이 강화됨에 따라 살포 기간이 단축되었고, 높은 작업 높이를 가진 분무기를 사용하여 살포하는 ‘즉용형’ 액체 제제가 선호되고 있습니다. 현재 브라질 대두 재배 면적의 97%를 제초제 내성 품종이 차지하고 있으며, 이에 따른 ‘오버 더 톱(Over-the-top)’ 살포는 잡초 방제를 효율화하지만, 아마란서스속의 내성화를 촉진하고 있습니다.
제초제 내성 생명공학 종자의 도입
2025년 파종 시즌에 아르헨티나와 브라질의 대두 종자 판매의 대부분은 글리포세이트 및 글루호시네이트 내성 형질이 차지했습니다. 코르테바(Corteva)사의 ‘Enlist E3’ 플랫폼은 브라질에서 시장 점유율을 확대했으며, 이에 따른 보완적 제초제인 ‘Enlist One’ 및 ‘Enlist Duo’의 판매도 증가했습니다. BASF사의 ‘Xtend’ 기술이 적용된 ‘Credenz’ 품종은 아르헨티나에서 재배 면적을 확대하며 ‘Engenia’의 판매량도 끌어올렸습니다. 형질과 농약의 연계는 통합형 공급업체에게 지속적인 수익원이 되지만, 한편으로는 할인 협상을 진행하는 대규모 농가로의 구매력 집중을 초래하고 있습니다. 파라과이에서는 협동조합이 종자, 제초제, 대출을 한 세트로 묶은 패키지를 제공함에 따라, 2023년부터 2025년에 걸쳐 인증 종자의 사용이 대폭 증가했습니다.
합성 유효 성분에 대한 더욱 엄격한 금지 조치
브라질 국립보건감시청(ANVISA)은 파라콰트의 단계적 폐지를 2026년 12월까지로 예정하고, 2,4-D의 사용을 2027년까지 폐쇄형 시스템으로 제한했습니다. 2024년, 파라콰트는 브라질 제초제 판매량의 8%를 차지했습니다. 글루호시네이트나 사프루페나실로의 대체로 인해 1헥타르당 비용은 최대 50% 증가하며, 새로운 살포 시기 설정이 필요하게 됩니다. 아르헨티나 농업식품위생품질국(SENASA)은 2027년 중반까지 클로르피리포스와 카보프란의 사용 금지를 발표했으며, 이는 옥수수 및 사탕수수의 살충제 살포 계획에 영향을 미칠 것입니다. 규제 준수를 위한 투자는 대규모 농장에 유리하게 작용합니다. 소규모 농가는 살포 빈도를 줄일 가능성이 있어, 수확량 감소의 위험을 감수하게 됩니다.
부문 분석
2025년에는 작물 보호용 화학물질이 시장을 독점하며, 제품 유형별 매출의 65.8%를 차지했습니다. 이는 이 지역 전체에 걸쳐 광대한 농지를 보호하는 데 있어 제초제, 살충제, 살균제 및 기타 농약이 수행하는 역할의 중요성을 여실히 보여줍니다. 비료는 매출액 기준 두 번째로 큰 시장 점유율을 차지했으며, 전 세계적인 가격 변동에도 불구하고 요소와 칼륨의 수입량을 확보한 브라질의 무관세 수입 정책에 힘입었습니다. 보조제는 점유율은 작지만 가장 빠르게 성장하는 부문으로 부상했습니다. 이 부문은 정밀 살포 시스템과 드론을 이용한 살포의 보급, 그리고 점점 더 복잡해지는 탱크 혼합에서 고급 계면활성제, 드리프트 억제제, pH 조절제에 대한 수요에 힘입어 2031년까지 연평균 성장률(CAGR) 9.2%를 나타낼 것으로 예측됩니다.
작물 보호 분야에서는 제초제 내성 대두 재배 시스템의 보급에 힘입어 제초제가 여전히 수요의 주요 원동력으로 작용하고 있습니다. 살충제와 살균제는 면화, 옥수수, 대두, 포도 및 기타 고부가가치 작물에 영향을 미치는 해충 및 병해의 압력으로 인해 계속해서 중요한 역할을 하고 있습니다. 보조제의 성장은 스팟 살포 및 가변 살포 기술의 도입과 밀접한 관련이 있으며, 이로 인해 처리 면적 1헥타르당 보조제 사용량이 증가하고 있습니다. 비료는 유리한 정책과 안정적인 수요에 힘입어, 특히 질소계 및 칼륨계 제품에서 계속해서 성장세를 보이고 있습니다. 식물 생장 조절제는 시장 규모 면에서는 틈새 시장 수준에 머물러 있지만, 높은 이익률과 사탕수수 및 수출용 과수 작물에서의 용도 확대에 힘입어 꾸준한 성장을 보이고 있습니다. 이 틈새 시장은 2031년까지 특화된 성장을 이룰 것으로 예측됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.09According to Mordor Intelligence, the South America agrochemicals market size was valued at USD 27.55 billion in 2025 and is estimated to reach USD 29.40 billion in 2026, further projected to grow to USD 40.70 billion by 2031, expanding at a CAGR of 6.72% over the forecast period (2026-2031).
This report is Segmented by Product Type (Fertilizers, Crop Protection Chemicals, Adjuvants, and More), by Crop Type (Cereals and Grains, Oilseeds and Pulses, and More), and by Country (Brazil, Argentina, and More). The Market Forecasts are Provided in Terms of Value (USD).
South America Agrochemicals Market Trends and Insights
Expansion of soybean cultivation area
Brazil planted 46.2 million ha of soybeans in the 2024-2025 season, up 3.8% year on year, and Argentina reached 16.8 million ha in 2025, reversing prior drought losses. Larger acreage lifts herbicide volumes because each hectare receives 2-3 sequential applications, including glyphosate, residual pre-emergents, and burndown chemistries. Fertilizer demand is increasing steadily. The average NPK usage in Brazilian soybean cultivation rose to 185 kg per hectare in 2025, compared to 168 kg per hectare in 2020. The intensified soy-corn double-crop model compresses spray windows, favoring ready-to-mix liquids applied via high-clearance sprayers. Herbicide-tolerant varieties now cover 97% of Brazilian soybean hectares, enabling over-the-top applications that streamline weed control but spur resistance in Amaranthus species.
Adoption of Herbicide-Tolerant Biotech Seeds
Glyphosate- and glufosinate-tolerant traits dominated the majority of soybean seed sales in Argentina and Brazil during the 2025 planting season. Corteva's Enlist E3 platform gained a higher market share in Brazil, lifting sales of complementary herbicides Enlist One and Enlist Duo. BASF's Credenz varieties with Xtend technology captured larger Argentine acreage, boosting Engenia volumes. Trait-chemistry linkages lock in recurring revenue for integrated suppliers but concentrate purchasing power among large growers that negotiate discounts. The use of certified seeds in Paraguay increased significantly between 2023 and 2025, driven by cooperatives offering bundled packages that included seeds, herbicides, and credit.
Stricter Bans on Synthetic Active Ingredients
Brazilian National Health Surveillance Agency (ANVISA) scheduled paraquat phase-out by December 2026 and restricted 2,4-D use to closed systems by 2027. Paraquat represented 8% of Brazilian herbicide volume in 2024. Substitution with glufosinate or saflufenacil raises per-hectare costs by up to 50% and requires new application timing. National Service of Agri-Food Health and Quality SENASA (Argentina) announced bans on chlorpyrifos and carbofuran by mid-2027, impacting corn and sugarcane insecticide programs. Compliance investments favor large farms. Smaller growers may cut application frequency, risking yield losses.
Other drivers and restraints analyzed in the detailed report include:
- Government fertilizer subsidy programs
- Climate-linked crop-insurance uptake
- Volatile Raw-Material Costs (Oil-Derived Intermediates)
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Crop protection chemicals dominated the market in 2025, contributing 65.8% of product-type revenue. This emphasizes the role of herbicides, insecticides, fungicides, and other pesticides in protecting vast hectares of crops across the region. Fertilizers accounted for the next largest market share of revenue, supported by Brazil's zero-tariff import policy, which ensured high urea and potash volumes despite global price fluctuations. Adjuvants, while comprising a smaller share, emerged as the fastest-growing segment. This segment is projected to grow at a 9.2% CAGR through 2031, driven by the adoption of precision-spraying systems, drone applications, and the demand for advanced surfactants, drift-control agents, and pH conditioners in increasingly complex tank mixes.
Within crop protection, herbicides remain the key driver of demand, supported by herbicide-tolerant soybean systems. Insecticides and fungicides continue to play a vital role due to pest and disease pressures affecting crops such as cotton, corn, soybeans, grapes, and other high-value crops. Adjuvant growth is closely associated with the adoption of spot-spraying and variable-rate technologies, which boost adjuvant usage per treated hectare. Fertilizers continue to gain traction, particularly in nitrogenous and potassic products, supported by favorable policies and consistent demand. Plant growth regulators, while accounting for niche market value, show steady growth due to their high margins and expanding applications in sugarcane and export-oriented fruit crops. This niche segment is anticipated to experience specialized growth through 2031.
Complete Report Scope:
- By Product Type
- Fertilizers
- Nitrogenous
- Phosphatic
- Potassic
- Other Fertilizers
- Crop Protection Chemicals
- Herbicides
- Insecticides
- Fungicides
- Other Pesticides
- Adjuvants
- Plant Growth Regulators
- Fertilizers
- By Crop Type
- Cereals and Grains
- Oilseeds and Pulses
- Fruits and Vegetables
- Commercial Crops
- Turf and Ornamentals
- By Country
- Brazil
- Argentina
- Colombia
- Chile
- Peru
- Rest of South America
List of Companies Covered in this Report:
- Bayer AG
- Syngenta Group
- BASF SE
- Corteva Agriscience
- FMC Corporation
- UPL Ltd.
- Sumitomo Chemical Co., Ltd.
- Nufarm Ltd.
- Nutrien Ltd.
- Yara International ASA
- Lavoro Agro Holding S.A.
- Haifa Negev technologies LTD
- Albaugh LLC
- Compo Expert Brasil Fertilizantes Ltda. (Azoty Group S.A)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of soybean cultivation area
- 4.2.2 Adoption of herbicide-tolerant biotech seeds
- 4.2.3 Government fertilizer subsidy programs
- 4.2.4 Growth in export-oriented specialty crops
- 4.2.5 Climate-linked crop-insurance uptake
- 4.2.6 AI-driven precision-spraying technologies
- 4.3 Market Restraints
- 4.3.1 Stricter bans on synthetic active ingredients
- 4.3.2 Volatile raw-material costs (oil-derived intermediates)
- 4.3.3 Rising herbicide resistance in key weed species
- 4.3.4 Amazon corridor logistics bottlenecks
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Suppliers
- 4.6.3 Bargaining Power of Buyers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Fertilizers
- 5.1.1.1 Nitrogenous
- 5.1.1.2 Phosphatic
- 5.1.1.3 Potassic
- 5.1.1.4 Other Fertilizers
- 5.1.2 Crop Protection Chemicals
- 5.1.2.1 Herbicides
- 5.1.2.2 Insecticides
- 5.1.2.3 Fungicides
- 5.1.2.4 Other Pesticides
- 5.1.3 Adjuvants
- 5.1.4 Plant Growth Regulators
- 5.1.1 Fertilizers
- 5.2 By Crop Type
- 5.2.1 Cereals and Grains
- 5.2.2 Oilseeds and Pulses
- 5.2.3 Fruits and Vegetables
- 5.2.4 Commercial Crops
- 5.2.5 Turf and Ornamentals
- 5.3 By Country
- 5.3.1 Brazil
- 5.3.2 Argentina
- 5.3.3 Colombia
- 5.3.4 Chile
- 5.3.5 Peru
- 5.3.6 Rest of South America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Bayer AG
- 6.4.2 Syngenta Group
- 6.4.3 BASF SE
- 6.4.4 Corteva Agriscience
- 6.4.5 FMC Corporation
- 6.4.6 UPL Ltd.
- 6.4.7 Sumitomo Chemical Co., Ltd.
- 6.4.8 Nufarm Ltd.
- 6.4.9 Nutrien Ltd.
- 6.4.10 Yara International ASA
- 6.4.11 Lavoro Agro Holding S.A.
- 6.4.12 Haifa Negev technologies LTD
- 6.4.13 Albaugh LLC
- 6.4.14 Compo Expert Brasil Fertilizantes Ltda. (Azoty Group S.A)


