

|
시장보고서
상품코드
2121806
가속도계 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Accelerometer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
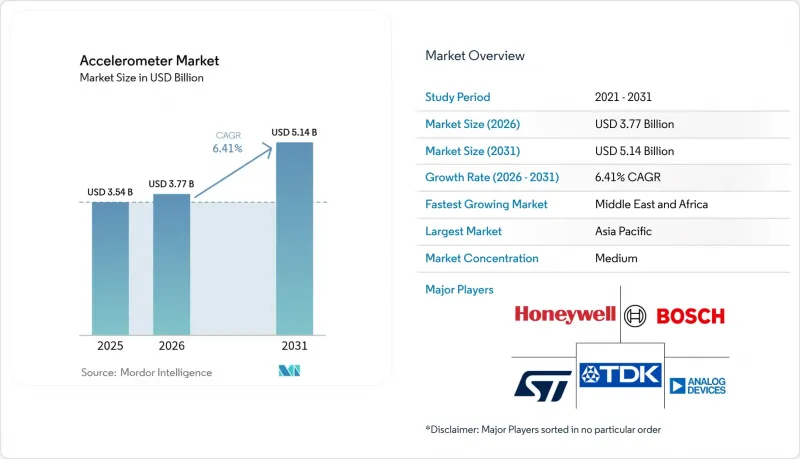
에 의하면, 가속도계 시장 규모는 2025년 35억 4,000만 달러로 평가되었고, 2026년에는 37억 7,000만 달러로 추정되고, 2026-2031년 CAGR 6.41%로 성장을 지속할 전망이며, 2031년에는 51억 4,000만 달러에 이를 것으로 예측됩니다.
본 보고서는 유형별(MEMS 가속도계, 압전식 가속도계 등), 축 수별(1축, 2축 등), 최종 사용자별(소비자 가전, 자동차 등), 성능 등급별(소비자용 등급, 산업용 등급 등), 지역별(북미, 남미 등)로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
세계의 가속도계 시장 동향 및 인사이트
MEMS의 소형화 및 비용 절감
3세대 MEMS 공정에서는 노이즈 밀도를 저하시키지 않으면서 칩 크기와 소비 전력을 줄일 수 있는 1mm 미만의 프루프매스 구조 제조가 가능해졌습니다. Bosch의 소형 2024 가속도계 시리즈는 웨이퍼 레벨 칩 스케일 패키징(WLCSP)을 통해 ±2g에서 ±16g의 동적 범위를 유지하면서 재료 비용을 절감할 수 있는 좋은 예입니다. 더 큰 규모의 300mm MEMS 팹은 추가적인 규모의 경제를 가져와, 각 OEM 업체가 부품표(BOM) 예산을 더욱 엄격하게 관리하면서도 추가적인 센싱 기능에 예산을 할당할 수 있게 해줍니다. STMicroelectronics의 LIS2DUXS12는 마이크로와트 수준의 이벤트 분류를 가능하게 하는 머신 러닝 코어를 통합하고 있어, 컴패니언 MCU가 필요 없게 됨으로써 기판의 실적를 축소합니다. 파운드리 업체들이 더 큰 웨이퍼로 전환함에 따라 평균 판매 가격은 하락하고, 비용에 민감한 IoT 노드의 잠재적 수요가 자극되어 가속도계 시장의 성장 주기가 더욱 강화될 것입니다.
소비자 가전 및 웨어러블 기기의 붐
스마트폰, 이어폰, 피트니스 트래커는 여전히 판매량의 주축이지만, 2025년 설계 로드맵을 살펴보면 30μg/√Hz 미만의 노이즈 플로어와 며칠간의 배터리 구동 시간을 가능하게 하는 연속 작동을 필요로 하는 의료용 웨어러블 기기로의 전환이 가속화되고 있음을 알 수 있습니다. Analog Devices의 ADXL380은 듀얼 신호 경로를 갖춘 완전 무선 이어폰을 대상으로 하며, 단일 센서로 능동형 소음 제거 피드백과 머리 제스처 인식을 모두 지원합니다. 의료기기 분야에서는 센서에 내장된 AI 추론 기능으로 클라우드 처리 부하가 경감되어, IEC 60601-1 규격을 준수하고 병원 사용이 인증된 낙상 감지 웨어러블 단말기의 구현이 가능해졌습니다. 부가가치가 높은 임상 용도는 이익률에 대한 압박을 완화하는 동시에, 최저 가격보다 품질을 중시하는 규제가 엄격한 의료 채널로 가속도계 시장을 확대시키고 있습니다.
가격 압박과 상품화
스마트폰 분야에서는 2022-2024년 관성 센싱용 부품 원가(BOM) 비중이 30% 가까이 축소되어, 공급업체들은 임베디드형 ML 코어나 저전력 서스펜드 모드를 통해 차별화를 꾀할 수밖에 없는 상황입니다. Kionix의 KX224 시리즈는 100만 개 단위의 출하량 기준으로 0.30달러 미만에 판매되고 있어, 구형 부품의 평균 판매 가격 하락을 여실히 보여주고 있습니다. 각 벤더들은 이익률 회복을 위해 자동 보정 기술에 투자하고 있지만, 공장 내 트림 작업으로 인해 설비 투자가 증가하면서 그 효과가 상쇄되고 있습니다. 이러한 불균형으로 인해 많은 경쟁사들은 손익분기점 부근의 수익 상태를 벗어나지 못하고 있으며, 이는 가속도계 시장의 단기적인 매출 확대를 억제하고 있습니다.
부문 분석
MEMS 디바이스는 타의 추종을 불허하는 가성비 덕분에 2025년에는 가속도계 시장 점유율의 71.35%를 차지했습니다. 200mm 웨이퍼를 이용한 양산과 웨이퍼 레벨 패키징의 조합을 통해 MEMS는 스마트폰, 웨어러블 기기, 자동차용 ECU에서 핵심적인 위치를 확립하고 있습니다. 압전식 유닛은 시장 규모는 작지만, 방위 및 항공우주 분야 사업자들로부터 1µg 미만의 바이어스 안정성과 내방사선성이 요구됨에 따라 연평균 7.42%의 성장률을 보이고 있습니다. 압전 저항식 및 정전 용량식 변형 제품은 절대적인 정밀도보다 내충격성이나 초저전력 소비가 우선시되는 틈새 산업용도로 활용되고 있습니다.
MEMS의 우위는 집적화의 이점에 의해 뒷받침됩니다. STMicroelectronics의 센서 허브 아키텍처는 디지털 머신 러닝 코어와 FIFO 버퍼를 다이 상에 직접 통합하여 외부 부품의 수를 줄이고 있습니다. 그러나 가속도 범위, 극한 온도 또는 바이어스 안정성이 MEMS의 한계를 초과하는 경우, 설계자들은 압전 스택으로 되돌아갑니다.
완전한 6자유도 측정 추세에 따라 2025년에는 3축 가속도계의 매출 점유율이 63.90%를 나타낸 것으로 평가되었습니다. OEM 업체들은 센서 퓨전의 오버헤드를 최소화하면서 제스처 인식 및 진동 진단을 지원하기 위해 X-Y-Z 통합 측정값을 선호합니다. 한편, 6축 또는 9축 기능을 통합한 콤보 IMU는 드론, AR/VR 헤드셋, 로봇 공학을 주축으로 8.05%의 성장 궤도를 보이고 있으며, 자이로와 가속도계의 동기화된 데이터를 통해 알고리즘 조정이 간소화되고 있습니다. 단축 장치는 여전히 틸트 스위치나 자동차 에어백 작동 장치 등에 사용되고 있지만, 그 점유율은 꾸준히 감소하고 있습니다.
Collins Aerospace의 SiIMU02는 다축 통합형 하이엔드 제품의 한 예로, 손바닥 크기의 MEMS 어셈블리에서 광섬유 자이로스코프에 필적하는 정확도를 실현하고 있습니다. 중급 소비자용 제품의 경우, 각 공급업체들은 가속도계, 자이로스코프, 경우에 따라 자력계를 프로그래밍 가능한 디지털 필터가 탑재된 단일 ASIC 위에 통합하고 있습니다. 이러한 통합으로 PCB 면적과 부품 원가가 절감되어, 용도의 복잡성이 증가하는 상황에서도 가속도계 시장의 성장세가 유지되고 있습니다.
지역별 분석
2025년, 아시아태평양은 전 세계 매출의 46.10%를 차지했으며, 중국의 가전제품 수출 거점과 8인치 MEMS 파운드리 밀집 네트워크가 이를 뒷받침했습니다. 선전에 본사를 둔 MEMSIC은 국내 스마트폰 OEM 제조업체를 대상으로 커패시터형 가속도계에 주력한 결과, 3자리 수의 성장을 기록했습니다. 일본과 한국은 자동차 및 산업 분야를 대상으로 고신뢰성 모델을 공급하고 있는 반면, 대만의 전문 파운드리 업체들은 수탁 생산을 뒷받침하고 있습니다. 이 지역의 가속도계 시장은 연평균 성장률(CAGR) 6.08%로 꾸준히 확대될 전망이지만, 웨이퍼 생산 능력의 제약과 인건비 상승이 성장세를 둔화시키고 있습니다.
중동 및 아프리카는 2031년까지 8.33%라는 가장 높은 연평균 성장률(CAGR)을 보일 것으로 전망됩니다. 이는 사우디아라비아의 ‘비전 2030’에 따른 부양책이 현지 반도체 이니셔티브에 자금을 지원하고, 터빈 진동 모니터링이 필요한 재생에너지 자산을 확대하고 있기 때문입니다. 이집트와 모로코의 풍력 발전소에서는 ISO 10816 예측 유지보수 기준을 충족하기 위해 3축 가속도계가 채택되고 있습니다. 유럽의 센서 제조업체들과의 지역적 민관 파트너십을 통해 기술 이전이 촉진되고 현지 생산이 가속화됨에 따라, 현지 가속도계 시장의 성장 궤도가 상승하고 있습니다.
북미는 자동차 분야의 ADAS(첨단 운전자 지원 시스템) 규제 도입과 첨단 산업용 IoT 도입 기반에 힘입어 견고한 2위 자리를 유지하고 있습니다. 석유 및 가스, 화학, 금속 업계에서 인더스트리 4.0 유지보수 전략을 채택함에 따라, 내환경성이 뛰어나고 위험 구역 대응 인증을 받은 가속도계에 대한 수요가 증가하고 있습니다. 유럽은 약간 뒤처져 있지만, 각 OEM 업체들이 품질과 기능 안전을 우선시하고 있어 평균 판매 가격은 높은 임베디드니다. ‘호라이즌 유럽(Horizon Europe)’의 로봇공학 프로젝트에 대한 EU의 자금 지원은 고정밀 센서의 도입을 더욱 촉진하여, 가속도계 시장에서 해당 지역의 입지를 강화하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the accelerometer market size is expected to grow from USD 3.54 billion in 2025 to USD 3.77 billion in 2026 and is forecast to reach USD 5.14 billion by 2031 at 6.41% CAGR over 2026-2031.
This report is Segmented by Type (MEMS Accelerometers, Piezoelectric Accelerometers, and More), Dimension (1-Axis, 2-Axis, and More), End User (Consumer Electronics, Automotive, and More), Performance Grade (Consumer Grade, Industrial Grade, and More), and Geography (North America, South America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Accelerometer Market Trends and Insights
MEMS Miniaturization and Cost Reduction
Third-generation MEMS processes now fabricate sub-millimeter proof-mass structures that cut die size and power draw without degrading noise density. Bosch's miniature 2024 accelerometer series exemplifies how wafer-level chip-scale packaging lowers material cost while sustaining +-2 g to +-16 g dynamic range. Larger 300 mm MEMS fabs promise further scale economies, allowing OEMs to allocate tighter bill-of-materials budgets to additional sensing functions. STMicroelectronics' LIS2DUXS12 integrates a machine-learning core enabling event classification at microwatt levels, removing the need for a companion MCU and shrinking board footprint. As foundries migrate to larger wafers, average selling prices decline and unlock latent demand in cost-sensitive IoT nodes, reinforcing the growth loop for the accelerometer market.
Consumer Electronics and Wearables Boom
Smartphones, earbuds and fitness trackers remain volume engines, but 2025 design roadmaps reveal an accelerating pivot toward medical-grade wearables that require sub-30 μg/√Hz noise floors and continuous operation for multi-day battery life. Analog Devices' ADXL380 targets true-wireless earbuds with dual signal paths so a single sensor supports both active-noise-cancellation feedback and head-gesture recognition. In medical devices, AI-inference embedded in the sensor offloads cloud processing, enabling fall-detection wearables certified under IEC 60601-1 for hospital use. Higher-value clinical applications ease margin pressure and expand the accelerometer market into regulated healthcare channels that favor quality over lowest price.
Price Pressure and Commoditization
In smartphones the bill-of-materials allotment for inertial sensing shrank by nearly 30% between 2022 and 2024, pushing suppliers to differentiate with embedded ML cores and lower power-suspend modes. Kionix's KX224 series sells below USD 0.30 at million-piece volumes, underscoring deteriorating average selling prices for legacy parts. Vendors invest in automated calibration to recoup margin; however, factory-trim routines raise capex and erode benefit. The imbalance confines many competitors to break-even PandL positions, tempering near-term revenue expansion for the accelerometer market.
Other drivers and restraints analyzed in the detailed report include:
- Automotive ADAS / Safety Integration
- Industry-4.0 Condition Monitoring Uptake
- Accuracy Limits vs. Piezoelectric High-G
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
MEMS devices captured 71.35% accelerometer market share in 2025 owing to unmatched cost-performance balance. Volume manufacturing on 200 mm wafers combined with wafer-level packaging positions MEMS at the heart of smartphones, wearables and automotive ECUs. Piezoelectric units, while representing a smaller base, advance at 7.42% annually as defense and aerospace operators demand sub-1 µg bias stability and radiation tolerance. Piezoresistive and capacitive variants serve niche industrial uses where shock survivability or ultra-low power trumps absolute precision.
MEMS leadership rests on integration advantages. STMicroelectronics' sensor-hub architecture merges a digital machine-learning core and FIFO buffers directly on the die, trimming external component count. Still, when g-range, temperature extremes or bias stability exceed MEMS limits, designers revert to piezoelectric stacks.
The trend toward full-six-degree-of-freedom measurement places 3-axis accelerometers at 63.90% revenue share in 2025. OEMs prefer unified X-Y-Z readings to support gesture recognition and vibration diagnostics with minimal sensor fusion overhead. Meanwhile, combo IMUs embedding 6-axis or 9-axis capability demonstrate an 8.05% growth trajectory, driven by drones, AR/VR headsets and robotics, where synchronized gyro-accelerometer data simplifies algorithm tuning. Single-axis devices persist in tilt switches and automotive airbag triggers, but share steadily erodes.
Collins Aerospace's SiIMU02 illustrates the premium end of multi-axis integration, achieving near-fiber-optic gyro accuracy in a palm-sized MEMS assembly. For mid-tier consumer products, suppliers consolidate accelerometer, gyroscope and sometimes magnetometer on a single ASIC with programmable digital filters. This convergence compresses PCB area and bill-of-materials cost, ensuring the accelerometer market maintains momentum as application complexity rises.
Complete Report Scope:
- By Type
- MEMS Accelerometers
- Piezoelectric Accelerometers
- Piezoresistive Accelerometers
- Capacitive Accelerometers
- Thermal and Other Types
- By Dimension
- 1-Axis
- 2-Axis
- 3-Axis
- 6-Axis and Above (Combo IMUs)
- By End User
- Consumer Electronics
- Automotive
- Aerospace and Defense
- Industrial and Manufacturing
- Healthcare and Medical Devices
- Other End Users
- By Performance Grade
- Consumer Grade
- Industrial Grade
- Tactical Grade
- Navigation Grade
- Space Grade
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- APAC
- China
- Japan
- India
- South Korea
- Taiwan
- Southeast Asia
- Rest of APAC
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific controlled 46.10% of global revenue in 2025, anchored by China's consumer-electronics export base and a dense 8-inch MEMS foundry footprint. Shenzhen-headquartered MEMSIC recorded triple-digit growth after focusing capacitor-type accelerometers on domestic smartphone OEMs. Japan and South Korea contribute high-reliability variants for automotive and industrial sectors, while Taiwan's pure-play foundries support contract manufacturing. The region's accelerometer market will expand at a steady 6.08% CAGR, although wafer-capacity constraints and rising labor costs temper upside.
The Middle East and Africa represents the fastest 8.33% CAGR through 2031 as Saudi Arabia's Vision 2030 stimulus funds local semiconductor initiatives and scales renewable-energy assets requiring turbine vibration monitoring. Wind farms across Egypt and Morocco adopt triaxial accelerometers to meet ISO 10816 predictive-maintenance benchmarks. Regional public-private partnerships with European sensor makers expedite technology transfer, accelerating indigenous production and lifting the local accelerometer market trajectory.
North America holds a strong second position driven by automotive ADAS mandates and an advanced industrial IoT install base. Adoption of Industry-4.0 maintenance strategies across oil and gas, chemicals and metals drives demand for rugged, hazardous-area-rated accelerometers. Europe trails marginally yet enjoys higher average selling prices as OEMs prioritize quality and functional safety. EU funding for Horizon Europe robotics projects further stimulates precision-grade sensor uptake, reinforcing regional participation in the accelerometer market.
- Analog Devices Inc.
- Robert Bosch GmbH
- STMicroelectronics
- TDK InvenSense
- Honeywell International Inc.
- Murata Manufacturing Co., Ltd. (Kionix)
- NXP Semiconductors N.V.
- MEMSIC Inc.
- TE Connectivity (Measurement Specialties)
- Silicon Sensing Systems Ltd.
- Sensonor AS
- PCB Piezotronics (MTS Systems)
- Northrop Grumman LITEF GmbH
- Rockwell Automation Inc.
- Kearfott Corporation
- Meggitt PLC (Endevco)
- Dytran Instruments Inc.
- Al Cielo Inertial Solutions Ltd.
- Atlantic Inertial Systems Ltd.
- LORD MicroStrain (HBK)
- QST Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 MEMS miniaturization and cost reduction
- 4.2.2 Consumer-electronics and wearables boom
- 4.2.3 Automotive ADAS / safety integration
- 4.2.4 Industry-4.0 condition monitoring uptake
- 4.2.5 Precision-agriculture drone adoption
- 4.2.6 Renewable-energy tilt/vibration demand
- 4.3 Market Restraints
- 4.3.1 Price pressure and commoditization
- 4.3.2 Accuracy limits vs. piezoelectric high-g
- 4.3.3 8-inch MEMS foundry capacity bottlenecks
- 4.3.4 Firmware/security vulnerabilities
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers/Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS
- 5.1 By Type
- 5.1.1 MEMS Accelerometers
- 5.1.2 Piezoelectric Accelerometers
- 5.1.3 Piezoresistive Accelerometers
- 5.1.4 Capacitive Accelerometers
- 5.1.5 Thermal and Other Types
- 5.2 By Dimension
- 5.2.1 1-Axis
- 5.2.2 2-Axis
- 5.2.3 3-Axis
- 5.2.4 6-Axis and Above (Combo IMUs)
- 5.3 By End User
- 5.3.1 Consumer Electronics
- 5.3.2 Automotive
- 5.3.3 Aerospace and Defense
- 5.3.4 Industrial and Manufacturing
- 5.3.5 Healthcare and Medical Devices
- 5.3.6 Other End Users
- 5.4 By Performance Grade
- 5.4.1 Consumer Grade
- 5.4.2 Industrial Grade
- 5.4.3 Tactical Grade
- 5.4.4 Navigation Grade
- 5.4.5 Space Grade
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 APAC
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Taiwan
- 5.5.4.6 Southeast Asia
- 5.5.4.7 Rest of APAC
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Analog Devices Inc.
- 6.4.2 Robert Bosch GmbH
- 6.4.3 STMicroelectronics
- 6.4.4 TDK InvenSense
- 6.4.5 Honeywell International Inc.
- 6.4.6 Murata Manufacturing Co., Ltd. (Kionix)
- 6.4.7 NXP Semiconductors N.V.
- 6.4.8 MEMSIC Inc.
- 6.4.9 TE Connectivity (Measurement Specialties)
- 6.4.10 Silicon Sensing Systems Ltd.
- 6.4.11 Sensonor AS
- 6.4.12 PCB Piezotronics (MTS Systems)
- 6.4.13 Northrop Grumman LITEF GmbH
- 6.4.14 Rockwell Automation Inc.
- 6.4.15 Kearfott Corporation
- 6.4.16 Meggitt PLC (Endevco)
- 6.4.17 Dytran Instruments Inc.
- 6.4.18 Al Cielo Inertial Solutions Ltd.
- 6.4.19 Atlantic Inertial Systems Ltd.
- 6.4.20 LORD MicroStrain (HBK)
- 6.4.21 QST Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment


