|
시장보고서
상품코드
2121951
유럽의 발포 폴리스티렌(EPS) 시장 : 시장 점유율 분석, 업계 동향 및 통계, 성장 예측(2026-2031년)Europe Expanded Polystyrene (EPS) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
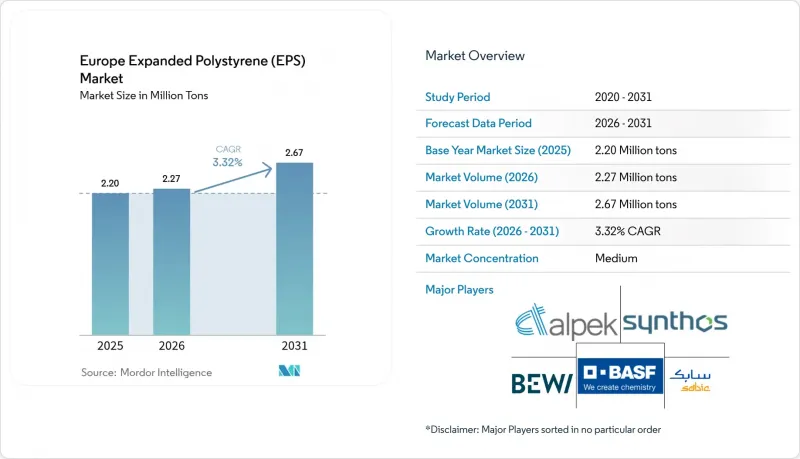
에 의하면, 유럽의 발포 폴리스티렌(EPS) 시장 규모는 2025년에 220만 톤으로 평가되었고, 2026년 227만 톤에서 2031년까지 267만 톤에 이를 것으로 예측됩니다.
예측 기간(2026-2031년) 동안 연평균 성장률(CAGR)은 3.32%를 나타낼 것으로 전망됩니다.
본 보고서는 제품 유형별(화이트 EPS, 그레이 및 실버 EPS), 최종 사용자 산업별(건축 및 건설, 전기 및 전자 기기, 포장, 기타) 및 지역별(독일, 영국, 프랑스, 이탈리아, 스페인, 노르웨이, 스웨덴, 덴마크, 핀란드, 기타)로 분류되어 있습니다. 시장 예측은 수량(톤) 기준으로 제시됩니다.
유럽의 발포 폴리스티렌(EPS) 시장 동향 및 인사이트
건축 에너지 기준이 단열 성능 요건을 촉진
각국 및 EU 전체에서 에너지 기준이 강화됨에 따라, 개발업자들은 U값이 낮은 벽, 지붕, 바닥을 설계해야 하며, 이로 인해 단열재 두께 요건이 높아지면서 유럽 발포 폴리스티렌(EPS) 시장 솔루션에 대한 안정적인 수요가 뒷받침되고 있습니다. 독일의 Gebaudeenergiegesetz(건축물 에너지법)에서는 이미 외벽의 U값을 0.20 W/(m2K) 정도로 규정하고 있으며, 이를 충족하려면 일반적으로 12-16 cm 두께의 EPS가 필요합니다. 이로 인해 높이에 따른 방화 제한이 있음에도 불구하고, 독일의 파사드 시스템에서 이 발포재가 약 40%의 점유율을 확고히 하고 있습니다. 프랑스와 북유럽 국가들도 유사한 성능 요건을 확대하고 있으며, 2024년에 개정될 건축물 에너지 성능에 관한 지침에서는 2030년 이후 신축 건물에 대해 넷 제로 의무화가 규정되어, 장기적인 단열재 수요가 확고해지고 있습니다. 또한, EU 리노베이션 웨이브(Renovation Wave)에 따라 개보수 공사의 규모도 확대되고 있으며, 보조금 제도를 통해 주택 소유자들은 단열 성능이 뛰어나면서도 합리적인 가격의 시스템을 선택하도록 유도되고 있습니다. 이러한 규제 대응이 요구되는 상황에서 각 제조업체는 네오폴이나 흑연을 배합한 제품 라인을 확충하여, 고액의 구조 개조를 수반하지 않으면서도 우수한 R값을 실현하고 있습니다.
mRNA 바이오의약품 콜드체인 확대
mRNA 백신이나 첨단 치료제의 급속한 상용화에는 공장에서 진료소에 이르기까지 2℃-8℃의 안정적인 온도 관리가 요구됩니다. 이 분야에서는 EPS제 운송 용기가 주류를 이루고 있습니다. 그 이유는 이 소재의 독립 기포 구조가 장거리 항공 운송이나 라스트 마일 배송에서 예측 가능한 단열성과 완충성을 제공하기 때문입니다. Cold Chain Technologies와 같은 제조업체들은 네덜란드 브레다에 유럽 시장용 생산 능력을 확충했습니다. 이는 자동차로 6시간 이내 거리에 EU GDP의 80%를 차지하는 주요 도시들을 아우르는 제약 물류 경로를 특별히 지원하기 위함입니다. 유럽 약전 부록 11.7에 따른 규제 강화로 인해 포장 공급업체들은 추출물 및 용출물에 대한 검증을 수행해야 하는 상황에 놓여 있으며, 규정 준수 실적이 입증된 기존 EPS 배합이 선호되고 있습니다. 이 콜드체인 분야의 비즈니스 기회는 높은 이익률을 가져다주며, 일반 건설용 발포재 분야의 스티렌 가격 스프레드 변동을 부분적으로 상쇄하고 있습니다.
원자재 비용 변동이 이익률을 압박
스티렌은 EPS 현금 원가의 최대 70%를 차지하고 있어, 벤젠이나 나프타의 가격 변동에 따라 수익성이 좌우되기 쉬운 상황입니다. Trinseo가 2025년 1월 계약 가격을 톤당 55유로 인상한다고 발표한 것은 생산자들이 이익률을 지키려 하고 있음을 보여줍니다. 2025년 4월 Versalis가 브린디시의 크래커를 폐쇄함에 따라 공급 부족이 더욱 심화되고, 해당 지역의 수입 의존도가 높아지는 한편, 운송비와 환율 리스크도 증가하고 있습니다. 변동이 심한 원자재 비용과 고정 가격의 건설 계약 간의 불일치로 인해 가공업체의 현금 흐름이 압박받고 있으며, 이는 북서유럽 전역의 소규모 공장들에게 과제가 되고 있습니다.
부문별 분석
유럽의 발포 폴리스티렌(EPS) 시장에서 화이트 등급 시장 규모는 총 소비량의 70.86%를 차지했습니다. 화이트 EPS는 여전히 비용이 중요한 선정 기준이며, 건축 기준을 준수하기 위해 두께가 그리 두껍지 않은 패널로 충분한 경우, 중공 벽, 지반 직접 시공 슬래브 및 주변 배수 보드에 계속해서 사용되고 있습니다. 한편, 그레이 및 실버 등급은 2031년까지 연평균 성장률(CAGR) 3.74%라는 가장 높은 성장률을 보이고 있습니다. 이는 흑연의 적외선 반사 입자로 인해 λ값이 약 0.030 W/(m·K)까지 낮아지기 때문입니다. 외단열 복합 시스템에서 그레이 EPS는 동일한 U값을 유지하면서 층 두께를 16cm에서 12cm로 줄일 수 있으므로, 부지 경계가 좁은 도시 지역의 파사드 개보수를 가능하게 합니다. BEWI의 CIRCULUM 시리즈는 뛰어난 성능과 재생 비드 배합을 모두 갖추고 있어, 건축가가 에너지 효율과 순환형 경제 목표를 동시에 달성하는 데 도움이 됩니다. 각 제조업체는 인라인 발포제 회수 및 연속 블록 성형에 투자하고, 기계적 특성을 저해하지 않으면서 더 많은 재생 재료를 배합함으로써, 유럽의 발포 폴리스티렌 시장에서 그레이 EPS를 기술적·환경적 측면에서 우수한 선택지로 자리매김하고 있습니다.
기타 혜택 :
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모 및 성장 예측
제6장 경쟁 구도
제7장 시장 기회 및 향후 전망
AJY 26.09.09According to Mordor Intelligence, the Europe expanded polystyrene market size was valued at 2.20 million tons in 2025 and estimated to grow from 2.27 million tons in 2026 to reach 2.67 million tons by 2031, at a CAGR of 3.32% during the forecast period (2026-2031).
This report is Segmented by Product Type (White EPS, Gray and Silver EPS), End-User Industry (Building and Construction, Electrical and Electronics, Packaging, Other End-User Industries), and Geography (Germany, United Kingdom, France, Italy, Spain, Norway, Sweden, Denmark, Finland, Rest of Europe). The Market Forecasts are Provided in Terms of Volume (Tons).
Europe Expanded Polystyrene (EPS) Market Trends and Insights
Building Energy Codes Drive Thermal Performance Requirements
Stricter national and EU-wide energy codes compel developers to design walls, roofs, and floors with lower U-values, lifting insulation thickness requirements and supporting steady volume demand for Europe's Expanded Polystyrene market solutions. Germany's Gebaudeenergiegesetz already specifies exterior wall U-values near 0.20 W/(m2K), which typically necessitates 12-16 cm of EPS, cementing roughly 40% share for the foam in German facade systems despite height-based fire-safety limits. France and the Nordics extend similar performance stipulations, and the 2024 recast of the Energy Performance of Buildings Directive sets a net-zero mandate for new structures from 2030, locking in long-range insulation demand. Retrofit volumes also rise under the EU Renovation Wave, with grants steering homeowners toward thermally efficient yet affordable systems. Producers broaden their Neopor and graphite-enriched lines in this compliance-driven landscape to deliver superior R-values without costly structural modifications.
mRNA Biologics Cold Chain Expansion
Rapid commercialization of mRNA vaccines and advanced therapeutics requires 2 °C-to-8 °C stability from factory to clinic. EPS shippers dominate this lane because the material's closed-cell matrix provides predictable insulation and cushioning over long-haul flights and last-mile parcels. Manufacturers such as Cold Chain Technologies have added European capacity in Breda, Netherlands, specifically to serve pharma corridors reaching 80% of EU GDP centers within a six-hour drive. Regulatory tightening under European Pharmacopoeia Supplement 11.7 pushes packaging suppliers to validate extractables and leachables, favoring incumbent EPS formulations with proven compliance records. The cold-chain opportunity carries premium margins that partially offset styrene spread volatility in commodity construction foam.
Feedstock Cost Volatility Pressures Margins
Styrene accounts for up to 70% of EPS cash costs, making profitability sensitive to benzene-and naphtha swings. January 2025 contract hikes of EUR 55 per ton announced by Trinseo illustrate producer attempts to defend margins. Structural tightness deepens as Versalis shutters its Brindisi cracker in April 2025, widening the region's import dependency and magnifying freight and currency risks. The mismatch between volatile raw-material outlays and fixed-price construction contracts squeezes converter cash flows, challenging smaller plants across Northwest Europe.
Other drivers and restraints analyzed in the detailed report include:
- Appliance Manufacturing Reshoring Momentum
- EU Renovation Wave Accelerates Gray EPS Adoption
- Sustainable Alternatives Gain Market Traction
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Europe's Expanded Polystyrene market size for white grades accounted for 70.86% share of overall consumption. White EPS persists in cavity walls, slab-on-grade floors, and perimeter drainage boards where cost remains the critical selector and modest panel thicknesses suffice for code compliance. However, gray and silver grades register the fastest 3.74% CAGR to 2031 as graphite's infrared-reflective particles lower λ-values to around 0.030 W/(m*K). In external thermal insulation composite systems, gray EPS reduces layer thickness from 16 cm to 12 cm for the same U-value, unlocking facade renovation in urban districts with tight lot lines. BEWI's CIRCULUM line couples the performance edge with recycled bead content, helping architects reconcile energy and circularity targets. Producers invest in in-line blowing-agent recovery and continuous block molding to embed more reclaim without sacrificing mechanical properties, positioning gray EPS as a technical and eco-credential upgrade within the Europe Expanded Polystyrene market.
Complete Report Scope:
- By Product Type
- White EPS
- Gray and Silver EPS
- By End-user Industry
- Building and Construction
- Electrical and Electronics
- Packaging
- Other End-user Industries (Agriculture and Automotive)
- By Geography
- Germany
- United Kingdom
- France
- Italy
- Spain
- Norway
- Sweden
- Denmark
- Finland
- Rest of Europe
List of Companies Covered in this Report:
- Alpek SAB de CV
- Austrotherm
- BASF
- BEWi
- Epsilyte LLC
- Ineos
- Kaneka Corporation
- Ravago
- SABIC
- SIBUR International GmbH
- Sunde Group
- Sunpor
- Synthos
- TotalEnergies
- Versalis S.p.A.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Building-energy codes mandating higher R-values from 2025
- 4.2.2 Mandatory cold-chain capacity additions for mRNA-class biologics
- 4.2.3 Re-shoring of appliance production boosting domestic protective packaging
- 4.2.4 Grey-EPS adoption in EU "Renovation Wave" retrofit projects
- 4.2.5 Low-cost modular housing programmes
- 4.3 Market Restraints
- 4.3.1 Styrene monomer price volatility tracking crude-oil spreads
- 4.3.2 Commercialisation of mycelium and moulded-pulp substitutes
- 4.3.3 Carbon-pricing schemes inflating Scope-3 footprints of petro-polymers
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Import-Export Trends
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Product Type
- 5.1.1 White EPS
- 5.1.2 Gray and Silver EPS
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Electrical and Electronics
- 5.2.3 Packaging
- 5.2.4 Other End-user Industries (Agriculture and Automotive)
- 5.3 By Geography
- 5.3.1 Germany
- 5.3.2 United Kingdom
- 5.3.3 France
- 5.3.4 Italy
- 5.3.5 Spain
- 5.3.6 Norway
- 5.3.7 Sweden
- 5.3.8 Denmark
- 5.3.9 Finland
- 5.3.10 Rest of Europe
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Alpek SAB de CV
- 6.4.2 Austrotherm
- 6.4.3 BASF
- 6.4.4 BEWi
- 6.4.5 Epsilyte LLC
- 6.4.6 Ineos
- 6.4.7 Kaneka Corporation
- 6.4.8 Ravago
- 6.4.9 SABIC
- 6.4.10 SIBUR International GmbH
- 6.4.11 Sunde Group
- 6.4.12 Sunpor
- 6.4.13 Synthos
- 6.4.14 TotalEnergies
- 6.4.15 Versalis S.p.A.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment