|
시장보고서
상품코드
2121977
모듈형 실험실 자동화 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Modular Laboratory Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
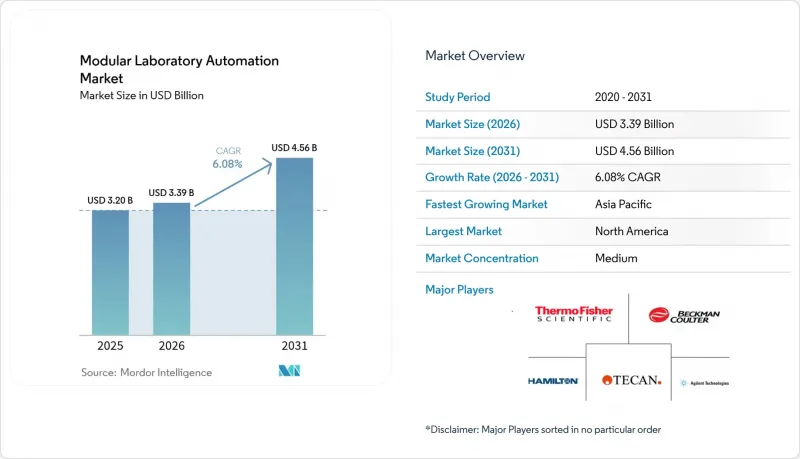
에 따르면 모듈형 실험실 자동화 시장 규모는 2025년에 32억 달러로 평가되며, 2026년 33억 9,000만 달러에서 2031년까지 45억 6,000만 달러에 달할 것으로 예측되고 있으며, 예측 기간(2026-2031년)에 CAGR은 6.08%에 달할 전망입니다.
이 보고서는 장비 및 소프트웨어(자동 액체 핸들러, 자동 플레이트 핸들러 등), 응용 분야(신약 개발, 유전체학 등), 최종사용자(제약 회사 및 생명공학 기업 등), 자동화 유형(독립형 장비 자동화, 모듈형 워크셀 등), 그리고 지역별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
글로벌 모듈형 실험실 자동화 시장의 동향 및 인사이트
재현성 및 데이터 무결성에 대한 요구 증가
자동화 플랫폼은 엄격한 공정 관리를 적용하여 수동 방식에서 흔히 발생하는 편차를 줄입니다. 메이요 클리닉의 분류 시스템은 시간당 6,000개의 시험관을 오분류 없이 처리하여 결함 제로의 데이터 수집을 실현하고 있습니다. 규제 당국이 모든 분석에 대해 상세한 감사 추적을 요구하고 있으므로 이러한 결과는 필수적입니다. 여러 시설로 구성된 컨소시엄에서는 표준화된 로봇 워크플로우를 사용하여 결과를 확실하게 비교하고, 공동 연구를 촉진하고 있습니다. 각 벤더들은 원시 데이터를 보호하기 위해 블록체인 기반 로그를 통합하는 사례가 늘고 있습니다. 이러한 기능을 통해 규제 당국에 증거를 제출할 때 실험실의 신뢰성이 향상됩니다.
생명과학 연구소의 만성적인 숙련된 인력 부족
북미 전역에서 2만 5,000건에 달하는 인력 부족으로 인해 연구소들은 반복적인 작업을 기계에 맡기고 과학자들이 결과 해석에 전념할 수 있도록 자동화를 추진하고 있습니다. Clarapath사의 로봇 마이크로토미 시스템을 통해 한 명의 기술자가 여러 슬라이드 제작 스테이션을 감독할 수 있게 되어 생산 능력이 3배로 증가합니다. 이러한 노동 효율 향상 덕분에 검사 지체가 해소되고, 초과근무 수당을 지급하지 않고도 연중무휴 24시간 운영이 가능해집니다. 또한 자동화를 통해 프로토콜을 소프트웨어에 통합함으로써 암묵적 지식이 체계화되어 신입 사원의 교육 기간이 단축됩니다. 이직률이 상승하는 가운데, 모듈형 검사실 자동화 시장에 대한 투자에 대한 경제적 타당성은 더욱 높아지고 있습니다.
높은 초기 설비 투자(Capex)와 장기화된 ROI 주기
엔트리 레벨 로봇 벤치는 10만-30만 달러, 풀 라인의 경우 100만 달러를 초과하므로 학술기관이나 중규모 기관의 예산을 압박하고 있습니다. 오류 없는 데이터나 직원 재배치와 같은 이점은 단순한 금전적 평가가 어렵기 때문에 투자 회수에는 3년 이상 걸리는 경우가 많습니다. 리스 제도나 사용량에 따른 요금 체계로 진입 장벽은 일부 낮아지지만, 유지보수 계약, 검증, 운영자 교육 등으로 인해 총 소유 비용은 여전히 높습니다. 따라서 재무위원회는 투자를 단계적으로 시행하고, 시설이 단계적으로 역량을 확장할 수 있는 모듈형 검사실 자동화 시장 접근 방식을 우선시하고 있습니다.
부문 분석
2025년, 자동 액체 핸들러는 모듈형 실험실 자동화 시장 규모의 25.83%를 차지하며, 분석 준비의 기반으로서의 입지를 공고히 했습니다. 실험실에서 이러한 플랫폼을 선호하는 이유는 고정밀 피펫팅이 후공정 데이터 품질을 보장하는 동시에 직원이 분석 업무에 전념할 수 있게 해주기 때문입니다. 데크 레이아웃을 최적화하고 칩 소비량을 예측하는 통합 소프트웨어에 대한 수요가 증가하고 있으며, 이를 통해 소모품 낭비와 예기치 않은 가동 중단 시간이 줄어들고 있습니다. 연평균 성장률(CAGR) 6.94%로 성장할 것으로 예상되는 자동 보관·이송 시스템은 시료를 적시에 작업 셀에 공급함으로써, 시료 보관이라는 오랜 과제를 해결합니다. 현재 각 벤더사는 저온 창고와 AI 기반 경로 계획 기능을 결합하여 동결·해동 횟수를 최소화하고, 생체 분자의 무결성을 보호하고 있습니다.
각 벤더사가 분석 실패가 확대되기 전에 이상을 감지하는 기계학습 알고리즘을 통합함으로써, 소프트웨어 혁신이 경쟁상의 차별화 요소가 되고 있습니다. Thermo Fisher사의 ‘Vulcan’ 플랫폼은 로봇 암과 자동 조정형 워크플로우를 결합하여 처리 능력을 어떻게 향상시킬 수 있는지 보여주고 있습니다. 인라인 질량분석 및 형광 검출이 가능한 분석 장치는 총 소요 시간을 단축하여, 연구소에서 며칠이 걸리던 프로토콜을 1교대 근무 시간 내에 완료할 수 있게 해줍니다. 그 결과, 단일 용도의 장비가 아닌 통합된 생태계에 대한 수요가 구조적으로 증가하고 있으며, 공급업체들은 하드웨어와 데이터를 단일 화면에서 통합 관리하는 모듈형 실험실 자동화 시장의 생태계에 주력하고 있습니다.
임상 진단 분야는 2025년에 매출의 28.12%를 차지하며, 그 배경에는 대량 처리가 요구되는 화학 검사 및 재현성이 높은 자동화를 평가하는 엄격한 인증 기준이 있습니다. 병원 검사실에서는 컨베이어로 연결된 워크셀을 미들웨어와 통합하고, 검증된 결과를 전자 차트에 직접 전송함으로써 환자 치료 주기를 단축하고 있습니다. 연평균 성장률(CAGR) 9.21%로 예측되는 세포·유전자 치료 워크플로우에는 장기간의 배양 기간 중 오염 위험을 최소화하는 폐쇄형 시스템 로봇이 필요합니다. 환경 센서와 AI 분류기를 탑재한 로봇은 서브미크론 수준의 청정도를 유지하여 수백만 달러의 손실로 이어질 수 있는 배치 실패를 방지합니다.
신약 개발 그룹은 1,536웰 플레이트를 이용한 고처리량 스크리닝을 지속적으로 도입하고 있는 반면, 유전체학 컨소시엄은 집단 코호트를 위한 라이브러리 조제를 자동화하고 있습니다. 단백질체학 분야에서는 실험실내 시료의 분해 처리 및 LC-MS 주입이 점차 자동화되고 있습니다. 시약에 의존하지 않는 프로토콜을 지원하는 학제간 플랫폼이 주목을 받고 있으며, 이를 통해 각 시설은 진단, 신약 개발, 제조의 각 워크로드 간에 처리 능력을 유연하게 전환할 수 있게 됩니다. 이러한 범용성 덕분에 단일 설비 투자로 여러 수입원을 창출할 수 있으며, 모듈형 실험실 자동화 시장에 대한 투자가 촉진되고 있습니다.
지역별 분석
북미는 2025년에 41.15%의 매출 점유율을 유지했습니다. 이는 바이오의약품 기업의 본사가 집중되어 있다는 점, NIH의 풍부한 자금 지원, 그리고 기술 투자를 지원하는 성숙한 규제 환경을 반영한 것입니다. 215만 달러 규모의 MATChS 보조금 등 최근 연방 정부의 보조금은 지능형 자동화에 대한 공공 부문의 지지를 지원하고 있습니다. Tier 1 병원에서는 분산형 워크셀을 도입하여 검체 처리를 환자 접수 현장에 가깝게 함으로써 물류 지연을 줄이고 있습니다. 캐나다의 생명과학 클러스터에서는 주 정부의 세액 공제를 활용하여 연구 인프라 업그레이드를 추진하고 있으나, 인력 부족은 여전히 심각한 문제입니다. 이에 따라 인력이 제한된 상황에서도 처리 능력을 유지하기 위한 현실적인 수단으로 자동화가 주목받고 있습니다. 멕시코는 무균 주사제 수출 인증 획득을 목표로, Annex 1 요건을 충족하고 수탁제조 계약을 확보하기 위해 로봇식 아이솔레이터의 시범 운영을 진행하고 있습니다.
아시아태평양은 각국 정부가 생명공학 인프라에 보조금을 지원하고, 첨단 치료법의 현지 생산을 장려하고 있으며, 가장 높은 성장 궤도를 그리고 있습니다. 중국은 완전 자동화된 폐쇄형 파이프라인을 채택한 국가 시퀀싱 허브에 투자하여 게놈당 비용을 절감하고 정밀 의료 시범 프로그램을 가속화하고 있습니다. 일본에서는 고령화에 따라 만성질환 패널을 처리할 수 있는 진단 자동화에 대한 수요가 증가하고 있습니다. 인도의 수탁제조 부문에서는 국제 무균 기준을 준수하는 모듈형 아이솔레이터를 도입하여, 국내 공장이 규제 시장으로의 수출에 대응할 수 있는 체제를 갖추고 있습니다. 한국은 듀얼 암 로봇과 AI 분석을 결합한 세포 치료 우수 센터에 주력하고 있으며, 복잡한 바이오의약품을 보다 신속하게 시장에 출시하고 있습니다. 이러한 노력들이 어우러져 해당 지역 전체의 모듈형 검사실 자동화 시장에서 지속적인 수요를 지원하고 있습니다.
유럽은 여전히 매우 중요한 시장이며, 부속서 1(Annex 1)이 로봇 기술 도입을 장려하는 방식으로 기술적 장벽을 철폐함에 따라 기존 충전 및 포장 라인의 업그레이드가 진행되고 있습니다. 독일의 엔지니어링 기반에는 고정밀 메카트로닉스와 클라우드 네이티브 MES 플랫폼이 통합되어 있는 반면, 영국에서는 AI 주도형 워크셀을 검증하는 대학 및 병원 간 파트너십에 연구 자금이 투입되고 있습니다. 프랑스에서는 초기 설비 투자를 보전해 주는 경제 부양책을 통해 공공 부문 실험실의 현대화가 추진되고 있습니다. 이탈리아와 스페인에서는 수혈 오류를 억제하기 위해 혈액은행 운영에 있으며, 실험실의 완전 자동화를 우선시하고 있습니다. 유럽경제지역(EEA) 전반에 걸친 규제 공통성은 국경을 초월한 표준화를 촉진하고 있으며, 이를 통해 공급업체는 통합된 검증 패키지를 제공할 수 있게 되어 모듈형 실험실 자동화 시장에서 여러 거점에 걸친 조달을 신속화하고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.04According to Mordor Intelligence, the modular laboratory automation market size was valued at USD 3.2 billion in 2025 and estimated to grow from USD 3.39 billion in 2026 to reach USD 4.56 billion by 2031, at a CAGR of 6.08% during the forecast period (2026-2031).
This report is Segmented by Equipment and Software (Automated Liquid Handlers, Automated Plate Handlers and More), Field of Application (Drug Discovery, Genomics and More), End User (Pharmaceutical and Biotech Companies, and More), Automation Type (Standalone Instrument Automation, Modular Workcells and More) and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Modular Laboratory Automation Market Trends and Insights
Rising Need for Reproducibility & Data Integrity
Automated platforms impose strict process control, cutting variability that manual techniques often introduce. The Mayo Clinic's sorting system moves 6,000 tubes per hour without mis-sorts, demonstrating zero-defect data capture. Such results are indispensable as regulators demand granular audit trails for every assay. Multi-site consortia use standardized robotic workflows to compare results confidently, boosting collaborative studies. Vendors increasingly embed blockchain-ready logs to safeguard raw data. These capabilities elevate laboratory credibility when submitting evidence to regulatory agencies.
Chronic Skilled-Labor Shortages in Life-Science Labs
Vacancies nearing 25,000 positions across North America have pushed labs toward automation that reassigns repetitive tasks to machines while scientists focus on interpretation. Clarapath's robotic microtomy lets one technician oversee multiple slide-prep stations, tripling output capacity. Such labour-multiplying benefits shorten testing backlogs and support 24/7 operations without overtime premiums. Automation also institutionalizes tacit knowledge by encoding protocols into software, reducing onboarding time for new hires. With retirement rates climbing, the economic rationale for modular laboratory automation market investments strengthens further.
High Upfront Capex & Long ROI Cycles
Entry-level robotic benches cost USD 100,000-300,000, while full lines exceed USD 1 million, straining academic and midsize budgets. Payback often stretches past three years because benefits like error-free data or staff redeployment resist simple monetization. Leasing schemes and usage-based pricing partially lower the barrier, yet maintenance contracts, validation, and operator training still elevate total cost of ownership. Finance committees therefore stage investments in phases, favouring the modular laboratory automation market approach that lets sites bolt on capacity incrementally.
Other drivers and restraints analyzed in the detailed report include:
- High-Throughput Genomics & Cell-Therapy Pipelines
- EU GMP Annex 1 Contamination-Control Mandates
- Integration Complexity with Legacy Instruments & LIMS
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Automated liquid handlers generated 25.83% of the modular laboratory automation market size in 2025, cementing their role as the backbone of assay preparation. Laboratories favour these platforms because precision pipetting ensures downstream data quality while freeing staff for analytical tasks. Demand for integrated software that optimizes deck layouts and predicts tip consumption is growing, reducing consumable waste and unplanned downtime. Automated storage & retrieval systems, projected to grow at 6.94% CAGR, solve the chronic challenge of sample archiving by delivering samples to work cells just-in-time. Vendors now combine low-temperature warehouses with AI route planning, minimizing freeze-thaw events and safeguarding biomolecule integrity.
Software innovation shapes competitive differentiation as vendors embed machine-learning algorithms that flag anomalies before assay failures propagate. Thermo Fisher's Vulcan platform illustrates how combining robotic arms with self-tuning workflows elevates throughput. Analysers capable of inline mass spectrometry or fluorescence detection compress total turnaround time, letting labs condense multi-day protocols into single shifts. The net effect is a structural rise in demand for cohesive ecosystems rather than single-purpose boxes, reinforcing supplier emphasis on modular laboratory automation market ecosystems that orchestrate hardware and data in one pane of glass.
Clinical diagnostics contributed 28.12% revenue in 2025, underpinned by high-volume chemistries and strict accreditation criteria that reward reproducible automation. Hospital laboratories integrate conveyor-linked work cells with middleware that posts verified results directly to electronic health records, shortening patient care cycles. Cell & gene therapy workflows, forecast for 9.21% CAGR, need closed-system robots that minimize contamination risk during lengthy culture periods. Robots equipped with environmental sensors and AI classifiers maintain sub-micron cleanliness, preventing batch failures that could cost millions of USD.
Drug-discovery groups continue to deploy high-throughput screens on 1,536-well plates, while genomics consortia automate library prep for population cohorts. Proteomics is emerging as laboratories automate sample digestion and LC-MS loading. Cross-disciplinary platforms that support reagent-agnostic protocols are gaining traction, as they let sites pivot capacity between diagnostic, discovery, and manufacturing workloads. This versatility reinforces investment in the modular laboratory automation market because a single capital outlay serves many revenue streams.
Complete Report Scope:
- By Equipment and Software
- Automated Liquid Handlers
- Automated Plate Handlers
- Robotic Arms
- Automated Storage and Retrieval Systems (ASRS)
- Analyzers
- Software
- By Field of Application
- Drug Discovery
- Genomics
- Proteomics
- Clinical Diagnostics
- Other Applications
- By End User
- Pharmaceutical and Biotech Companies
- Academic and Research Institutes
- Clinical and Diagnostic Laboratories
- Contract Research Organisations
- Food and Environmental Testing Labs
- By Automation Type
- Standalone Instrument Automation
- Modular Workcells
- Integrated Workcells
- Total Laboratory Automation (TLA) Lines
- Mobile/Cloud-connected Robots
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
North America sustained a 41.15% revenue share in 2025, reflecting the concentration of biopharmaceutical headquarters, generous NIH funding, and a mature regulatory environment that favours technology investments. Recent federal grants, such as the USD 2.15 million MATChS award, confirm public-sector endorsement of intelligent automation. Tier-1 hospitals are integrating decentralized work cells, pushing specimen processing closer to patient intake to reduce logistics delays. Canada's life-science clusters leverage provincial tax credits to upgrade research infrastructure, though staffing shortages remain acute; automation therefore offers a pragmatic path to maintain throughput despite limited headcount. Mexico, seeking export accreditation for sterile injectables, is piloting robotic isolators to meet Annex 1 requirements and secure contract manufacturing deals.
Asia-Pacific registers the highest growth trajectory as governments subsidize biotech infrastructure and encourage local manufacturing of advanced therapies. China invests in national sequencing hubs that adopt fully automated, closed-loop pipelines, reducing per-genome costs and accelerating precision-medicine pilot programs. Japan's aging population elevates demand for diagnostic automation capable of handling chronic-disease panels. India's contract-manufacturing sector implements modular isolators that comply with global sterility standards, positioning domestic plants for regulated-market exports. South Korea focuses on cell-therapy centers of excellence that combine dual-arm robots with AI analytics, bringing complex biologics to market more swiftly. Collectively, these initiatives underpin sustained demand across the modular laboratory automation market throughout the region.
Europe remains a pivotal market because Annex 1 lifts technical barriers in favour of robotics, driving upgrades across legacy fill-finish lines. Germany's engineering base integrates high-precision mechatronics with cloud-native MES platforms, while the United Kingdom channels research funding into university-hospital partnerships that validate AI-directed work cells. France modernizes public-sector laboratories through stimulus packages that offset upfront capex. Italy and Spain prioritize total laboratory automation in blood-bank operations to curb transfusion errors. The regulatory commonality across the European Economic Area encourages cross-border standardization, letting suppliers offer uniform validation packages and thereby expedite procurement across multiple sites within the modular laboratory automation market.
List of Companies Covered in this Report:
- Thermo Fisher Scientific
- Danaher Corporation (Beckman Coulter)
- Tecan Group AG
- Agilent Technologies
- PerkinElmer Inc.
- Siemens Healthineers
- Becton Dickinson (BD)
- Hudson Robotics Inc.
- Honeywell International Inc.
- Hamilton Company
- HighRes Biosolutions
- Biosero Inc.
- QIAGEN N.V.
- Copan Diagnostics
- Retisoft Inc.
- Bruker (Chemspeed)
- Roche Diagnostics
- ABB Ltd.
- LabVantage Solutions
- Festo AG and Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising need for reproducibility and data integrity
- 4.2.2 Chronic skilled-labor shortages in life-science labs
- 4.2.3 High-throughput genomics and cell-therapy pipelines
- 4.2.4 EU GMP Annex 1 contamination-control mandates accelerating robotics (under-reported)
- 4.3 Market Restraints
- 4.3.1 High upfront capex and long ROI cycles
- 4.3.2 Integration complexity with legacy instruments and LIMS
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Equipment and Software
- 5.1.1 Automated Liquid Handlers
- 5.1.2 Automated Plate Handlers
- 5.1.3 Robotic Arms
- 5.1.4 Automated Storage and Retrieval Systems (ASRS)
- 5.1.5 Analyzers
- 5.1.6 Software
- 5.2 By Field of Application
- 5.2.1 Drug Discovery
- 5.2.2 Genomics
- 5.2.3 Proteomics
- 5.2.4 Clinical Diagnostics
- 5.2.5 Other Applications
- 5.3 By End User
- 5.3.1 Pharmaceutical and Biotech Companies
- 5.3.2 Academic and Research Institutes
- 5.3.3 Clinical and Diagnostic Laboratories
- 5.3.4 Contract Research Organisations
- 5.3.5 Food and Environmental Testing Labs
- 5.4 By Automation Type
- 5.4.1 Standalone Instrument Automation
- 5.4.2 Modular Workcells
- 5.4.3 Integrated Workcells
- 5.4.4 Total Laboratory Automation (TLA) Lines
- 5.4.5 Mobile/Cloud-connected Robots
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle East
- 5.5.5.1 Israel
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 United Arab Emirates
- 5.5.5.4 Turkey
- 5.5.5.5 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Thermo Fisher Scientific
- 6.4.2 Danaher Corporation (Beckman Coulter)
- 6.4.3 Tecan Group AG
- 6.4.4 Agilent Technologies
- 6.4.5 PerkinElmer Inc.
- 6.4.6 Siemens Healthineers
- 6.4.7 Becton Dickinson (BD)
- 6.4.8 Hudson Robotics Inc.
- 6.4.9 Honeywell International Inc.
- 6.4.10 Hamilton Company
- 6.4.11 HighRes Biosolutions
- 6.4.12 Biosero Inc.
- 6.4.13 QIAGEN N.V.
- 6.4.14 Copan Diagnostics
- 6.4.15 Retisoft Inc.
- 6.4.16 Bruker (Chemspeed)
- 6.4.17 Roche Diagnostics
- 6.4.18 ABB Ltd.
- 6.4.19 LabVantage Solutions
- 6.4.20 Festo AG and Co. KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment