|
시장보고서
상품코드
2122008
스페인의 미용 기기 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Spain Aesthetic Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
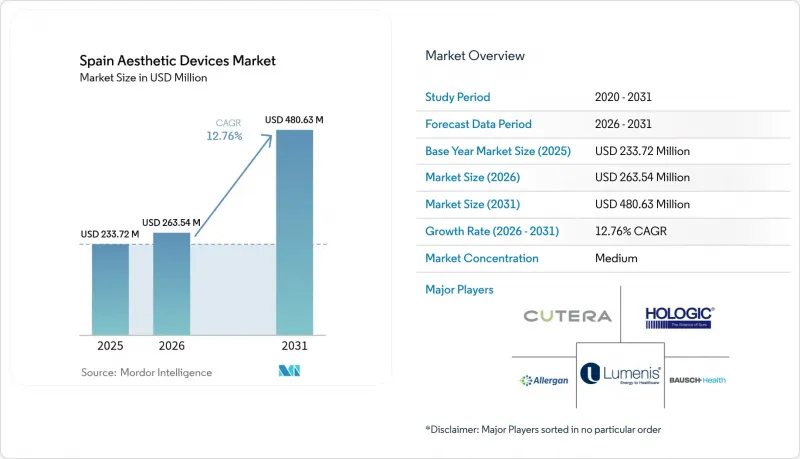
에 의하면, 스페인의 미용 기기 시장 규모는 2025년에 2억 3,372만 달러로 평가되었고, 2026년 2억 6,354만 달러에서 2031년까지 4억 8,063만 달러에 이를 것으로 예측되며, 예측 기간(2026-2031년) CAGR은 12.76%를 기록할 전망입니다.
본 보고서는 기기 유형(에너지 방식 기기, 비에너지 방식 기기), 용도(피부 재생·탄력 강화, 바디 컨투어링·셀룰라이트 완화, 제모, 문신·색소 침착 제거, 가슴 확대, 여드름·흉터 치료, 기타 용도), 최종 사용자(병원 등)별로 분류되어 있습니다. 시장 예측은 금액(달러) 기준으로 제시되어 있습니다.
스페인의 미용 기기 시장 동향 및 인사이트
고령화와 젊어 보이는 외모에 대한 수요
스페인의 연령 중앙값은 서서히 계속 상승하고 있지만, 동시에 미용에 대한 의식도 높아지고 있어 45-65세 연령층을 비수술적 탄력 개선 및 피부 재생 옵션으로 이끌고 있습니다. 시각화 기능을 갖춘 마이크로 포커스 초음파 등, 콜라겐을 자극하는 에너지 기반 치료법은 눈에 띄면서도 과하지 않은 결과를 제공함으로써 이러한 요구를 충족시키고 있습니다. 또한, 시술 전 정밀한 평가를 가능하게 하는 3D 피부 매핑 시스템이 이러한 시술의 보급을 뒷받침하고 있으며, 마드리드와 바르셀로나의 품질을 중시하는 소비자들로부터 지지를 얻고 있습니다. 병원 및 대형 클리닉 그룹은 이러한 시술을 ‘교정’이 아닌 ‘예방’으로 포지셔닝하며, 환자와의 장기적인 관계를 지속적으로 구축하고 있습니다. 인구 동향의 추세가 지속되는 한, 스페인의 미용 기기 시장 수요 최저치도 유지될 것입니다.
미용 시술 분야의 의료 관광 부상
스페인이 왕령 제81/2014호를 통해 EU의 국경 간 의료 지침에 가입함에 따라, EU 지역 내 환자에 대한 의료비 환급이 원활해졌으며, 스페인은 선택적 미용 시술을 받기 위한 합리적인 목적지가 되었습니다. 2024년 9월에 시행된, 미용 성형 수술을 인증받은 성형외과 전문의에게만 허용하는 규정은 엄격한 안전 감독이 이루어지고 있음을 보여줌으로써 역설적으로 스페인의 브랜드 이미지를 향상시켰습니다. 발렌시아와 말라가 지역의 클리닉에서는 현재 HIFU를 이용한 바디 컨투어링 패키지에 숙박 시설을 세트로 제공하며, 해안 지역의 매력을 외국인 관광객들에게 어필하고 있습니다. 환자들의 높은 만족도 평가가 온라인 입소문을 낳으며 선순환을 만들어내고 있습니다. 이에 따라 스페인 미용 의료기기 시장 전체에서 시술 건수가 증가하고, 기기 교체 수요도 높아지고 있습니다.
미용 시술에 대한 보험 적용 범위 제한
공적 보험에서는 선택적 미용 시술이 적용 대상에서 제외되어 있어, 환자는 고액의 치료비를 본인 부담으로 지불할 수밖에 없습니다. 미용 관련 청구에 대한 재판 외 합의 평균액은 3만 3,000유로를 초과하고 있어, 이와 관련된 금전적 리스크가 크다는 것을 알 수 있습니다. 기기의 감가상각비가 시술 요금에 가산되어 있기 때문에 클리닉은 수익성을 유지하기 위해 가동률을 높게 유지해야 하며, 그 결과 중산층에게 경제적 장벽이 높아지고 있습니다. 법 제29/2006호에 근거한 법적 체계에서는 안전성과 유효성에 대한 엄격한 증명이 의무화되어 있으며, 이로 인해 제조업체의 규정 준수 비용이 상승하고, 이 또한 소비자에게 전가되고 있습니다. 소비자용 광치료 마스크나 휴대용 RF 기기가 점차 보급되고 있지만, 주요 도시 외 지역에 거주하는 많은 스페인인들에게 전문용 기기는 여전히 손에 닿지 않는 존재입니다.
부문 분석
2025년, 스페인의 미용 기기 시장에서 에너지 기반 기기가 59.02%의 점유율을 차지했습니다. 이는 레이저, 고주파, 초음파 플랫폼이 다양한 적응증에 걸쳐 범용성을 발휘했기 때문입니다. 초음파 기반 시스템은 2031년까지 연평균 성장률(CAGR) 15.62%를 나타낼 것으로 예측됩니다. 이는 고강도 집속 초음파(HIFU) 시술이 남성형 탈모 치료로서 유효성이 확인된 두피 회춘 프로토콜로까지 확대되고 있는 것이 원동력이 되고 있습니다.
각 레이저 제조업체들은 색소 침착 합병증 없이 지속적인 여드름 개선을 실현하는 실시간 열화상 기능을 갖춘 1726nm 기기를 시장에 출시하고 있습니다. 온도 제어 기능을 갖춘 RF 마이크로니들링 플랫폼은 임상시험에서 86.7%의 환자 만족도를 기록했으며, 레이저 기술이 발전하더라도 고주파(RF)의 중요성은 여전히 유지되고 있습니다. 필러와 같은 비에너지 대체 요법은 유변학적 특성의 개선과 AEMPS의 감독 강화로 시장 점유율을 유지하고 있는 반면, 케미컬 필링은 비용 대비 효과가 높은 보조 요법으로서 틈새 시장에서 부활하고 있습니다. 마이크로니들 롤러는 현재 Class IIa 규제 대상이며, 이에 따라 클리닉에서는 보다 안전한 카트리지식 시스템의 도입이 확대되고 있습니다. 이러한 동향을 종합해 볼 때, 스페인의 미용 기기 시장에서는 에너지 기반 플랫폼이 계속해서 주류를 이루는 한편, 보조 요법 분야에서의 목표 지향적인 혁신의 여지도 남을 것으로 확실시됩니다.
기타 혜택:
- 엑셀 형식 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 주요 요약
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
LSH 26.09.10According to Mordor Intelligence, the Spain aesthetic devices market size was valued at USD 233.72 million in 2025 and estimated to grow from USD 263.54 million in 2026 to reach USD 480.63 million by 2031, at a CAGR of 12.76% during the forecast period (2026-2031).
This report is Segmented by Device Type (Energy-Based Devices, Non-Energy-Based Devices), Application (Skin Resurfacing & Tightening, Body Contouring & Cellulite Reduction, Hair Removal, Tattoo & Pigmentation Removal, Breast Augmentation, Acne & Scar Treatment, Other Applications), End User (Hospitals, and More). The Market Forecasts are Provided in Terms of Value (USD).
Spain Aesthetic Devices Market Trends and Insights
Aging Population & Youthful-Appearance Demand
Spain's median age continues to inch upward, yet cosmetic consciousness is rising in parallel, pushing the 45-65 cohort toward non-surgical tightening and resurfacing options. Energy-based modalities that stimulate collagen, such as micro-focused ultrasound with visualization, fit this preference by delivering visible yet discreet results. Uptake is further reinforced by 3D skin-mapping systems that provide precise pre-treatment assessments, a feature embraced by quality-oriented consumers in Madrid and Barcelona. Hospitals and large clinic groups continue to market these procedures as preventive rather than corrective, lengthening patient lifecycles. As demographic momentum endures, so does the baseline demand floor for the Spain aesthetic devices market.
Rising Medical Tourism in Cosmetic Procedures
Spain's accession to the EU cross-border healthcare directive through Real Decreto 81/2014 smooths reimbursement for intra-EU patients, making the country a logical destination for elective aesthetics. The September 2024 rule that confines cosmetic surgery to board-certified plastic surgeons has paradoxically improved the nation's brand by signaling strict safety oversight. Clinics in Valencia and Malaga now bundle accommodation with HIFU-based body-contouring packages, leveraging coastal appeal to foreign visitors. High patient satisfaction ratings feed digital word-of-mouth, reinforcing a virtuous inflow cycle that elevates procedure volumes and equipment replacement needs across the Spain aesthetic devices market.
Limited Insurance Coverage for Cosmetic Procedures
Public insurance excludes elective aesthetics, obliging patients to self-fund expensive treatments. Average out-of-court settlements for cosmetic-related claims exceed EUR 33,000, illustrating the financial stakes involved. Because device amortization costs are rolled into procedure pricing, clinics must keep utilization high to remain profitable, raising affordability barriers for middle-income groups. The legal framework under Ley 29/2006 mandates rigorous proof of safety and efficacy, driving up manufacturer compliance costs that, again, echo down to consumers. Although consumer-grade light-therapy masks and handheld RF tools are proliferating, professional equipment remains inaccessible to many Spaniards outside major cities.
Other drivers and restraints analyzed in the detailed report include:
- Growing Popularity of Minimally Invasive Treatments
- Technological Advances in Aesthetic Devices
- Shortage of Certified Aesthetic Professionals in Rural Areas
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Energy-based equipment accounted for 59.02% of Spain aesthetic devices market share in 2025 as lasers, radiofrequency, and ultrasound platforms proved versatile across multiple indications. Ultrasound-based systems are forecast to log a 15.62% CAGR through 2031, propelled by high-intensity focused ultrasound procedures that now extend to scalp rejuvenation protocols validated for androgenetic alopecia treatment.
Laser manufacturers are commercializing 1726 nm devices with real-time thermal imaging that achieve durable acne clearance without pigmentary complications. Temperature-controlled RF microneedling platforms record 86.7% patient satisfaction in clinical trials, keeping radiofrequency relevant even as lasers evolve. Non-energy alternatives such as fillers maintain share through improved rheology and tighter AEMPS oversight, while chemical peels enjoy a niche revival as cost-effective adjuncts. Microneedle rollers now fall under Class IIa rules, prompting clinics to adopt safer cartridge-based systems. Collectively, these trends ensure that the Spain aesthetic devices market continues to favor energy platforms while leaving space for targeted innovation in adjunct categories.
Complete Report Scope:
- By Device Type
- Energy-based Devices
- Laser-based
- Light-based (IPL)
- Radio-frequency-based
- Ultrasound-based
- Cryolipolysis & Plasma-based
- Non-energy-based Devices
- Botulinum Toxin
- Dermal Fillers & Threads
- Chemical Peels
- Microdermabrasion
- Implants
- Mesotherapy & Others
- Energy-based Devices
- By Application
- Skin Resurfacing & Tightening
- Body Contouring & Cellulite Reduction
- Hair Removal
- Tattoo & Pigmentation Removal
- Breast Augmentation
- Acne & Scar Treatment
- Other Applications
- By End User
- Hospitals
- Dermatology & Cosmetic Clinics
- Medical Spas
- Home-use Settings
List of Companies Covered in this Report:
- AbbVie (Allergan Aesthetics)
- Alma Lasers (Sisram Medical)
- Cutera
- Bausch + Lomb (Solta Medical)
- Galderma
- Hologic
- Lumenis
- Lutronic
- Candela Medical
- Venus Concept
- InMode Ltd.
- Fotona
- Sciton
- BTL
- Zimmer Aesthetics
- Apyx Medical
- WonTech
- Straumann Group (botiss aesthetics)
- Sinclair Pharma
- Laboratorios Leti
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging Population & Youthful Appearance Demand
- 4.2.2 Rising Medical Tourism in Cosmetic Procedures
- 4.2.3 Growing Popularity of Minimally-Invasive Treatments
- 4.2.4 Technological Advancements in Aesthetic Devices
- 4.2.5 Cultural Emphasis on Beauty & Wellness
- 4.2.6 Expanding Private Aesthetic Clinics in Urban Centers
- 4.3 Market Restraints
- 4.3.1 Limited Insurance Coverage for Cosmetic Procedures
- 4.3.2 Shortage of Certified Aesthetic Professionals in Rural Areas
- 4.3.3 Stringent EU Regulatory Oversight on Devices & Fillers
- 4.3.4 Economic Sensitivity of Elective Procedures
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Device Type
- 5.1.1 Energy-based Devices
- 5.1.1.1 Laser-based
- 5.1.1.2 Light-based (IPL)
- 5.1.1.3 Radio-frequency-based
- 5.1.1.4 Ultrasound-based
- 5.1.1.5 Cryolipolysis & Plasma-based
- 5.1.2 Non-energy-based Devices
- 5.1.2.1 Botulinum Toxin
- 5.1.2.2 Dermal Fillers & Threads
- 5.1.2.3 Chemical Peels
- 5.1.2.4 Microdermabrasion
- 5.1.2.5 Implants
- 5.1.2.6 Mesotherapy & Others
- 5.1.1 Energy-based Devices
- 5.2 By Application
- 5.2.1 Skin Resurfacing & Tightening
- 5.2.2 Body Contouring & Cellulite Reduction
- 5.2.3 Hair Removal
- 5.2.4 Tattoo & Pigmentation Removal
- 5.2.5 Breast Augmentation
- 5.2.6 Acne & Scar Treatment
- 5.2.7 Other Applications
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Dermatology & Cosmetic Clinics
- 5.3.3 Medical Spas
- 5.3.4 Home-use Settings
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 AbbVie (Allergan Aesthetics)
- 6.3.2 Alma Lasers (Sisram Medical)
- 6.3.3 Cutera Inc.
- 6.3.4 Bausch + Lomb (Solta Medical)
- 6.3.5 Galderma SA
- 6.3.6 Hologic Inc. (Cynosure)
- 6.3.7 Lumenis
- 6.3.8 Lutronic Corporation
- 6.3.9 Candela Medical
- 6.3.10 Venus Concept
- 6.3.11 InMode Ltd.
- 6.3.12 Fotona
- 6.3.13 Sciton Inc.
- 6.3.14 BTL Aesthetics
- 6.3.15 Zimmer Aesthetics
- 6.3.16 Apyx Medical
- 6.3.17 WonTech
- 6.3.18 Straumann Group (botiss aesthetics)
- 6.3.19 Sinclair Pharma
- 6.3.20 Laboratorios Leti
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment