|
시장보고서
상품코드
2122034
유럽의 프로세스 자동화 : 시장 점유율 분석, 업계 동향과 통계, 성장 예측(2026-2031년)Europe Process Automation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031) |
||||||
 Mordor Intelligence
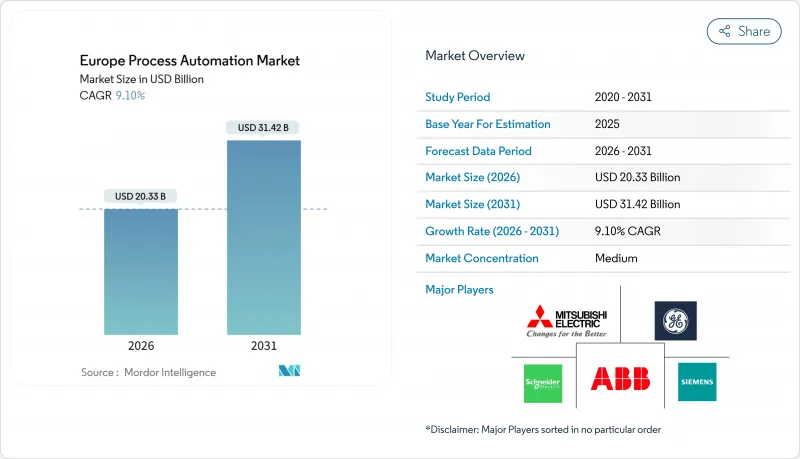
에 따르면 유럽의 프로세스 자동화 시장 규모는 2026년에 203억 3,000만 달러에 달하며, 2031년까지 314억 2,000만 달러로 확대할 것으로 예측되고 있으며, CAGR은 9.1%에 달할 전망입니다.
이 보고서는 통신 프로토콜(유선 및 무선), 시스템 유형(하드웨어 및 소프트웨어), 배포 모델(온프레미스, 클라우드, 엣지), 최종사용자 산업(석유 및 가스,화학·석유화학, 전력·유틸리티, 상수도·하수도, 식품 및 음료, 제지·펄프, 제약, 기타) 및 국가별로 분류되어 있습니다. 시장 전망은 금액(달러) 기준으로 제시되어 있습니다.
유럽 프로세스 자동화 시장의 동향 및 인사이트
에너지 효율 및 비용 절감에 대한 관심 증가
유럽의 플랜트에서는 전력 가격이 2021년 이전 수준보다 40-60% 높은 상황이 지속되고 있으며, 이에 대응하기 위해 사업자들은 가변속 드라이브, 폐열 회수 루프 및 에너지 대시보드를 도입하여 단위당 소비량을 두 자릿수 비율로 절감하고 있습니다. 2026년에 탄소 국경 조정세가 도입됨에 따라 실시간 에너지 지표는 단순한 비용 문제에서 시장 진입의 필수 요건으로 변화하고 있습니다. 한때 정유소에 국한되었던 첨단 공정 제어 소프트웨어가 현재는 용광로, 건조기, 발효조의 최적화에 활용되어, 배치별 편차 속에 숨어 있던 에너지 낭비를 드러내고 있습니다. 기계학습 모델이 히스토리안(historian)에 통합되어, 손실이 누적되기 전에 오염이나 압축기 블레이드의 마모를 예측할 수 있게 되었습니다. 에너지 대시보드와 예측 모델은 일회성 판매가 아닌 지속적인 업데이트가 필요하므로 각 벤더들은 구독형 가격 체계로 전환하고 있습니다.
브라운필드 플랜트에서의 인더스트리 4.0 및 IIoT 통합
유럽의 공정 자산의 중앙값은 30년 이상 경과했으며, 설비 투자의 대부분은 개보수에 할당되고 있습니다. 무선 진동 프로브와 적외선 카메라는 케이블 트레이가 필요하지 않기 때문에 공장은 배선 공사로 인해 가동을 중단하지 않고도 단계적으로 디지털화를 추진할 수 있습니다. 엣지 게이트웨이는 고속 루프를 로컬에서 실행하면서 엄선된 데이터를 클라우드 히스토리안으로 전송함으로써 지연과 분석의 균형을 맞추고 있습니다. 그러나 이러한 개조 열풍은 사이버 보안 위험을 높이기 때문에 사업자들은 현재 네트워크 세분화, 단방향 방화벽,및 이상 탐지에 최대 12%의 추가 예산을 배정하고 있습니다. 따라서 성장의 열쇠를 쥐고 있는 것은 브라운필드 도입에 즉시 대응할 수 있는 사이버 보안 대책이 완비된 센서·엣지 통합 패키지를 제공하는 공급업체입니다.
막대한 설비 투자와 통합의 복잡성
중규모 현장의 개조 프로젝트 비용은 종종 500만 유로(565만 달러)를 초과하지만, 그 절반 이상은 PROFIBUS, Modbus, HART 루프를 이더넷 백본에 통합하기 위한 작업 비용으로 충당되고 있습니다. 남유럽 및 동유럽의 중소기업에게는 자금 조달이 여전히 어려운 상황이기 때문에 많은 프로젝트가 단계적으로 진행되며 투자 회수 기간이 길어지고 있습니다. 엣지 센서와 하이브리드 클라우드는 아키텍처의 복잡성을 가중시키며, 운영 담당자는 온프레미스, 엣지, 클라우드라는 세 가지 서로 다른 데이터 플레인을 각각 고유한 거버넌스 규칙에 따라 관리할 수밖에 없게 되었습니다.
부문 분석
2025년 프로세스 자동화 시장에서 유선 연결이 79.16%의 점유율을 차지했습니다. 이는 결정론적인 PROFIBUS, Modbus, HART가 안전상 중요한 업무에서 계속해서 지배적인 위치를 유지하고 있기 때문입니다. 그러나 무선 노드는 연평균 성장률(CAGR) 9.46%로 성장할 것으로 예상되며, 특히 배관 매설 공사가 비용 면에서 현실적이지 않은 위험한 석유, 화학, 폐수 처리 분야에서 이러한 경향이 두드러집니다. 에머슨(Emerson)은 2025년, 유럽 정유소를 대상으로 ‘Wireless 1410’ 게이트웨이 출하량을 29% 증가시켰으며, 이를 통해 운영자는 지금까지 모니터링이 어려웠던 탱크나 플레어 스택에 계측 기기를 설치할 수 있게 되었습니다. 지방 자치단체의 상수도 사업자는 원격 양수 펌프장을 위해 배터리 구동식 LoRaWAN 수위 센서를 채택하여 토목 공사를 줄이고 있습니다.
지연 및 인증 문제로 인해 안전 계장 시스템 주변에서는 유선 백본이 여전히 자리 잡고 있습니다. 제약 업계의 비전 시스템은 고속 이미지를 네트워크로 대량으로 전송하고 있으며, 여전히 무선 대역에 과부하를 주고 있습니다. 엣지 게이트웨이가 무선 현장 데이터를 집계·압축하여, 이중화된 광섬유 백홀을 통해 히스토리안으로 전송하는 하이브리드 방식이 부상하고 있으며, 이를 통해 루프의 무결성을 유지하면서 개조 비용 부담을 경감하고 있습니다.
분산형 제어 시스템과 프로그래머블 로직 컨트롤러(PLC)가 연속 생산 플랜트의 제어 핵심을 형성하고 있으므로 2025년 매출의 56.19%를 하드웨어가 차지했습니다. 연평균 성장률(CAGR) 9.52%로 성장하고 있는 소프트웨어 매출은, 설치된 설비를 철거하지 않고도 수율을 향상시키는 예측 유지보수, 모델 예측 제어, 디지털 트윈으로의 전환을 반영하고 있습니다. 하네웰(Honeywell)에 따르면 유럽의 Experion 사용자 중 68%가 현재 최적화 기회를 파악할 수 있는 클라우드 분석 서비스를 이용하고 있습니다.
분산 제어 시스템은 석유 화학의 중합 및 생명 공학의 발효 분야에서 여전히 표준으로 자리 잡고 있습니다. 이러한 분야에서는 수백 개의 긴밀하게 연동된 루프가 결정론적 스캔을 필요로 합니다. 프로그래머블 로직 컨트롤러(PLC)는 향료 및 화장품 등의 배치 처리 분야에서 주류를 이루고 있습니다. 센서, 밸브, 모터에는 가동 중단이 발생하기 전에 고장을 감지하는 알고리즘이 내장되는 경우가 늘고 있습니다. HMI(Human-Machine Interface)는 전용 사양의 패널에서 태블릿 브라우저 대시보드로 전환되고 있으며, 이로 인해 설비 투자(CAPEX)는 감소하는 반면, 사이버 공격자에 대한 공격 표면은 확대되고 있습니다.
기타 혜택:
- 엑셀 형식의 시장 예측(ME) 시트
- 3개월간의 애널리스트 지원
자주 묻는 질문
목차
제1장 서론
제2장 조사 방법
제3장 개요
제4장 시장 구도
제5장 시장 규모와 성장 예측
제6장 경쟁 구도
제7장 시장 기회와 향후 전망
KSA 26.09.03According to Mordor Intelligence, the Europe process automation market size reached USD 20.33 billion in 2026 and is projected to climb to USD 31.42 billion by 2031, reflecting a 9.1% CAGR.
This report is Segmented by Communication Protocol (Wired, and Wireless), System Type (Hardware, and Software), Deployment Model (On-Premise, Cloud, Edge), End-User Industry (Oil and Gas, Chemical and Petrochemical, Power and Utilities, Water and Wastewater, Food and Beverage, Paper and Pulp, Pharmaceutical, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
Europe Process Automation Market Trends and Insights
Growing Emphasis on Energy Efficiency and Cost Reduction
European plants are contending with electricity prices that remain 40-60% above pre-2021 levels; therefore, operators are installing variable-speed drives, waste-heat recovery loops, and energy dashboards that reduce specific consumption by double-digit percentages. As carbon-border taxes begin in 2026, real-time energy metrics are transforming from a cost topic into a market-access prerequisite. Advanced process control software, once limited to refineries, now optimizes ovens, dryers, and fermenters, revealing energy waste hidden behind batch variability. Machine-learning models are being layered on historians to predict fouling or compressor-blade wear before losses compound. Vendors are shifting toward subscription pricing because energy dashboards and predictive models require continual updates rather than one-off sales.
Industry 4.0 and IIoT Integration Across Brownfield Plants
With the median European process asset older than three decades, retrofits dominate capex. Wireless vibration probes and infrared cameras bypass cable trays, letting plants digitalize piecemeal instead of shutting down for rewiring. Edge gateways run fast loops locally yet pass curated data to cloud historians, balancing latency and analytics. The retrofit wave, however, increases cybersecurity exposure, so operators now allocate up to 12% more for network segmentation, one-way firewalls, and anomaly detection. Growth, therefore, hinges on suppliers that offer pre-integrated cyber-secure sensor-edge bundles ready for brownfield deployment.
High Capital Expenditure and Integration Complexity
Retrofit projects often top EUR 5 million (USD 5.65 million) for mid-sized sites, and more than half of that sum finances integration labor that stitches PROFIBUS, Modbus, and HART loops into Ethernet backbones. Financing remains scarce for smaller firms in Southern and Eastern Europe, so many projects proceed in phases that extend the payback period. Edge sensors and hybrid clouds increase architectural complexity, forcing operators to manage three distinct data planes: on-premises, edge, and cloud, each with its own governance rules.
Other drivers and restraints analyzed in the detailed report include:
- EU Decarbonisation Policies Driving Retrofit Automation
- Digital Product Passport Mandate Boosting Traceability Automation
- Cybersecurity Compliance Costs in OT Networks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Wired links secured 79.16% of the 2025 process automation market share, as deterministic PROFIBUS, Modbus, and HART continue to dominate safety-critical duties. Wireless nodes, however, are set to grow at a 9.46% CAGR, particularly in hazardous oil, chemical, and wastewater zones where conduit trenching is cost-prohibitive. Emerson shipped 29% more Wireless 1410 gateways into European refineries in 2025, enabling operators to instrument tanks and flare stacks that had previously run blind. Municipal water utilities choose battery-powered LoRaWAN level sensors for remote lift stations, cutting civil works.
Latency and certification keep wired backbones entrenched around safety instrumented systems. Pharmaceutical vision systems flood networks with high-speed images that still overload wireless bands. A hybrid future is emerging where edge gateways aggregate wireless field data, compress it, and then forward it to historians over redundant fiber backhauls, maintaining loop integrity while easing retrofit economics.
Hardware captured 56.19% of 2025 revenue as distributed control systems and programmable logic controllers form the control core of continuous plants. Software revenues, growing at a 9.52% CAGR, reflect a pivot toward predictive maintenance, model-predictive control, and digital twins that boost yields without requiring the removal of installed equipment. Honeywell notes that 68% of its European Experion customers now subscribe to cloud analytics that surface optimization opportunities.
Distributed control systems remain the standard for petrochemical polymerization and biotech fermentation, where hundreds of tightly coupled loops demand deterministic scans. Programmable logic controllers dominate batch sectors such as flavors and fragrances. Sensors, valves, and motors are increasingly bundled with algorithms that flag failures before downtime occurs. Human-machine interfaces migrate from proprietary panels to browser dashboards on tablets, shrinking capex but widening the threat surface for cyber attackers.
Complete Report Scope:
- By Communication Protocol
- Wired
- Wireless
- By System Type
- Hardware
- Supervisory Control and Data Acquisition System (SCADA)
- Distributed Control System (DCS)
- Programmable Logic Controller (PLC)
- Manufacturing Execution System (MES)
- Valves and Actuators
- Electric Motors
- Human Machine Interface (HMI)
- Process Safety Systems
- Sensors and Transmitters
- Software
- Advanced Process Control (APC)
- Data Analytics and Reporting Software
- Other Software
- Hardware
- By Deployment Model
- On-Premise
- Cloud
- Edge
- By End-User Industry
- Oil and Gas
- Chemical and Petrochemical
- Power and Utilities
- Water and Wastewater
- Food and Beverage
- Paper and Pulp
- Pharmaceutical
- Other End-User Industry
- By Country
- United Kingdom
- Germany
- France
- Rest of Europe
List of Companies Covered in this Report:
- ABB Ltd
- Siemens AG
- Schneider Electric SE
- Emerson Electric Co.
- Rockwell Automation Inc.
- Honeywell International Inc.
- Mitsubishi Electric Corporation
- Yokogawa Electric Corporation
- General Electric Co.
- Delta Electronics Inc.
- Eaton Corporation
- Fuji Electric Co. Ltd.
- Endress+Hauser Group
- Bosch Rexroth AG
- Omron Corporation
- KUKA AG
- Phoenix Contact GmbH and Co. KG
- Festo SE and Co. KG
- Valmet Oyj
- Hitachi Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Emphasis on Energy Efficiency and Cost Reduction
- 4.2.2 Demand for Safety Automation Systems
- 4.2.3 Industry 4.0 and IIoT Integration Across Brownfield Plants
- 4.2.4 EU Decarbonisation Policies Driving Retrofit Automation
- 4.2.5 Digital Product Passport Mandate Boosting Traceability Automation
- 4.2.6 Green Hydrogen Pilot Plants Requiring Modular Automation
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure and Integration Complexity
- 4.3.2 Cybersecurity Compliance Costs in OT Networks
- 4.3.3 Ageing Workforce and OT-IT Skills Shortage
- 4.3.4 Vendor Lock-in Concerns With Proprietary Architectures
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
- 4.9 Analysis of Industrial Automation Hubs in United Kingdom, Germany and France
- 4.10 Assessment of the Impact of COVID-19 on the Process Automation Industry in Europe
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Communication Protocol
- 5.1.1 Wired
- 5.1.2 Wireless
- 5.2 By System Type
- 5.2.1 Hardware
- 5.2.1.1 Supervisory Control and Data Acquisition System (SCADA)
- 5.2.1.2 Distributed Control System (DCS)
- 5.2.1.3 Programmable Logic Controller (PLC)
- 5.2.1.4 Manufacturing Execution System (MES)
- 5.2.1.5 Valves and Actuators
- 5.2.1.6 Electric Motors
- 5.2.1.7 Human Machine Interface (HMI)
- 5.2.1.8 Process Safety Systems
- 5.2.1.9 Sensors and Transmitters
- 5.2.2 Software
- 5.2.2.1 Advanced Process Control (APC)
- 5.2.2.2 Data Analytics and Reporting Software
- 5.2.2.3 Other Software
- 5.2.1 Hardware
- 5.3 By Deployment Model
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.3.3 Edge
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Chemical and Petrochemical
- 5.4.3 Power and Utilities
- 5.4.4 Water and Wastewater
- 5.4.5 Food and Beverage
- 5.4.6 Paper and Pulp
- 5.4.7 Pharmaceutical
- 5.4.8 Other End-User Industry
- 5.5 By Country
- 5.5.1 United Kingdom
- 5.5.2 Germany
- 5.5.3 France
- 5.5.4 Rest of Europe
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)}
- 6.4.1 ABB Ltd
- 6.4.2 Siemens AG
- 6.4.3 Schneider Electric SE
- 6.4.4 Emerson Electric Co.
- 6.4.5 Rockwell Automation Inc.
- 6.4.6 Honeywell International Inc.
- 6.4.7 Mitsubishi Electric Corporation
- 6.4.8 Yokogawa Electric Corporation
- 6.4.9 General Electric Co.
- 6.4.10 Delta Electronics Inc.
- 6.4.11 Eaton Corporation
- 6.4.12 Fuji Electric Co. Ltd.
- 6.4.13 Endress+Hauser Group
- 6.4.14 Bosch Rexroth AG
- 6.4.15 Omron Corporation
- 6.4.16 KUKA AG
- 6.4.17 Phoenix Contact GmbH and Co. KG
- 6.4.18 Festo SE and Co. KG
- 6.4.19 Valmet Oyj
- 6.4.20 Hitachi Ltd.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Investment Analysis and Market Outlook